


US Manufacturing Survey Strongest Since May 2022 On AI Spend, Prices Paid Spike
Following the explosive growth signaled by S&P Global's PMI data last week, this week we get a final look for September's Manufacturing surveys and fresh data from ISM.
S&P Global's final September read for US Manufacturing dipped from the preliminary level but remains at its strongest since May 2022.
ISM's September survey of US Manufacturers also dipped at the headline level (54.5 vs 55.0 exp), but remains near multi-year highs.
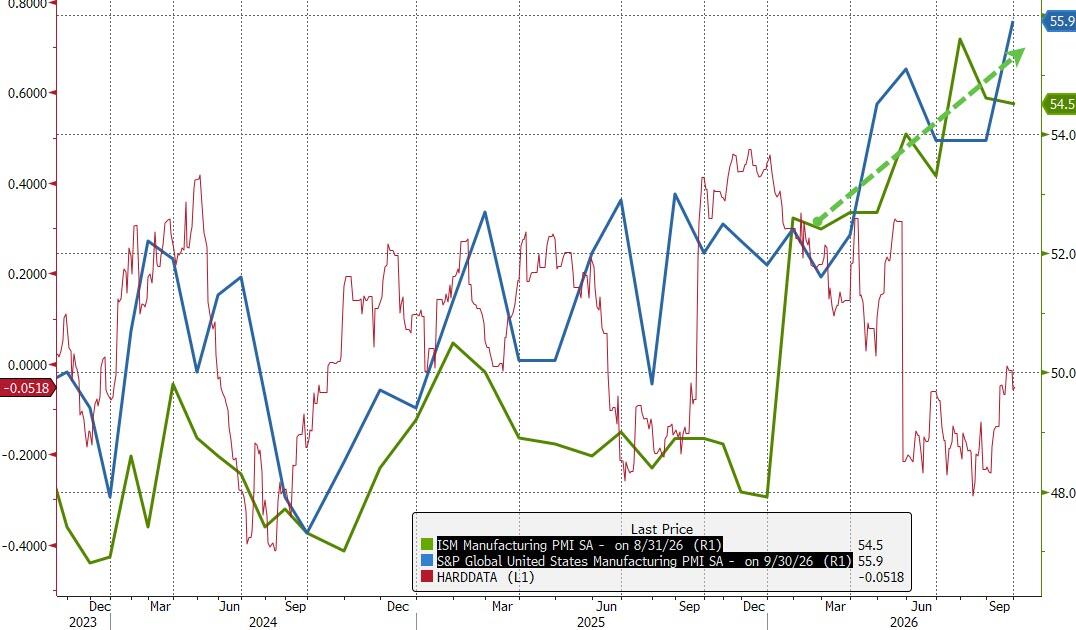
“September has seen the pace of US manufacturing growth pick up a gear again," said Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, adding that PMI hit its highest since May 2022 as a surge in new orders encouraged factories to lift output sharply higher and take on workers in increasing numbers.
Once again, it was the domestic market that underpinned demand growth as new export orders fell for the fifteenth successive month.
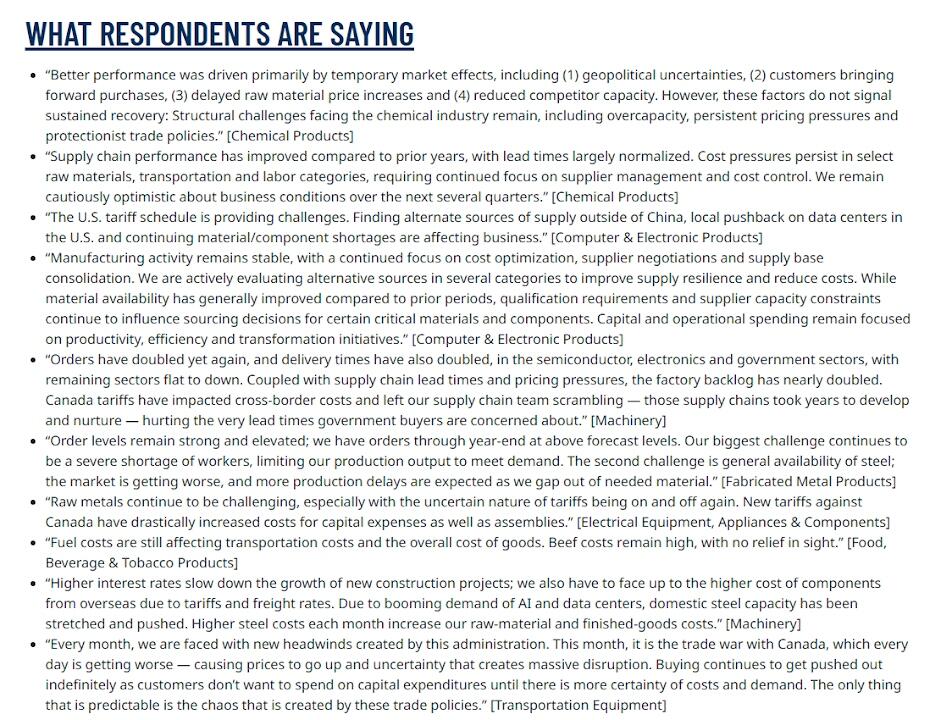
Respondents were mixed...
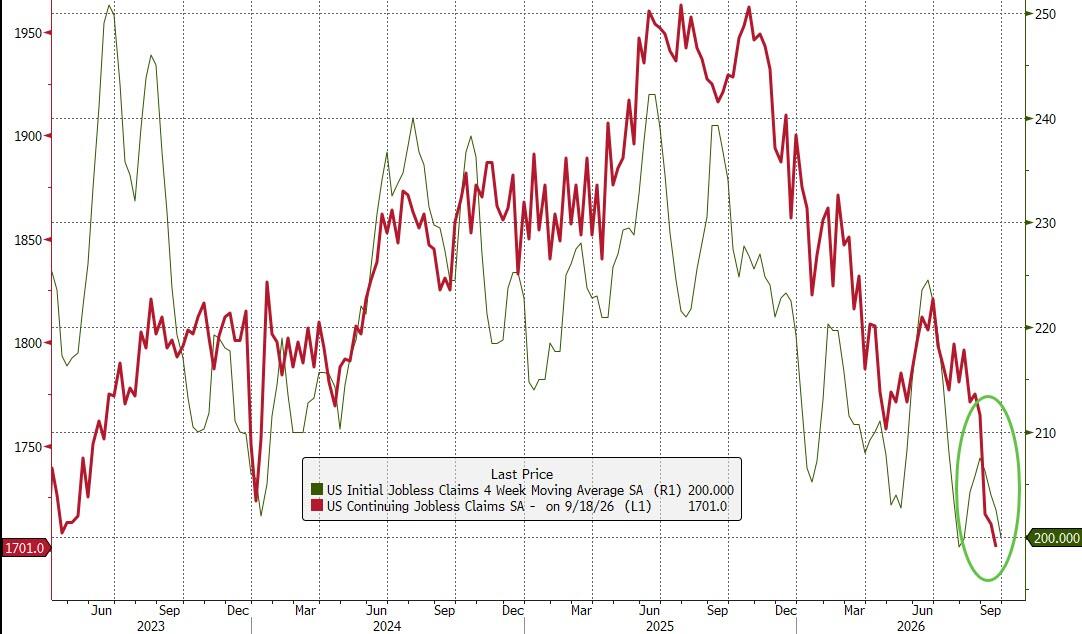
Building on that strength, earlier we saw the number of Americans filing for unemployment benefits for the first drop back below the 200k Maginot Line (197k), signaling very little strain in the labor market (at least on the 'firing' side, while JOLTS recently signaled some pain on the 'hiring' side of the equation). Continuing Claims also fell back to its lowest level since March 2023...
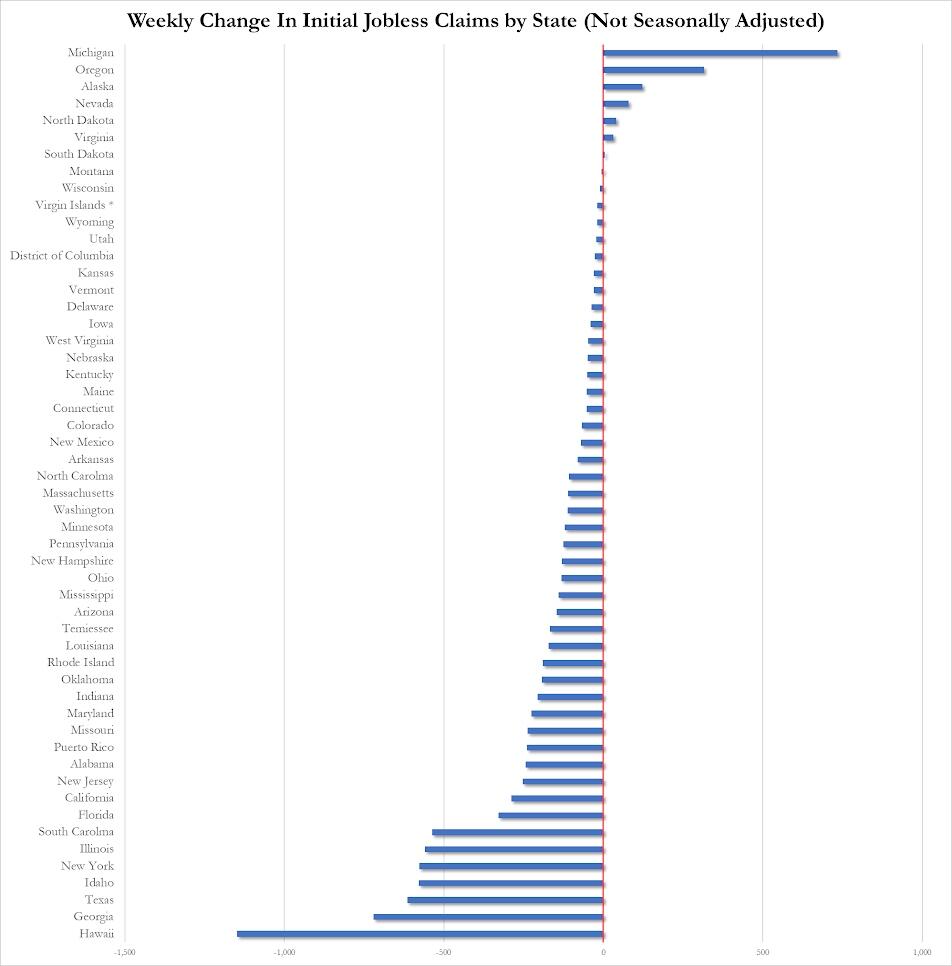
Hawaii saw the biggest decline in jobless claims last week while Michigan saw the biggest rise...
As S&P Global's Williamson concludes, while sending an encouraging signal for further growth of manufacturing capacity in the coming months, the indication that demand is outstripping supply also means inflationary pressures remain a key area of concern, especially amid high oil prices.
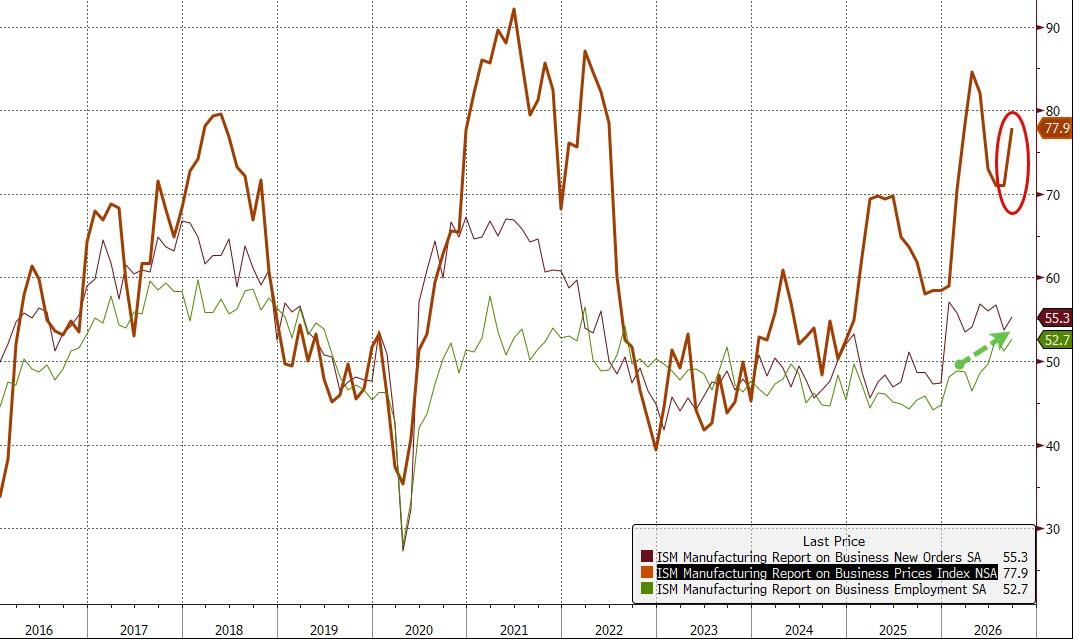
Indeed, under the surface of the ISM data, we saw Prices Paid soar and both New Orders and Employment bounce...
"The combination of accelerating growth, increased hiring and elevated price gauges will add to speculation of a further imminent rate hike from the FOMC."
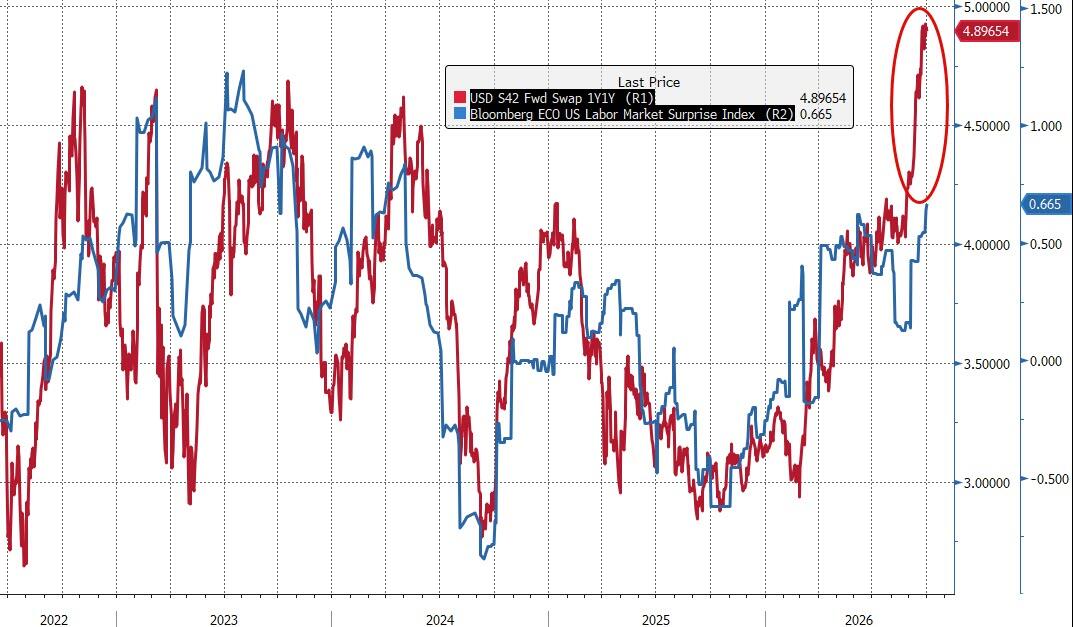
And, it is worth noting that the SOFR market is pricing a dramatically more hawkish Fed over the next year or two than the labor market data would suggest...
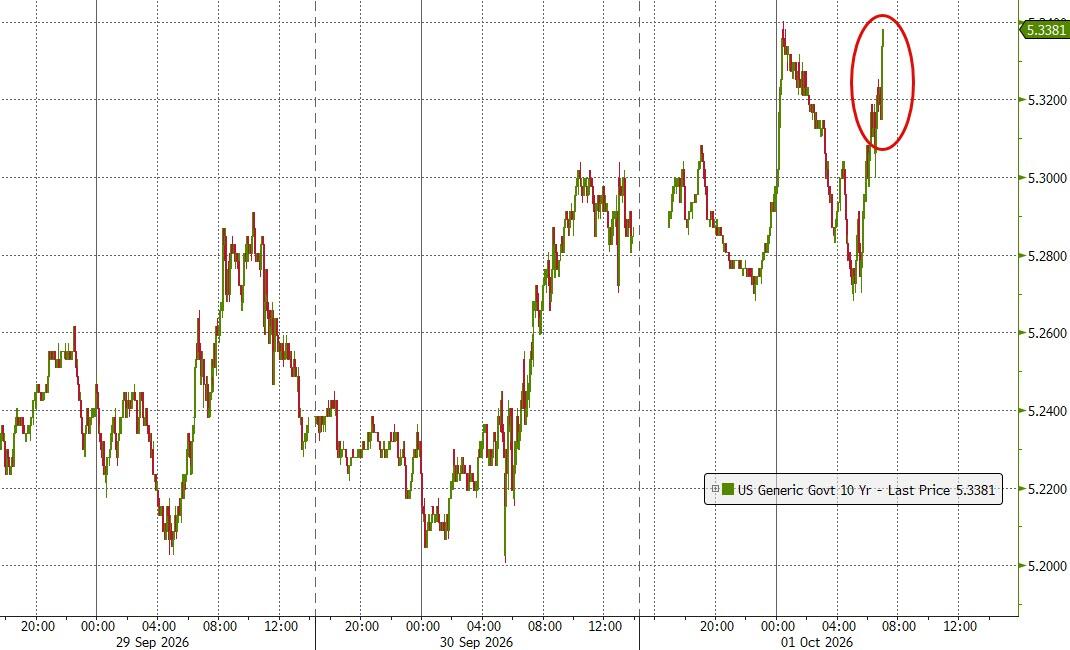
The 10Y yield spiked to the highs of the day on the PMIs...
Clearly the market thinks The Fed is favoring one side of its mandate much more dramatically than the other.
Tyler Durden Thu, 10/01/2026 - 10:05
Continue reading...
[ H/T ZeroHedge ]
Following the explosive growth signaled by S&P Global's PMI data last week, this week we get a final look for September's Manufacturing surveys and fresh data from ISM.
S&P Global's final September read for US Manufacturing dipped from the preliminary level but remains at its strongest since May 2022.
ISM's September survey of US Manufacturers also dipped at the headline level (54.5 vs 55.0 exp), but remains near multi-year highs.
“September has seen the pace of US manufacturing growth pick up a gear again," said Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, adding that PMI hit its highest since May 2022 as a surge in new orders encouraged factories to lift output sharply higher and take on workers in increasing numbers.
Once again, it was the domestic market that underpinned demand growth as new export orders fell for the fifteenth successive month.
Respondents were mixed...
Building on that strength, earlier we saw the number of Americans filing for unemployment benefits for the first drop back below the 200k Maginot Line (197k), signaling very little strain in the labor market (at least on the 'firing' side, while JOLTS recently signaled some pain on the 'hiring' side of the equation). Continuing Claims also fell back to its lowest level since March 2023...
Hawaii saw the biggest decline in jobless claims last week while Michigan saw the biggest rise...
As S&P Global's Williamson concludes, while sending an encouraging signal for further growth of manufacturing capacity in the coming months, the indication that demand is outstripping supply also means inflationary pressures remain a key area of concern, especially amid high oil prices.
Indeed, under the surface of the ISM data, we saw Prices Paid soar and both New Orders and Employment bounce...
"The combination of accelerating growth, increased hiring and elevated price gauges will add to speculation of a further imminent rate hike from the FOMC."
And, it is worth noting that the SOFR market is pricing a dramatically more hawkish Fed over the next year or two than the labor market data would suggest...
The 10Y yield spiked to the highs of the day on the PMIs...
Clearly the market thinks The Fed is favoring one side of its mandate much more dramatically than the other.
Tyler Durden Thu, 10/01/2026 - 10:05
Continue reading...
[ H/T ZeroHedge ]