Truist Slaps Nike With Sell Rating As Jordan Franchise Implodes
Nike's rally from roughly $34 a share in October to above $40 by midweek has done little to ease Wall Street analysts' skepticism about its turnaround strategy.
Earlier this week, UBS analyst Pilar Rocafort told clients, "It's still not time to buy Nike." Truist Securities reinforced Rocafort's caution on the stock in a note Thursday morning, downgrading the shares to Sell from Hold, citing "risks across the portfolio" and "an inflated valuation."
"NKE shares are up 19% over the past ~month (vs S&P flat), which we believe reflects positive sector rotations rather than an improvement in underlying fundamentals," Truist Securities retail analyst Joseph Civello wrote in a note.
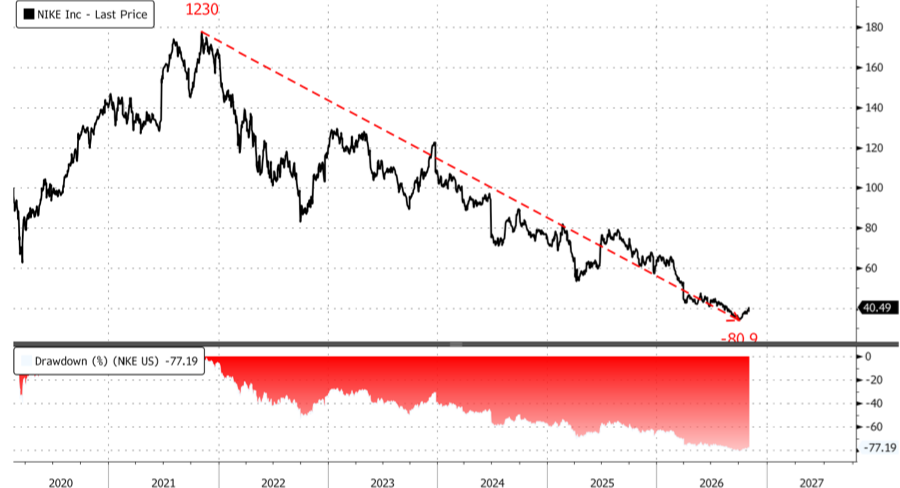
Civello maintained a $29 price target and warned that fading Jordan demand, deepening weakness in China, and mounting competition threaten an already expensive stock.
How expensive is Nike at around $40 a share?
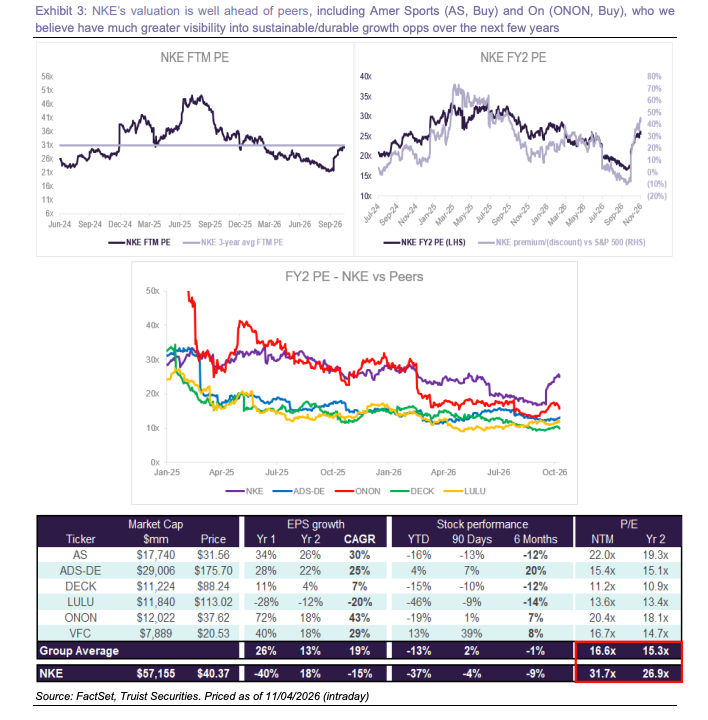
Well, Civello said its valuation is currently around 27 times second-year forward earnings, compared with about 15 times for peers. He said prices look cheap after the multi-year bear market, but anyone buying the stock today is paying a steep premium for a turnaround whose timeline keeps slipping.
The Jordan franchise is a key problem, the analyst continued:
On top of this all, the analyst warned that the downturn in the Chinese market has yet to conclude:
To sum up the note, these mounting pressures suggest Nike's latest rally has outpaced its underlying recovery. Civello maintained his $29 price target, signaling the turnaround timeline could be longer than expected.
Tyler Durden Thu, 11/05/2026 - 08:45
Continue reading...
[ H/T ZeroHedge ]
Nike's rally from roughly $34 a share in October to above $40 by midweek has done little to ease Wall Street analysts' skepticism about its turnaround strategy.
Earlier this week, UBS analyst Pilar Rocafort told clients, "It's still not time to buy Nike." Truist Securities reinforced Rocafort's caution on the stock in a note Thursday morning, downgrading the shares to Sell from Hold, citing "risks across the portfolio" and "an inflated valuation."
"NKE shares are up 19% over the past ~month (vs S&P flat), which we believe reflects positive sector rotations rather than an improvement in underlying fundamentals," Truist Securities retail analyst Joseph Civello wrote in a note.
Civello maintained a $29 price target and warned that fading Jordan demand, deepening weakness in China, and mounting competition threaten an already expensive stock.
How expensive is Nike at around $40 a share?
Well, Civello said its valuation is currently around 27 times second-year forward earnings, compared with about 15 times for peers. He said prices look cheap after the multi-year bear market, but anyone buying the stock today is paying a steep premium for a turnaround whose timeline keeps slipping.
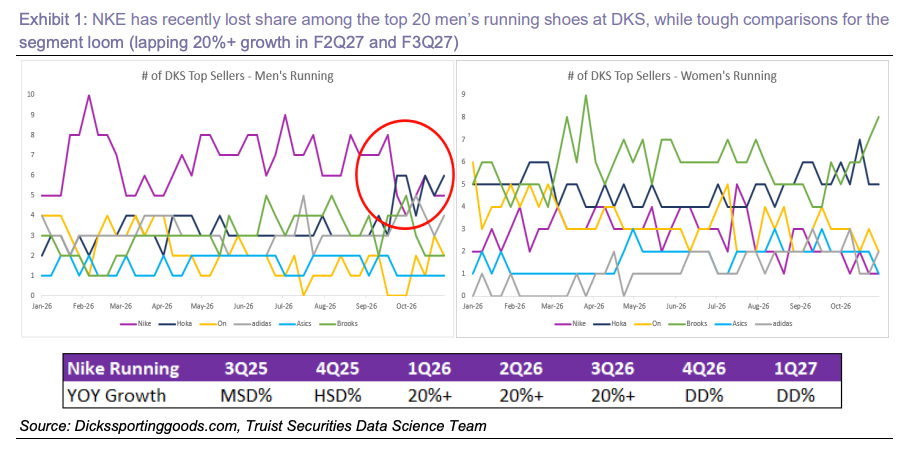
The Jordan franchise is a key problem, the analyst continued:
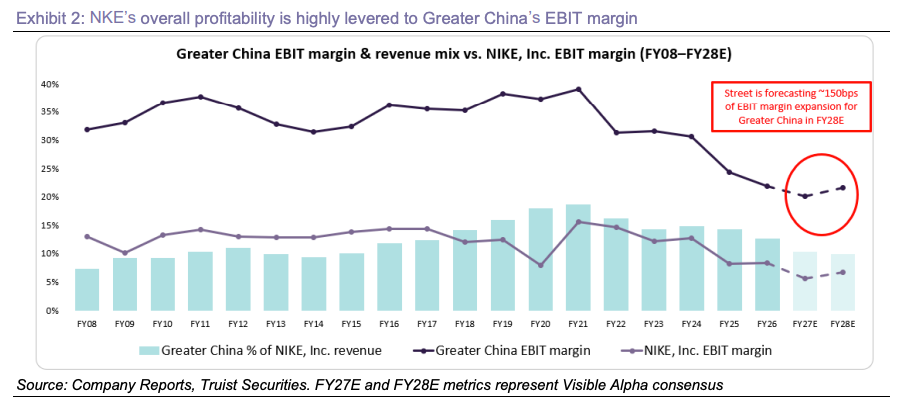
On top of this all, the analyst warned that the downturn in the Chinese market has yet to conclude:
We think visibility into where/when China bottoms is very limited – Despite recently becoming CFO on 8/17, Dave Denton materially slashed the China outlook, characterizing prior internal expectations as overly optimistic. Guidance now calls for the region to get worse through the year (vs F1Q's 26% CC declines) with the digital cleanup expected to take “multiple seasons.”
In our view, mgmt's historical optimism that trends in the country would eventually improve led to them getting complacent in the region, which when combined with broadly stale innovation/marketing has driven meaningful pressure on brand equity. We struggle to identify a clear catalyst path for reaccelerating demand in the region in the NT/MT, especially as competition from local & other western brands continues to get more intense.
To sum up the note, these mounting pressures suggest Nike's latest rally has outpaced its underlying recovery. Civello maintained his $29 price target, signaling the turnaround timeline could be longer than expected.
Tyler Durden Thu, 11/05/2026 - 08:45
Continue reading...
[ H/T ZeroHedge ]