


Key Events This Week: CPI, PPI, Earnings Start And Warsh Speaks
This week markets will navigate the latest complex geopolitical news amid a barrage of news including the latest US inflation data, with September CPI on Wednesday and PPI on Thursday, the final readings before the Fed’s October 28 meeting, alongside a broader US activity pulse from retail sales (Thursday) and industrial production (Friday). After Columbus Day today where US bond markets will be closed but equities open, Q3 US earnings season also gets properly under way tomorrow, led by the big US banks, while across the globe ASML (Wednesday) and TSMC (Thursday) should provide another useful read on the AI capex cycle. Elsewhere, China has September inflation and trade data on Wednesday, UK monthly GDP is due Thursday, and the IMF/World Bank meetings run through the week, with the IMF’s latest World Economic Outlook out tomorrow and a long list of central-bank speakers. Thursday we also get what may be a key speech from Warsh at the IMF when the Fed Chairman participates in a fireside chat with IMF managing director Kristalina Georgieva at the IMF Annual Meetings in Bangkok; a moderated Q&A is expected.
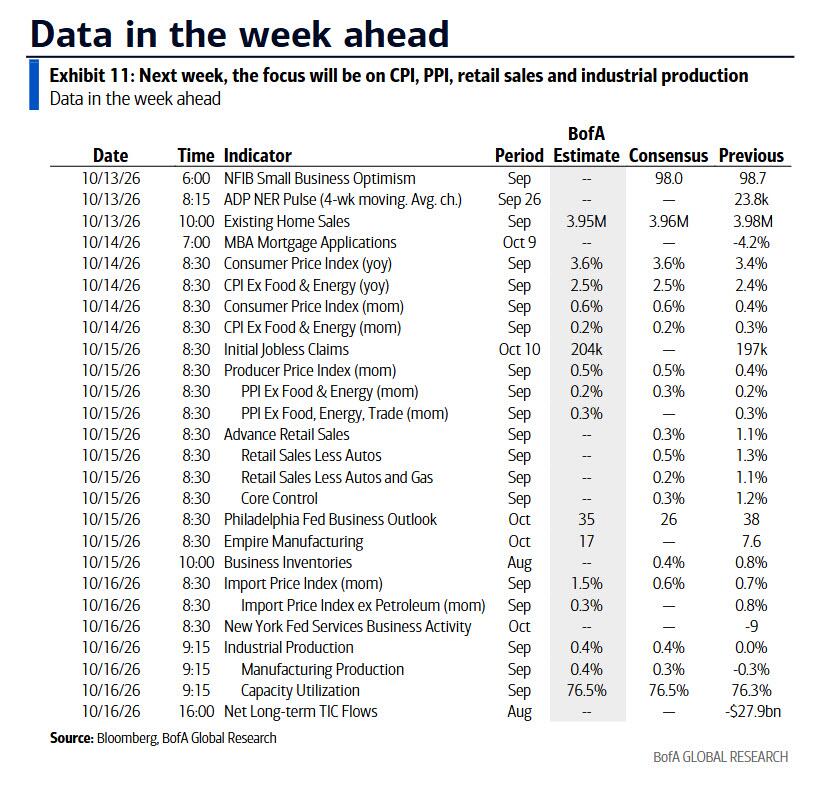
Going onto more detail on the week ahead, the main event is US CPI on Wednesday. Economists expect headline CPI to rise +0.6% MoM in September, up from +0.40% in August, largely because seasonally adjusted motor-fuel prices are expected to jump 9.6%. That would lift headline inflation to around 3.6% YoY from 3.4%. The core picture should be much softer: economists expect +0.2% MoM, down from +0.3%, still this will be enough to push the annual rate higher to 2.5% from 2.4%. Within core, DB economists expect goods prices to be unchanged, with lower used-car and medical-care commodity prices offset by firmer recreation and IT goods. On services, last month’s jump in wireless prices should roll off, although higher jet-fuel costs should support airfares. The contrast between a fuel-driven headline acceleration and a softer underlying core print will clearly be important for the Fed, particularly given recent messaging that further tightening may be needed but is not urgent.
The inflation story does not end there. PPI follows on Thursday and import prices on Friday, both important for mapping the CPI details into core PCE. These are the last inflation data Fed officials will see before the October FOMC meeting. DB economists’ ex-ante estimate is for core PCE (released on October 29th, the day after the FOMC) to rise around +0.21% MoM, leaving the annual rate roughly steady at 3.0%. If they are close to the economists’ forecasts, the DB team thinks the Fed can remain on hold on October 28 and wait for more information before December, especially with the midterms just a week or so later. Chair Warsh’s fireside chat with IMF Managing Director Georgieva on Thursday evening will therefore be particularly interesting, as it is the final Fed appearance before the communications blackout. On activity, DB economists expect total September retail sales to be unchanged (Thursday) and industrial production to rise +0.2% MoM (Friday). The Fed’s Beige Book is also out Wednesday. Today is Columbus Day, so US bond markets are closed although equities remain open.
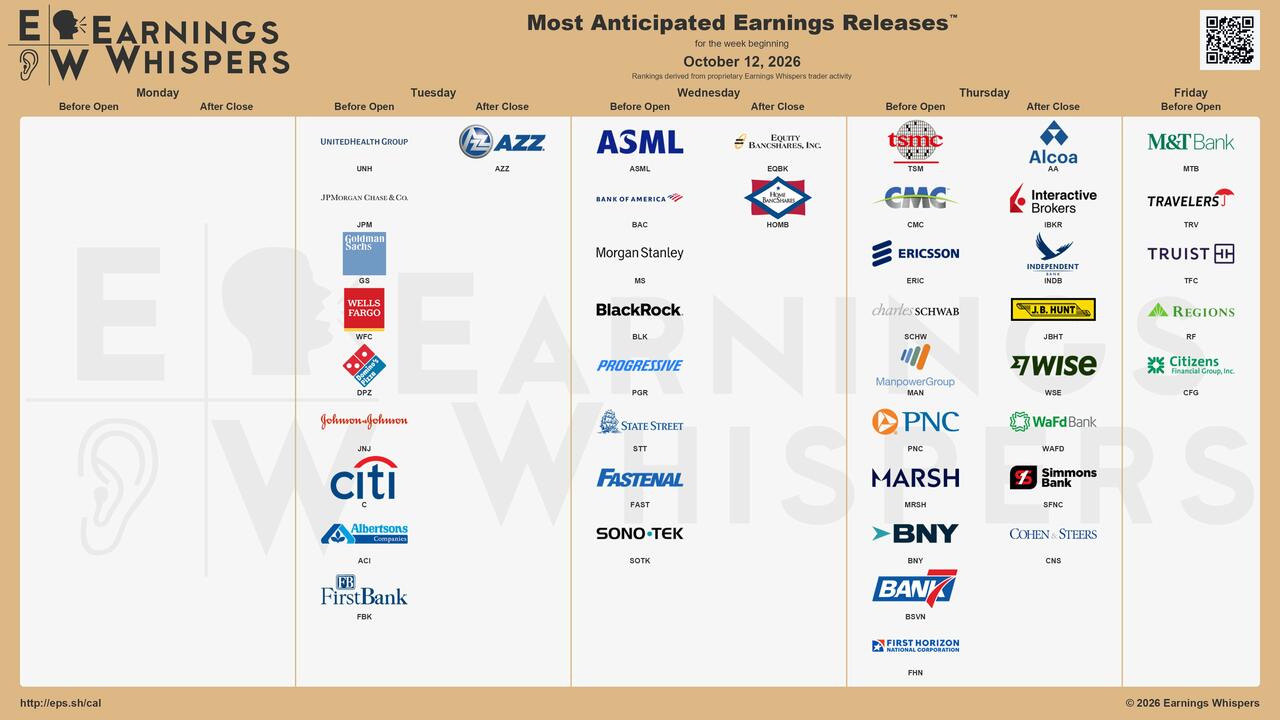
Earnings season is another important part of the week. JPMorgan, Goldman Sachs, Wells Fargo and Citigroup report tomorrow, followed by Bank of America, Morgan Stanley and BlackRock on Wednesday. ASML reports Wednesday and TSMC on Thursday. Deutsche's US equity strategists expect S&P 500 earnings growth to remain at a record 34% YoY in Q3, versus consensus at 27%. Their view is that consensus is again embedding too much of a slowdown, leaving scope for another quarter of above-average beats. In Europe, equity strategists expect earnings growth to reach 25% in Q3, 5 pp above consensus (their full preview is here). So it should be a very strong earnings season on both sides of the Atlantic and indeed across the globe.
Day-by-day calendar of events
Monday October 12
Tuesday October 13
Wednesday October 14
Thursday October 15
Friday October 16
* * *
Finally, looking at just the US, the key economic data releases this week are the CPI report on Wednesday and the retail sales report on Thursday. There are several speaking engagements with Fed officials scheduled this week, including an event with Chairman Warsh on Thursday.
Monday, October 12
Tuesday, October 13
Wednesday, October 14
Thursday, October 15
Friday, October 16
Source: DB, Goldman
Tyler Durden Mon, 10/12/2026 - 12:35
Continue reading...
[ H/T ZeroHedge ]
This week markets will navigate the latest complex geopolitical news amid a barrage of news including the latest US inflation data, with September CPI on Wednesday and PPI on Thursday, the final readings before the Fed’s October 28 meeting, alongside a broader US activity pulse from retail sales (Thursday) and industrial production (Friday). After Columbus Day today where US bond markets will be closed but equities open, Q3 US earnings season also gets properly under way tomorrow, led by the big US banks, while across the globe ASML (Wednesday) and TSMC (Thursday) should provide another useful read on the AI capex cycle. Elsewhere, China has September inflation and trade data on Wednesday, UK monthly GDP is due Thursday, and the IMF/World Bank meetings run through the week, with the IMF’s latest World Economic Outlook out tomorrow and a long list of central-bank speakers. Thursday we also get what may be a key speech from Warsh at the IMF when the Fed Chairman participates in a fireside chat with IMF managing director Kristalina Georgieva at the IMF Annual Meetings in Bangkok; a moderated Q&A is expected.
Going onto more detail on the week ahead, the main event is US CPI on Wednesday. Economists expect headline CPI to rise +0.6% MoM in September, up from +0.40% in August, largely because seasonally adjusted motor-fuel prices are expected to jump 9.6%. That would lift headline inflation to around 3.6% YoY from 3.4%. The core picture should be much softer: economists expect +0.2% MoM, down from +0.3%, still this will be enough to push the annual rate higher to 2.5% from 2.4%. Within core, DB economists expect goods prices to be unchanged, with lower used-car and medical-care commodity prices offset by firmer recreation and IT goods. On services, last month’s jump in wireless prices should roll off, although higher jet-fuel costs should support airfares. The contrast between a fuel-driven headline acceleration and a softer underlying core print will clearly be important for the Fed, particularly given recent messaging that further tightening may be needed but is not urgent.
The inflation story does not end there. PPI follows on Thursday and import prices on Friday, both important for mapping the CPI details into core PCE. These are the last inflation data Fed officials will see before the October FOMC meeting. DB economists’ ex-ante estimate is for core PCE (released on October 29th, the day after the FOMC) to rise around +0.21% MoM, leaving the annual rate roughly steady at 3.0%. If they are close to the economists’ forecasts, the DB team thinks the Fed can remain on hold on October 28 and wait for more information before December, especially with the midterms just a week or so later. Chair Warsh’s fireside chat with IMF Managing Director Georgieva on Thursday evening will therefore be particularly interesting, as it is the final Fed appearance before the communications blackout. On activity, DB economists expect total September retail sales to be unchanged (Thursday) and industrial production to rise +0.2% MoM (Friday). The Fed’s Beige Book is also out Wednesday. Today is Columbus Day, so US bond markets are closed although equities remain open.
Earnings season is another important part of the week. JPMorgan, Goldman Sachs, Wells Fargo and Citigroup report tomorrow, followed by Bank of America, Morgan Stanley and BlackRock on Wednesday. ASML reports Wednesday and TSMC on Thursday. Deutsche's US equity strategists expect S&P 500 earnings growth to remain at a record 34% YoY in Q3, versus consensus at 27%. Their view is that consensus is again embedding too much of a slowdown, leaving scope for another quarter of above-average beats. In Europe, equity strategists expect earnings growth to reach 25% in Q3, 5 pp above consensus (their full preview is here). So it should be a very strong earnings season on both sides of the Atlantic and indeed across the globe.
Day-by-day calendar of events
Monday October 12
- Data: Denmark September CPI
- Central banks: Fed's Hammack speaks, BoE’s Breeden and Mann speak
- Other: IMF and World Bank meetings begin in Bangkok (through October 18), US Columbus Day (bond markets closed)
Tuesday October 13
- Data: US September NFIB small business optimism, existing home sales, Japan September PPI, bank lending, Germany August current account balance
- Central banks: Fed's Waller, Barkin and Collins speak, BoE’s Greene and Dhingra speak
- Earnings: JPMorgan, Johnson & Johnson, UnitedHealth, Goldman Sachs, Wells Fargo, Citigroup
- Other: IMF’s world economic outlook
Wednesday October 14
- Data: US September CPI, China September CPI, PPI, trade balance, Japan September M2, M3, Germany September wholesale price index, Canada August building permits
- Central banks: Fed releases Beige Book, Fed's Bowman and Barkin speak, ECB's Lagarde, Moulin, Zigman, Escriva, Makhlouf and Pereira speak, BoE’s Breeden and Pill speak, BoC’s Macklem speaks
- Earnings: ASML, Bank of America, Morgan Stanley, Blackrock, Progressive
Thursday October 15
- Data: US September retail sales, PPI, October Empire manufacturing index, Philadelphia Fed business outlook, August business inventories, initial jobless claims, UK August monthly GDP, Japan August core machine orders, capacity utilisation, Italy August general government debt, Eurozone August industrial production, Canada August manufacturing sales, Australia September labour force survey
- Central banks: Fed's Hammack speaks, ECB's Kocher, Simkus, Pereira and Moulin speak, BoJ's Koeda speaks, BoE’s Pill, Greene and Breeden speak, BoC’s Rogers speaks
- Earnings: TSMC, Charles Schwab, Interactive Brokers, Prologis, Bank of New York Mellon, Nordea
- Other: European Council meeting (through October 16), G20 finance ministers and central bank governors meeting
Friday October 16
- Data: US October New York Fed services business activity, September industrial production, capacity utilisation, import price index, export price index, August total net TIC flows, Italy August trade balance, Eurozone August trade balance, Canada September existing home sales, housing starts, August international securities transactions
- Central banks: Fed's Warsh speaks, ECB's Nagel speaks, BoJ's Uchida speaks, BoE's Bailey speaks, BoC’s Macklem and Alexopoulos speak
* * *
Finally, looking at just the US, the key economic data releases this week are the CPI report on Wednesday and the retail sales report on Thursday. There are several speaking engagements with Fed officials scheduled this week, including an event with Chairman Warsh on Thursday.
Monday, October 12
- There are no major data releases scheduled. SIFMA recommends bond markets remain closed in observance of Columbus Day.
- 12:10 PM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will speak on the outlook and monetary policy at the annual meeting of the National Association for Business Economics. Speech text and moderated Q&A are expected. On October 11, President Hammack said that “when you see the amount of capital that’s flowing in, when you see the profits that are being created, to me, this does not look like an economy that has restraint.” Commenting on additional increases to the federal funds rate, she noted that “smaller, more frequent adjustments are preferable to larger ones.”
Tuesday, October 13
- 03:45 AM Fed Governor Waller speaks: Fed Governor Christopher Waller will speak on economic policy in the age of AI at the Bloomberg New Economy Forum in New Delhi, India. On October 8, Governor Waller said that “if the economic data continue to come in as expected, I anticipate additional hikes to support a timelier return of inflation to our 2 percent goal. But there is some flexibility about when those hikes will occur. The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time.”
- 06:00 AM NFIB small business optimism index, September (consensus 98.2, last 98.7)
- 10:00 AM Existing home sales, September (GS -1.0%, consensus -0.5%, last -2.0%)
- 01:00 PM Richmond Fed Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will take part in a discussion at Howard University School of Business in Washington, DC. Moderated Q&A is expected. On September 22, President Barkin said that “We are committed to returning inflation sustainably to our 2 percent target. [The September] hike will help. Will additional hikes be required, and how many? We’ll see.”
- 04:00 PM Boston Fed Collins (FOMC non-voter) speaks: Boston Fed President Susan Collins will speak at the 25th Annual Regional and Community Bankers Conference at the Federal Reserve Bank of Boston. Speech text and audience Q&A are expected. On September 22, President Collins said that “I now see an increased likelihood of future scenarios in which inflation remains notably above 2 percent,” adding that “a somewhat more restrictive federal funds rate will help ensure that inflation durably returns to target.”
Wednesday, October 14
- 05:40 AM Fed Vice Chair for Supervision Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will participate in a moderated conversation at the IMF Annual Meetings in Bangkok, Thailand. Moderated Q&A is expected. On October 1, Vice Chair for Supervision Bowman said that "after the Committee's action in September, what we need to have is a better understanding about the underlying trends in the economy and how financial conditions are evolving going forward. So, I don't currently see an urgent need for further action."
- 08:30 AM CPI (MoM), September (GS +0.59%, consensus +0.6%, last +0.4%); Core CPI (MoM), September (GS +0.24%, consensus +0.2%, last +0.3%); CPI (YoY), September (GS +3.70%, consensus +3.6%, last +3.4%); Core CPI (YoY), September (GS +2.46%, consensus +2.5%, last +2.4%): We estimate a 0.24% increase in September core CPI (month-over-month SA), which would raise the year-over-year rate by 0.1pp to 2.5% on a rounded basis. We expect a pickup in autos inflation, reflecting a 0.5% increase in used car prices, a 0.2% increase in new car prices, and a 0.2% increase in the car insurance category. We expect another large increase in airfares (+3%), reflecting the impact of the further increase in oil and refined product prices. We forecast benign readings for the shelter categories—a 0.20% increase in the OER category and a 0.17% increase in the rent category—reflecting the continued slowdown in their underlying trend. We estimate a 0.59% rise in headline CPI—reflecting higher food (+0.2%) and energy (+5.0%) prices—which would raise the year-over-year rate to +3.70% from +3.40%. Our forecast is consistent with a slightly smaller 0.20% monthly increase in the core PCE price index in September.
- 01:30 PM Richmond Fed Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will take part in a fireside chat in Richmond. Moderated Q&A is expected.
- 02:00 PM Fed releases Beige Book, October meeting period: The Fed’s Beige Book is a summary of regional economic anecdotes from the 12 Federal Reserve districts. The Beige Book for the September FOMC meeting period noted that economic activity increased at a slight to moderate pace in ten of the twelve districts, while two districts reported no change. In this month’s Beige Book, we will mainly look for anecdotes related to how consumers and firms are responding to the increase in energy prices from the conflict in the Middle East. We will also look for anecdotes related to the impact of the AI buildout on firms’ activity and costs.
- 10:55 PM Fed Vice Chair for Supervision Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will speak at the Bangkok Economic Festival. Speech text is expected.
Thursday, October 15
- 08:30 AM Retail sales, September (GS +0.3%, consensus +0.3%, last +1.1%); Retail sales ex-auto, September (GS +0.4%, consensus +0.5%, last +1.3%); Retail sales ex-auto & gas, September (GS +0.3%, consensus +0.2%, last +1.1%); Core retail sales, September (GS +0.3%, consensus +0.3%, last +1.2%): We estimate nominal core retail sales increased 0.3% in September (ex-autos, gasoline, and building materials; month-over-month SA) based on the signal from alternative measures of consumer spending. We estimate nominal headline retail sales also increased 0.3%, reflecting higher gasoline prices but lower auto sales.
- 08:30 AM Philadelphia Fed manufacturing index, October (GS 28.0, consensus 30.0, last 37.8)
- 08:30 AM Empire State manufacturing survey, October (consensus 12.6, last 7.6)
- 08:30 AM PPI final demand, September (GS +0.6%, consensus +0.6%, last +0.4%); PPI ex-food and energy, September (GS +0.2%, consensus +0.3%, last +0.2%); PPI ex-food, energy, and trade, September (GS +0.3%, consensus +0.4%, last +0.3%):
- 08:30 AM Initial jobless claims, week ended October 10 (GS 210k, consensus 200k, last 197k): Continuing jobless claims, week ended October 3 (consensus 1,710k, last 1,716k)
- 10:00 AM Business inventories, August (consensus +0.4%, last +0.8%)
- 04:30 PM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will participate in a moderated discussion at the Women's Trading Network Fireside Discussion hosted by Goldman Sachs and Girls Who Code in New York. Moderated Q&A is expected.
- 11:30 PM Fed Chairman Warsh speaks: Fed Chairman Kevin Warsh will participate in a fireside chat with IMF managing director Kristalina Georgieva at the IMF Annual Meetings in Bangkok. Moderated Q&A is expected.
Friday, October 16
- 08:30 AM Import price index, September (consensus +0.8%, last +0.7%)
- 09:15 AM Industrial production, September (GS +0.5%, consensus +0.4%, last flat); Manufacturing production, September (GS +0.4%, consensus +0.3%, last -0.3%); Capacity utilization, September (GS 76.4%, consensus 76.5%, last 76.3%): We estimate industrial production increased by 0.5% in September, largely reflecting strong auto and electricity production. We estimate capacity utilization edged up to 76.4%.
Source: DB, Goldman
Tyler Durden Mon, 10/12/2026 - 12:35
Continue reading...
[ H/T ZeroHedge ]