
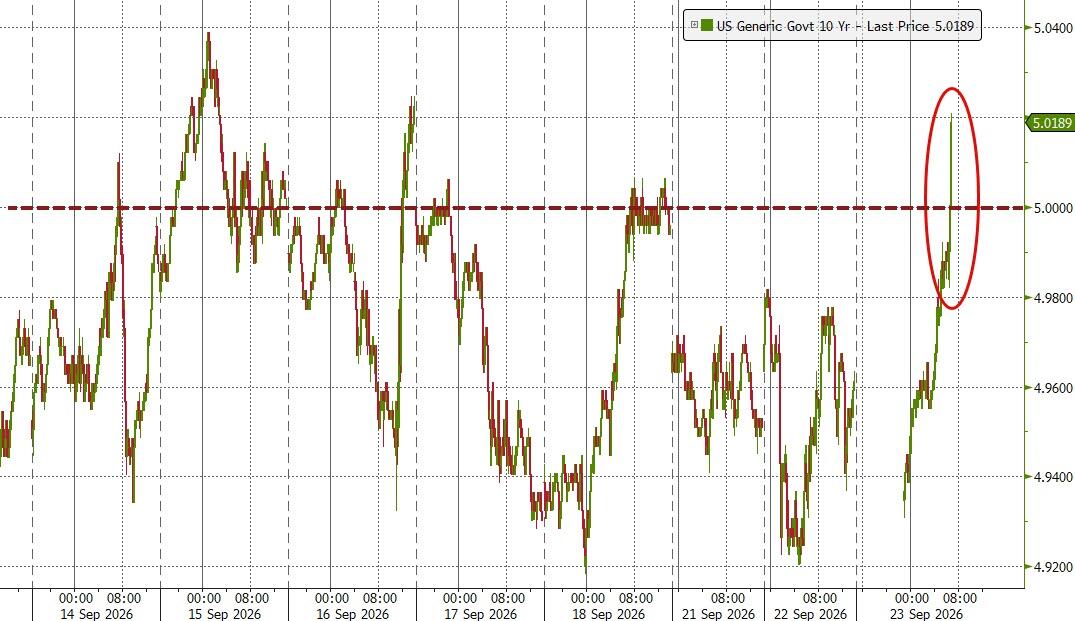
10Y Yield Spikes Above 5.00% After Blowout Beats For US PMIs
With 'hard' economic data still somewhat muted, expectations were for a modest retracement in US PMIs from recently optimistic levels in preliminary September data.
Instead, the 'soft' survey data soared:
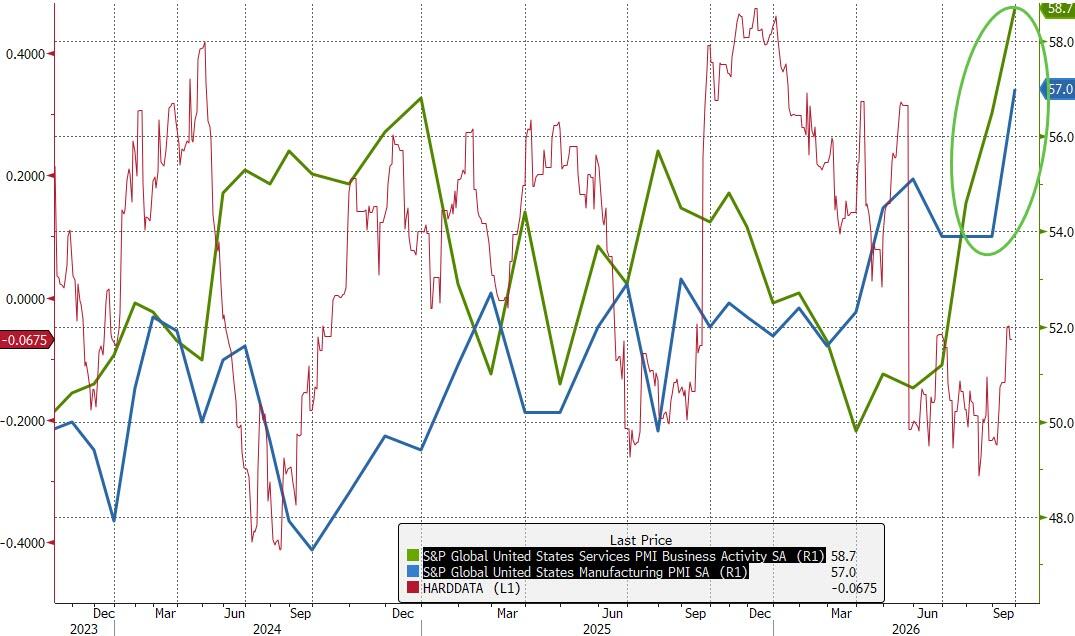
The headline flash S&P Global US PMI Composite Output Index rose from 56.0 in August to 58.4 in September, registering the fastest expansion since July 2021 and an acceleration of growth for a fourth successive month.
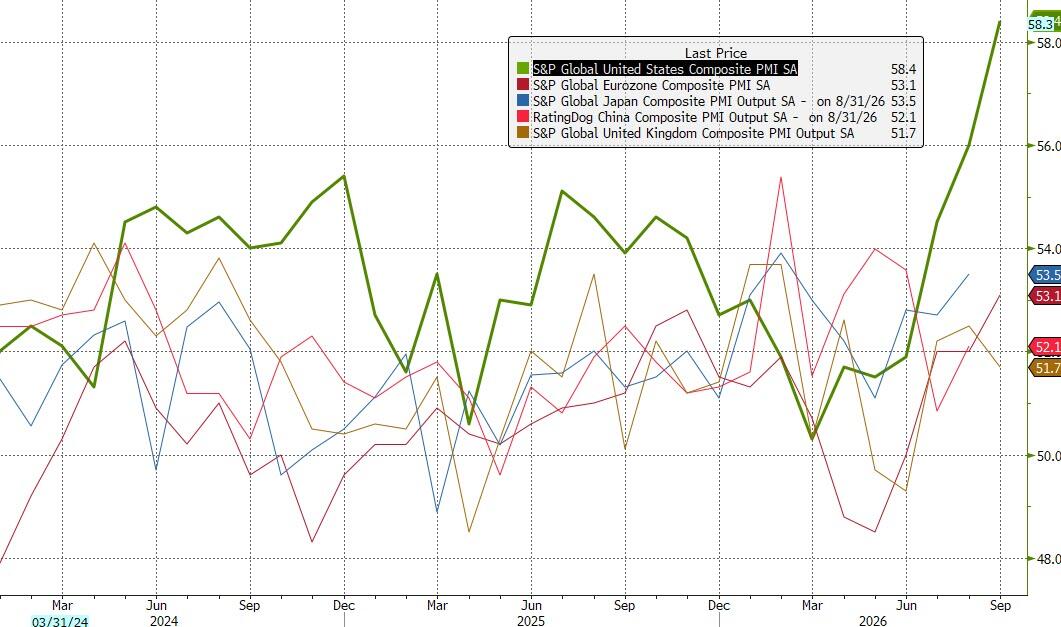
Growth was driven by the service sector, which reported the steepest rise in output for over five years, but a welcome development in September was an accompanying acceleration of manufacturing output growth to the fastest since April 2022. New order inflows also gathered pace in both sectors, with growth reaching the highest since March 2022 in the service sector and the highest since April 2022 in manufacturing. In both cases, demand was buoyed principally by the domestic market, as goods export volumes continued to fall and services exports rose only modestly.
“US business continues to boom, with output growing at the fastest rate for over five years in September," said Chris Williamson, Chief Business Economist at S&P Global Market Intelligence.
Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole...
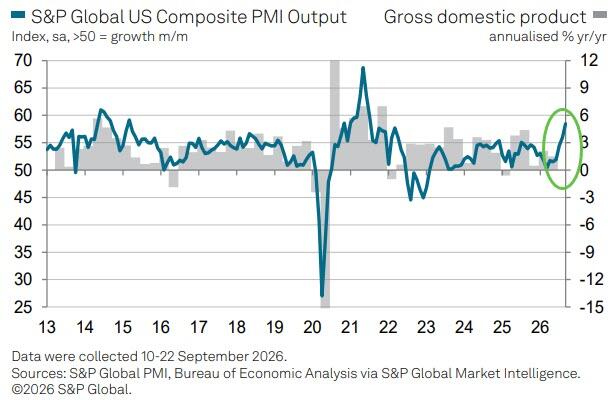
To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015 with Williamson noting that:
However, he adds, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff.
Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
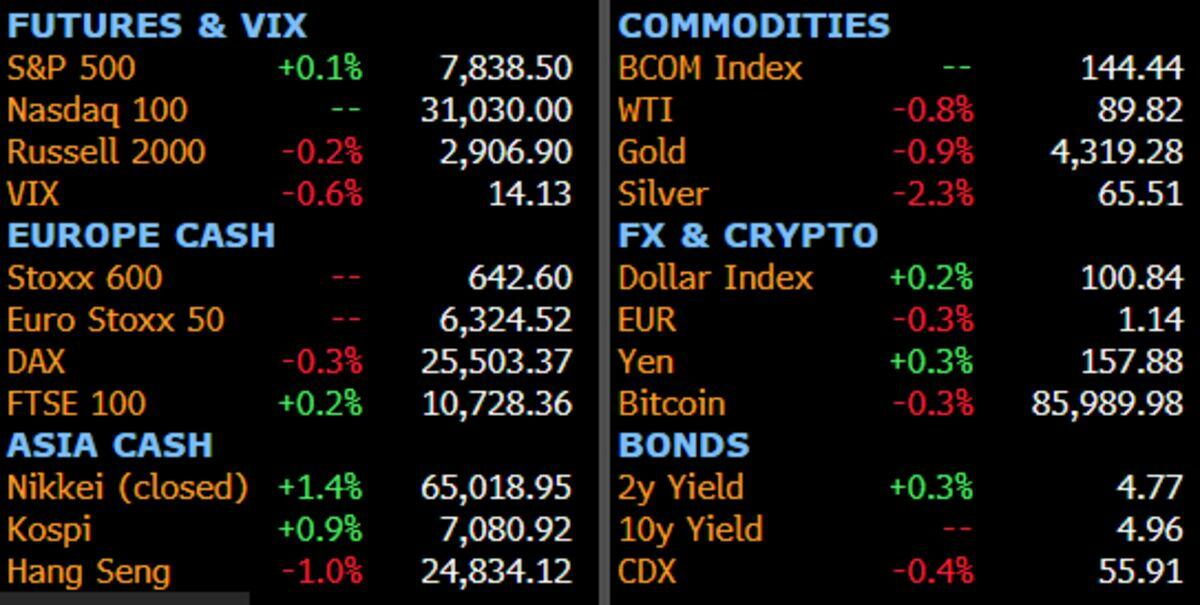
As a result of all this, 10Y yields have spiked back above 5.00%...
...and rate-hike odds picked up modestly for October.
Tyler Durden Wed, 09/23/2026 - 09:55
Continue reading...
[ H/T ZeroHedge ]
With 'hard' economic data still somewhat muted, expectations were for a modest retracement in US PMIs from recently optimistic levels in preliminary September data.
Instead, the 'soft' survey data soared:
Flash US Services PMI Business Activity Index: 58.7 vs 55.8 exp (August: 56.5). 59-month high.
Flash US Manufacturing PMI: 57.0 vs 53.7 exp (August: 53.9). 52-month high.
The headline flash S&P Global US PMI Composite Output Index rose from 56.0 in August to 58.4 in September, registering the fastest expansion since July 2021 and an acceleration of growth for a fourth successive month.
Growth was driven by the service sector, which reported the steepest rise in output for over five years, but a welcome development in September was an accompanying acceleration of manufacturing output growth to the fastest since April 2022. New order inflows also gathered pace in both sectors, with growth reaching the highest since March 2022 in the service sector and the highest since April 2022 in manufacturing. In both cases, demand was buoyed principally by the domestic market, as goods export volumes continued to fall and services exports rose only modestly.
“US business continues to boom, with output growing at the fastest rate for over five years in September," said Chris Williamson, Chief Business Economist at S&P Global Market Intelligence.
Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole...
To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015 with Williamson noting that:
However, he adds, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff.
Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
As a result of all this, 10Y yields have spiked back above 5.00%...
...and rate-hike odds picked up modestly for October.
Tyler Durden Wed, 09/23/2026 - 09:55
Continue reading...
[ H/T ZeroHedge ]