


WSJ Catches Up, Discovers AI's Off-Balance Sheet Liabilities Are $3 Trillion And Growing $1.2 Trillion Per Quarter
More than two months ago, long before most Wall Street analysts had any clue that the bulk of the AI buildout commitments were diligently hidden in various off-balance sheet SPVs and other (perfectly legal) accounting gimmicks, we wrote a lengthy article detailing just that, and explaining why far beyond the $1 trillion (and rapidly rising) in annual plain vanilla capex -- all of which now has to be funded through debt issuance since free cash flow across the hyperscaler universe is negative for the foreseeable future (if not forever) -- which most pundits obsess over daily...

... the real risk was in the "The $1.8 Trillion Off-Balance Sheet Time Bomb At The Heart Of The AI Supercycle."
We followed up on this critical topic after the latest batch of hyperscaler earnings in late July, which revealed that the nearly $2 trillion in spending commitments had exploded in the second quarter, with just GOOGL and META north of $1.5 trillion, which prompted us to conclude that "across all hypers, off BS commitments are now $3+ trillion, double in one quarter."
Many, traditionally those who had no idea what we were talking about or the implications of the above findings, took the conventional route and either mocked or slighted what we had found.
But not everyone: first it was Nvidia which, scrambling to distance itself from the circular financings that were meant to fund precisely these kinds of gargantuan off balance sheet SPVs, unveiled its $500 billion arrangement with a handful of private credit firms (an arrangement that was nothing new, as Nvidia had already done just that particular deal on numerous occasions, and it merely formalized it in the form of an open-ended MOU).
Second and more important, two months after our first warnings, the WSJ finally caught up, and in an article over the weekend titled "Why Big Tech’s AI Spending Is $3 Trillion Higher Than It Seems", it confirmed everything we have been reporting since early June.

Not to put too fine a point on it, but WSJ authors Rudegeair and Santilli echoed everything we said in our original report more than two months ago, to wit:
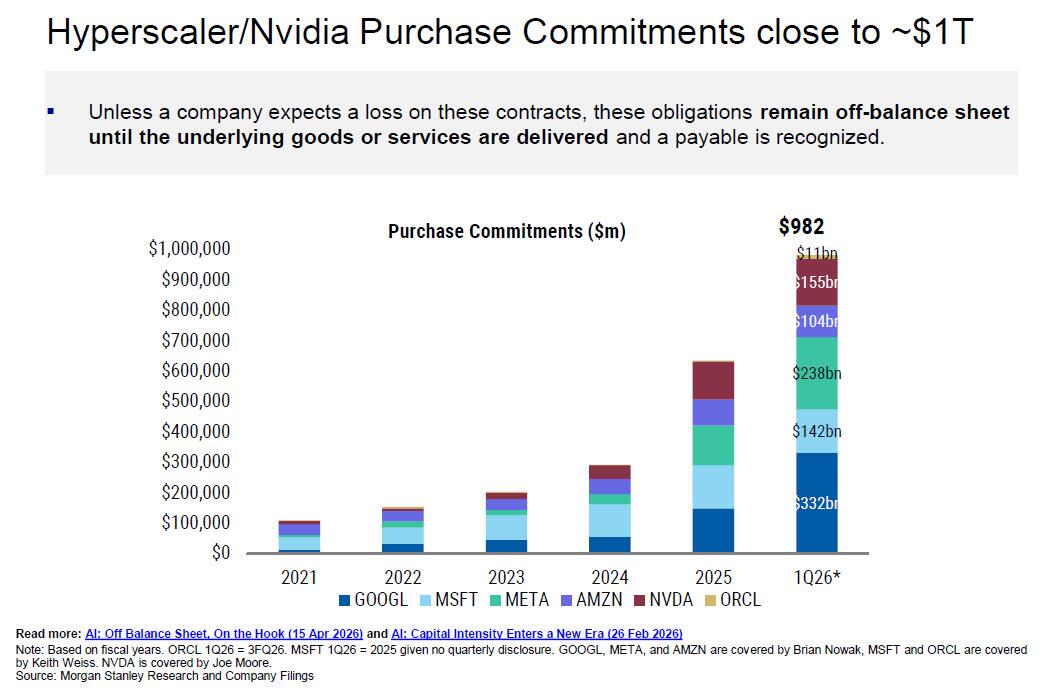
Back in June, we showed this staggering surge in off balance sheet purchase commitment as follows. Needless to say, the latest number is substantially higher.

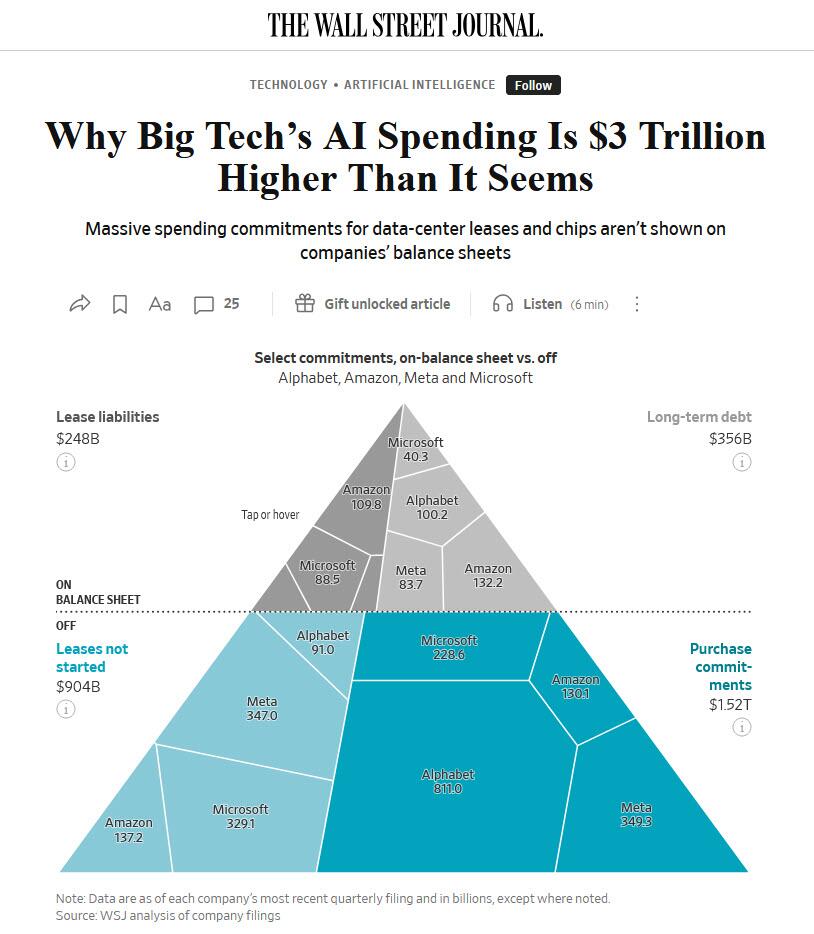
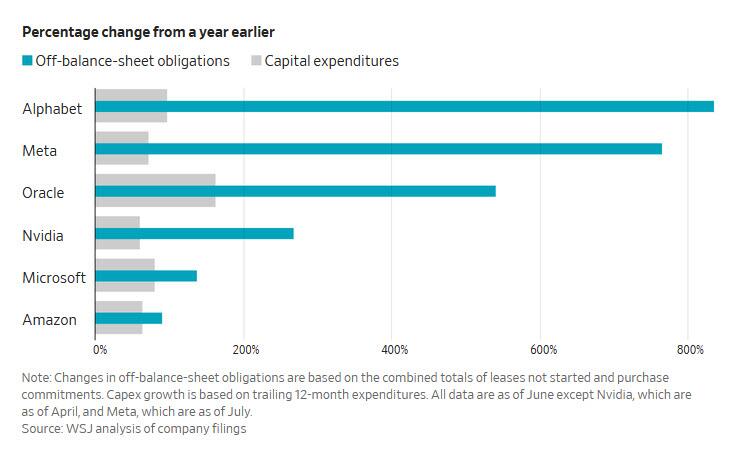
And this is how the WSJ compared side by side the on (capex) vs off balance sheet obligations at the 6 hyperscalers. Needless to say, the management teams at the big AI spenders are doing everything in their power to cover up just how spectacularly massive their true spending plans are.

The WSJ also takes a look at the off B/S SPVs we have been discussing ever since we explained back in January why Meta's Beignet funding model will be imitated by all of its peers throughout 2026 and onward.
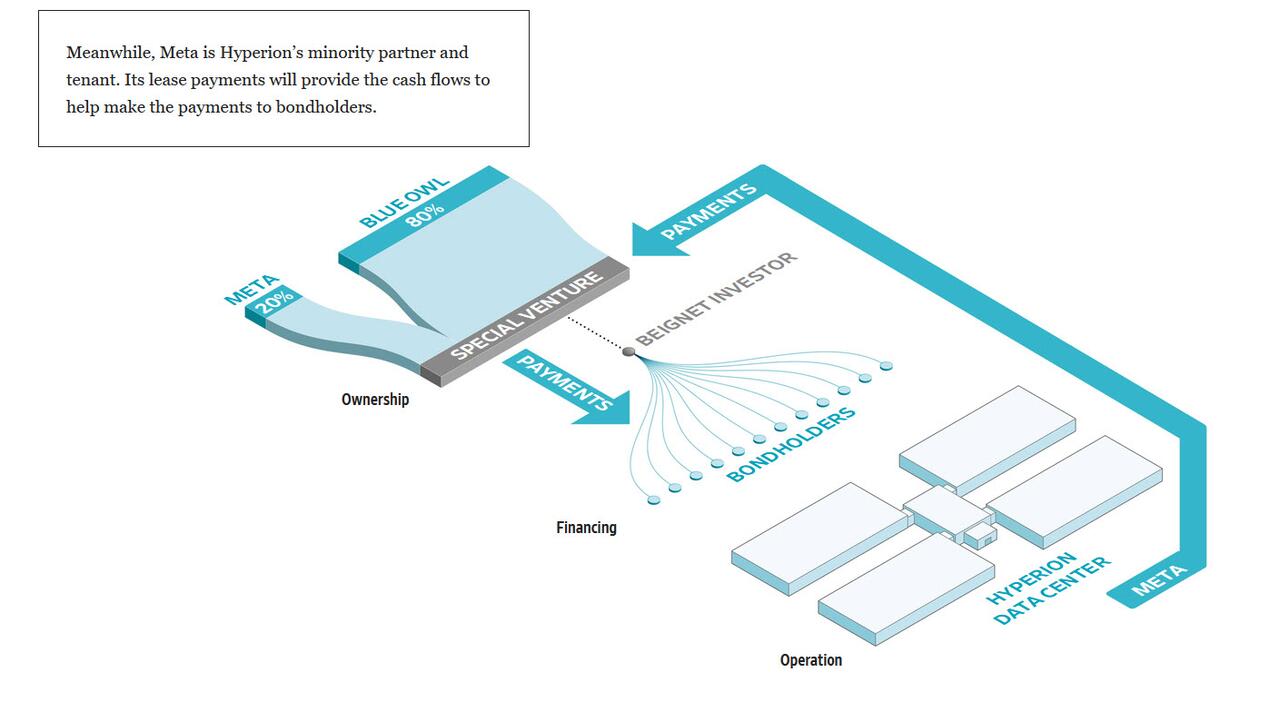
Of course, that's precisely what happened and this is how the WSJ lays out the funding of Meta’s gigantic “Hyperion” data-center project in Louisiana, which is the size of about 1,700 football fields, and which "helps explain how big obligations wind up off tech companies’ balance sheets."
This is the WSJ's version of our graphic from 8 months ago:

Remember what we said about expecting "hundreds of these in 2026?" Apparently it came as a surprise to the WSJ, which writes that "across the companies the Journal analyzed, promises of payments under these uncommenced leases totaled $1.2 trillion in off-balance–sheet obligations, or about four times more than what was disclosed a year earlier. In addition to Meta, the Journal reviewed commitments for Alphabet, Amazon.com, Microsoft, Oracle, Nvidia, Broadcom, SpaceX and Advanced Micro Devices."
Of course, as we explained two months ago, the uncommenced leases are just a part of the off B/S liabilities. There's much more:
... which is why Nvidia has the most to lose if funding deals that enable the AI bubble aren't in place, which is precisely why the company rushed and forced the various private credit firms to deliver the $500 billion deal announced last week. Putting a number to it:
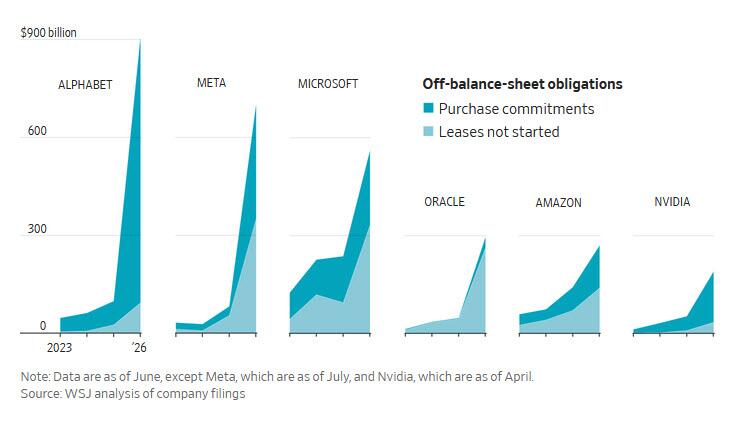
The uncommenced leases and purchase commitments are the bulk of the off balance sheet "ticking time bomb" we discussed in June. Only then it was $1.8 trillion. It has since grown by 50% to $3 trillion.... in two months! And this is how the WSJ redid another one of our June charts:

What happens next depends very much on whether or is an optimist... or not.
For the former, the WSJ says that "there are reasons to believe tech companies will make good on all their obligations. Optimists see the skyrocketing demand for AI tools—which has lifted the stock market and led to shortages of key hardware—as a proof point that demand is going to be strong for years, and the money to pay off all these bills will be rolling in."
As for the others, well the problems are only starting. First, this unprecedented explosion in off balance sheet liabilities in "a worrying sign that some tech companies that once seemed to have fortress balance sheets have needed to tap the capital markets frequently."
The worst case scenarios is that these tech giants companies, which until recently had pristine balance sheets will be paying an expensive tab for infrastructure that they can’t profitably use "if things go wrong." These obligations could also lead increasingly indebted companies to have to borrow even more.
One way such a catastrophic scenario may happen, is if Chinese open-weight models accelerate their market share grab by dramatically undercutting the token prices of frontier models (as they have been doing), and lead to a collapse in hyperscaler profits as compute creation shifts to China and its far cheaper chips, not to mention far more abundant sources of cheap energy... which is precisely what is happening right now, with token prices in historic free fall, crashing more than 50% in just the past few weeks as Chinese open-models unleash a historic race to the bottom.

And since the entire WSJ is effectively re-print of what we said in early June, we will leave readers with our conclusion from then as it is just as accurate today as it was two months ago (and $1.2 trillion less in off balance sheet obligations).
Much more in our full must-read (as the WSJ clearly found) report from June, as well as the "AI Ecosystem: Charting Recent Trends" report available to pro subs.
Tyler Durden Mon, 08/17/2026 - 23:29
Continue reading...
[ H/T ZeroHedge ]
More than two months ago, long before most Wall Street analysts had any clue that the bulk of the AI buildout commitments were diligently hidden in various off-balance sheet SPVs and other (perfectly legal) accounting gimmicks, we wrote a lengthy article detailing just that, and explaining why far beyond the $1 trillion (and rapidly rising) in annual plain vanilla capex -- all of which now has to be funded through debt issuance since free cash flow across the hyperscaler universe is negative for the foreseeable future (if not forever) -- which most pundits obsess over daily...
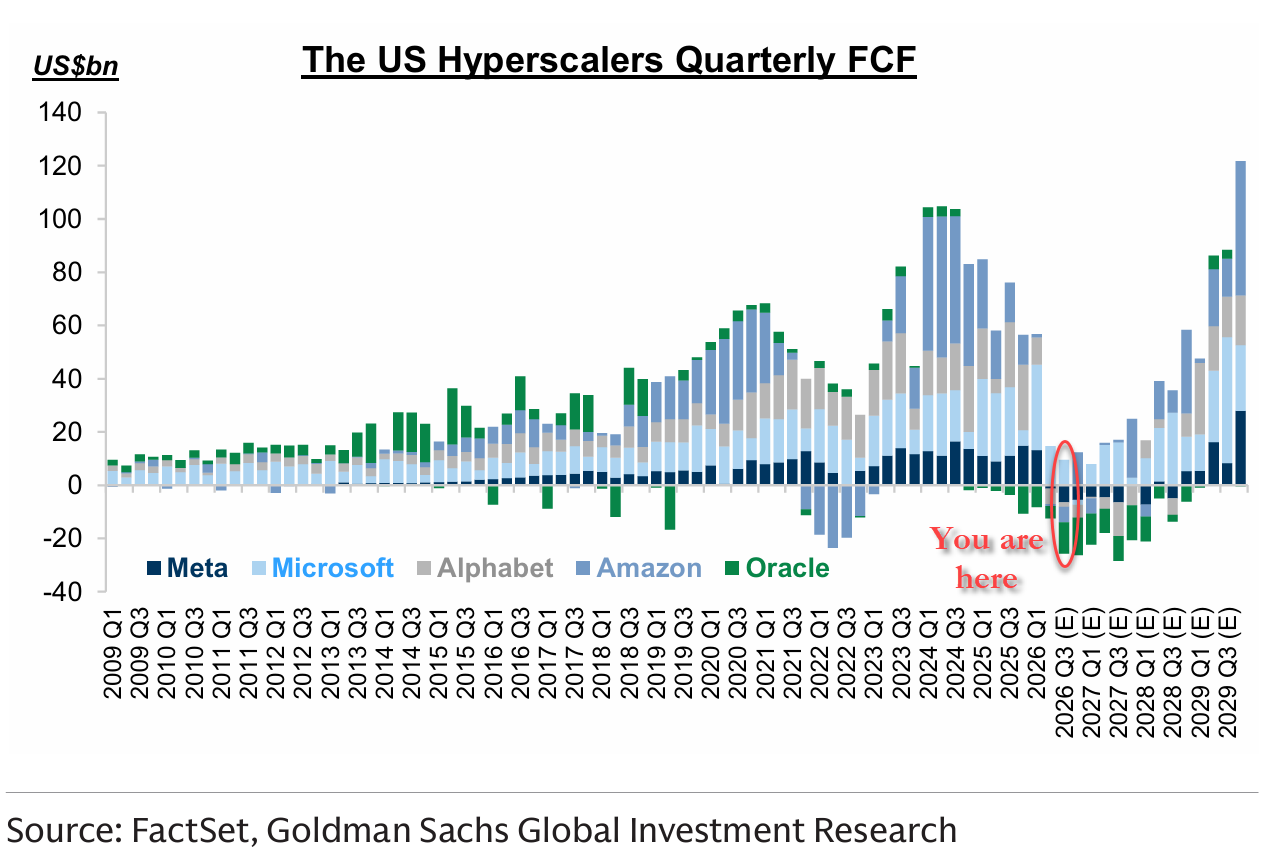
... the real risk was in the "The $1.8 Trillion Off-Balance Sheet Time Bomb At The Heart Of The AI Supercycle."
We followed up on this critical topic after the latest batch of hyperscaler earnings in late July, which revealed that the nearly $2 trillion in spending commitments had exploded in the second quarter, with just GOOGL and META north of $1.5 trillion, which prompted us to conclude that "across all hypers, off BS commitments are now $3+ trillion, double in one quarter."
Many, traditionally those who had no idea what we were talking about or the implications of the above findings, took the conventional route and either mocked or slighted what we had found.
But not everyone: first it was Nvidia which, scrambling to distance itself from the circular financings that were meant to fund precisely these kinds of gargantuan off balance sheet SPVs, unveiled its $500 billion arrangement with a handful of private credit firms (an arrangement that was nothing new, as Nvidia had already done just that particular deal on numerous occasions, and it merely formalized it in the form of an open-ended MOU).
Second and more important, two months after our first warnings, the WSJ finally caught up, and in an article over the weekend titled "Why Big Tech’s AI Spending Is $3 Trillion Higher Than It Seems", it confirmed everything we have been reporting since early June.
Not to put too fine a point on it, but WSJ authors Rudegeair and Santilli echoed everything we said in our original report more than two months ago, to wit:
Back in June, we showed this staggering surge in off balance sheet purchase commitment as follows. Needless to say, the latest number is substantially higher.
And this is how the WSJ compared side by side the on (capex) vs off balance sheet obligations at the 6 hyperscalers. Needless to say, the management teams at the big AI spenders are doing everything in their power to cover up just how spectacularly massive their true spending plans are.
The WSJ also takes a look at the off B/S SPVs we have been discussing ever since we explained back in January why Meta's Beignet funding model will be imitated by all of its peers throughout 2026 and onward.
Of course, that's precisely what happened and this is how the WSJ lays out the funding of Meta’s gigantic “Hyperion” data-center project in Louisiana, which is the size of about 1,700 football fields, and which "helps explain how big obligations wind up off tech companies’ balance sheets."
This is the WSJ's version of our graphic from 8 months ago:
Remember what we said about expecting "hundreds of these in 2026?" Apparently it came as a surprise to the WSJ, which writes that "across the companies the Journal analyzed, promises of payments under these uncommenced leases totaled $1.2 trillion in off-balance–sheet obligations, or about four times more than what was disclosed a year earlier. In addition to Meta, the Journal reviewed commitments for Alphabet, Amazon.com, Microsoft, Oracle, Nvidia, Broadcom, SpaceX and Advanced Micro Devices."
Of course, as we explained two months ago, the uncommenced leases are just a part of the off B/S liabilities. There's much more:
... which is why Nvidia has the most to lose if funding deals that enable the AI bubble aren't in place, which is precisely why the company rushed and forced the various private credit firms to deliver the $500 billion deal announced last week. Putting a number to it:
The uncommenced leases and purchase commitments are the bulk of the off balance sheet "ticking time bomb" we discussed in June. Only then it was $1.8 trillion. It has since grown by 50% to $3 trillion.... in two months! And this is how the WSJ redid another one of our June charts:
What happens next depends very much on whether or is an optimist... or not.
For the former, the WSJ says that "there are reasons to believe tech companies will make good on all their obligations. Optimists see the skyrocketing demand for AI tools—which has lifted the stock market and led to shortages of key hardware—as a proof point that demand is going to be strong for years, and the money to pay off all these bills will be rolling in."
As for the others, well the problems are only starting. First, this unprecedented explosion in off balance sheet liabilities in "a worrying sign that some tech companies that once seemed to have fortress balance sheets have needed to tap the capital markets frequently."
Alphabet and Amazon recently posted results showing negative free cash flow, meaning their capital spending exceeded the cash they brought in from operating their businesses."
And that is before considering the implications of trillions in off-balance–sheet commitments. Whether or not the revenues ever arrive, purchase commitments and signed leases can’t be canceled, for the most part.
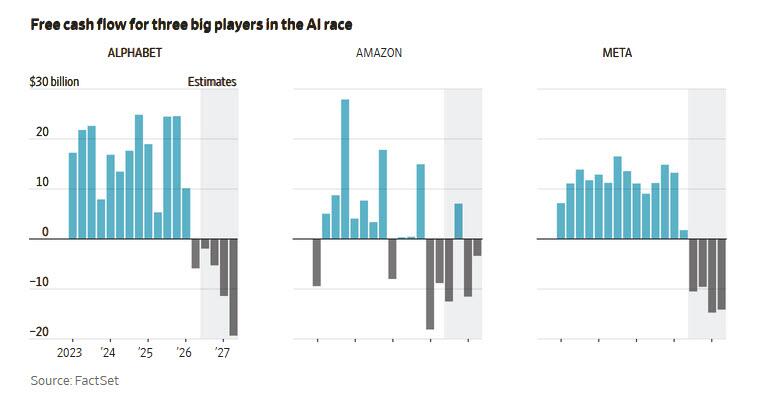
The worst case scenarios is that these tech giants companies, which until recently had pristine balance sheets will be paying an expensive tab for infrastructure that they can’t profitably use "if things go wrong." These obligations could also lead increasingly indebted companies to have to borrow even more.
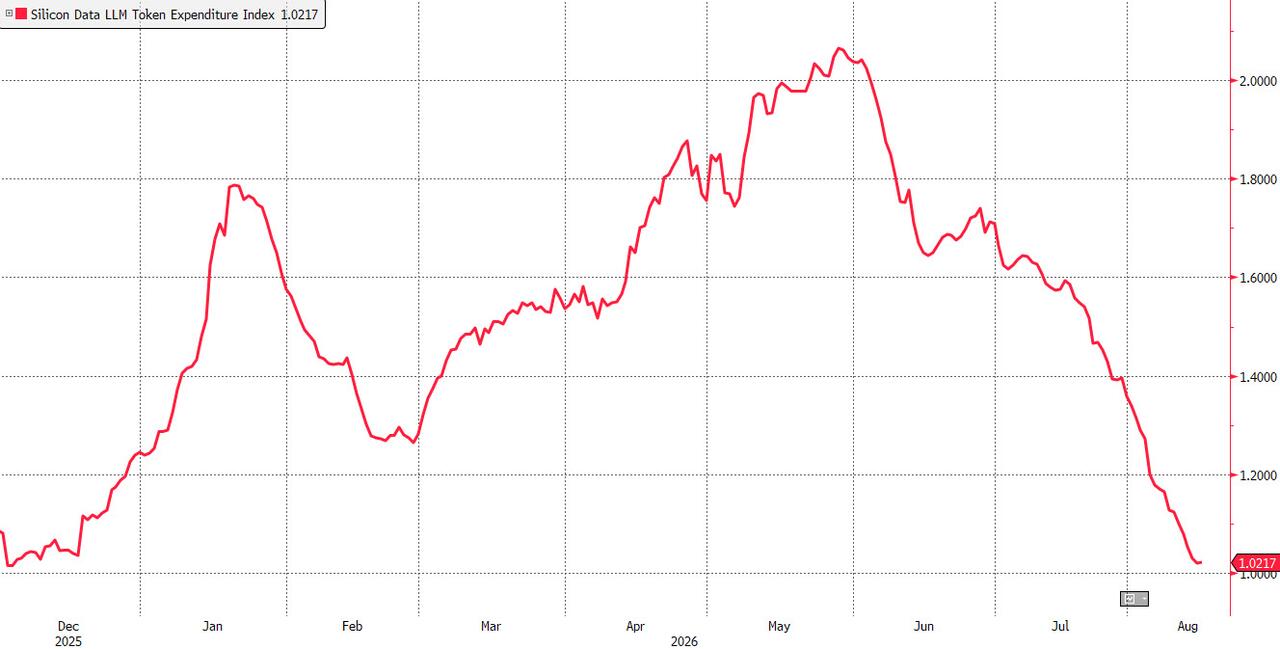
One way such a catastrophic scenario may happen, is if Chinese open-weight models accelerate their market share grab by dramatically undercutting the token prices of frontier models (as they have been doing), and lead to a collapse in hyperscaler profits as compute creation shifts to China and its far cheaper chips, not to mention far more abundant sources of cheap energy... which is precisely what is happening right now, with token prices in historic free fall, crashing more than 50% in just the past few weeks as Chinese open-models unleash a historic race to the bottom.
And since the entire WSJ is effectively re-print of what we said in early June, we will leave readers with our conclusion from then as it is just as accurate today as it was two months ago (and $1.2 trillion less in off balance sheet obligations).
Much more in our full must-read (as the WSJ clearly found) report from June, as well as the "AI Ecosystem: Charting Recent Trends" report available to pro subs.
Tyler Durden Mon, 08/17/2026 - 23:29
Continue reading...
[ H/T ZeroHedge ]