

Rate-Hike Odds, Bond Yields Explode Higher After Hotter-Than-Expected CPI
Expectations were for a hot headline and cool core heading into this morning's most-watched macro signal from CPI with the October FOMC decision on the line. FedSpeak has clearly pushed the market to back away from a hawkish view, today's data may force a change.
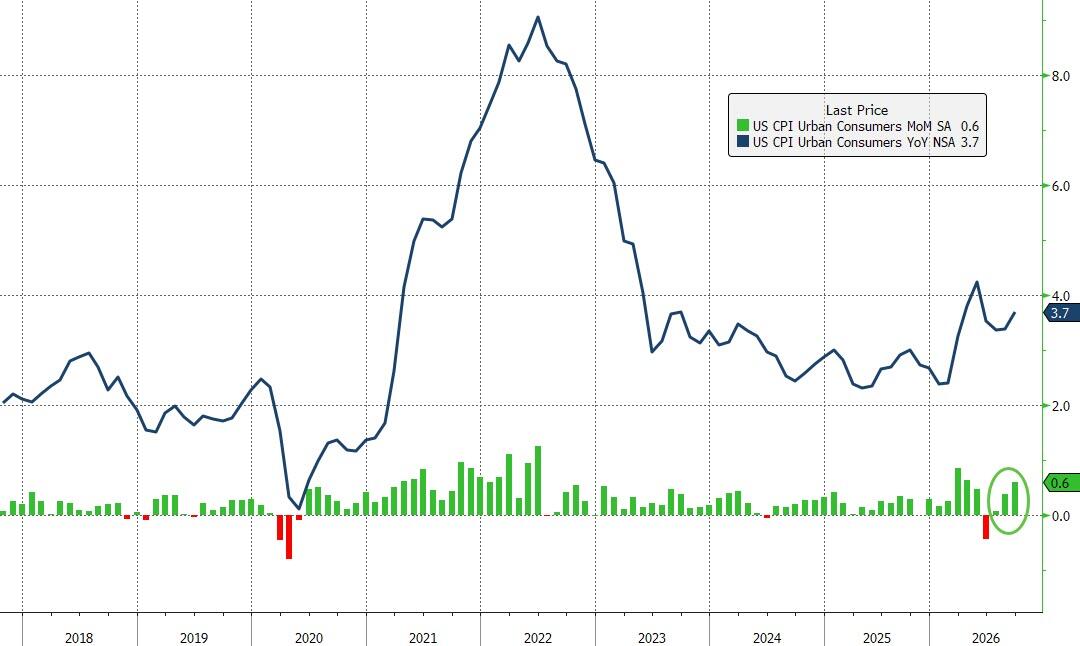
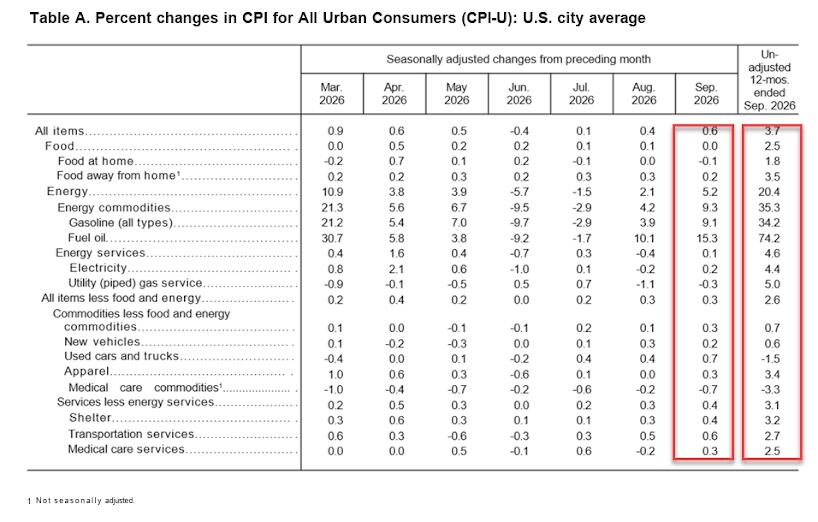
Headline CPI did indeed come hot in September - but as expected - at +0.6% MoM, which pulls it up 3.7% YoY (hotter than the 3.6% YoY exp)...
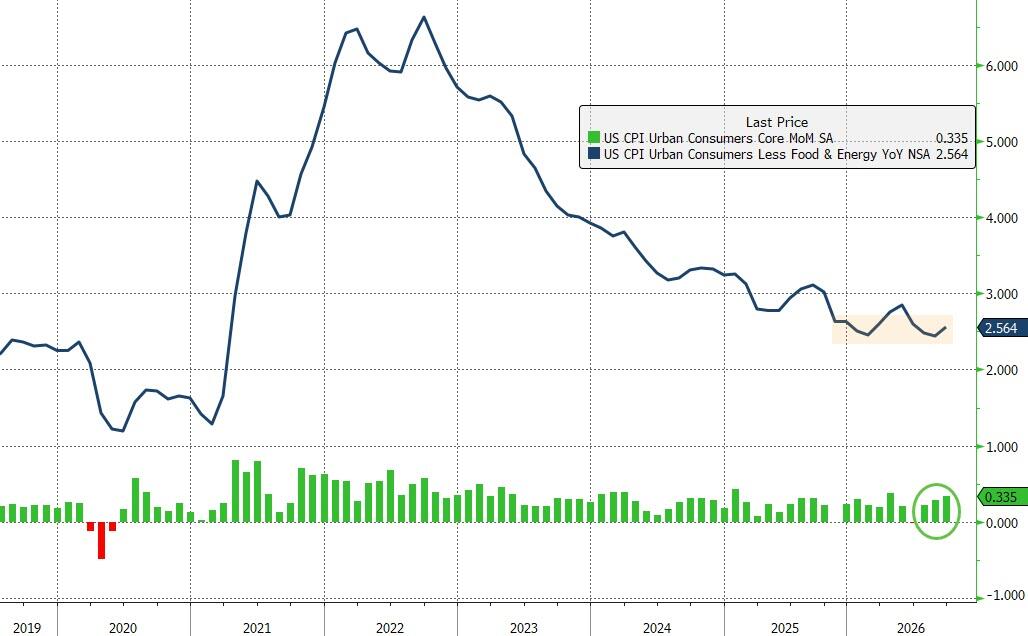
Core CPI also printed hotter than expected, up 0.3% MoM (+0.2% MoM exp). That has pulled Core CPI up 2.6% YoY (above the expected 2.5%)...
Indexes that increased over the month include recreation, used cars and trucks, education, airline fares, medical care, and apparel. Conversely, the index for communication was among the small number of major indexes that decreased in September.
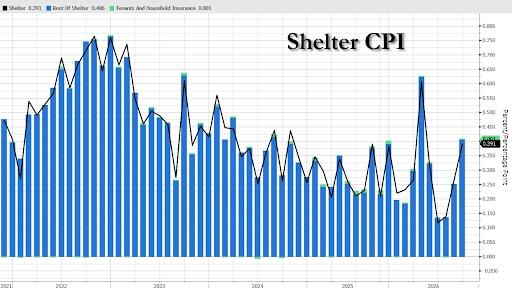
Services was the big driver of Core's jump (with Shelter dominating)...
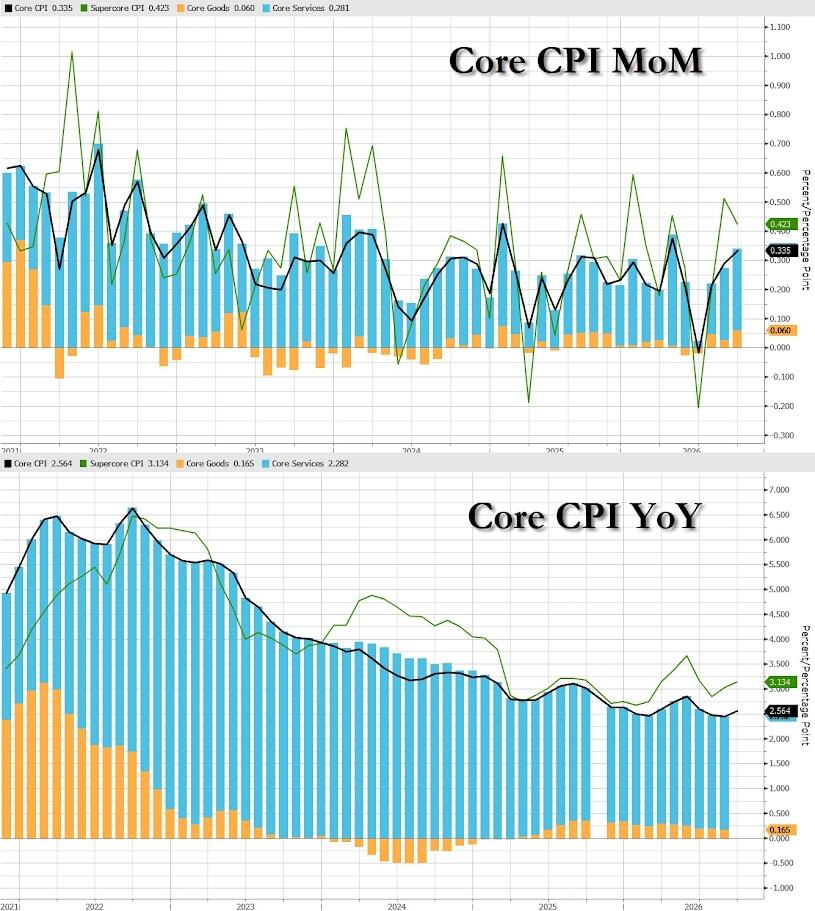
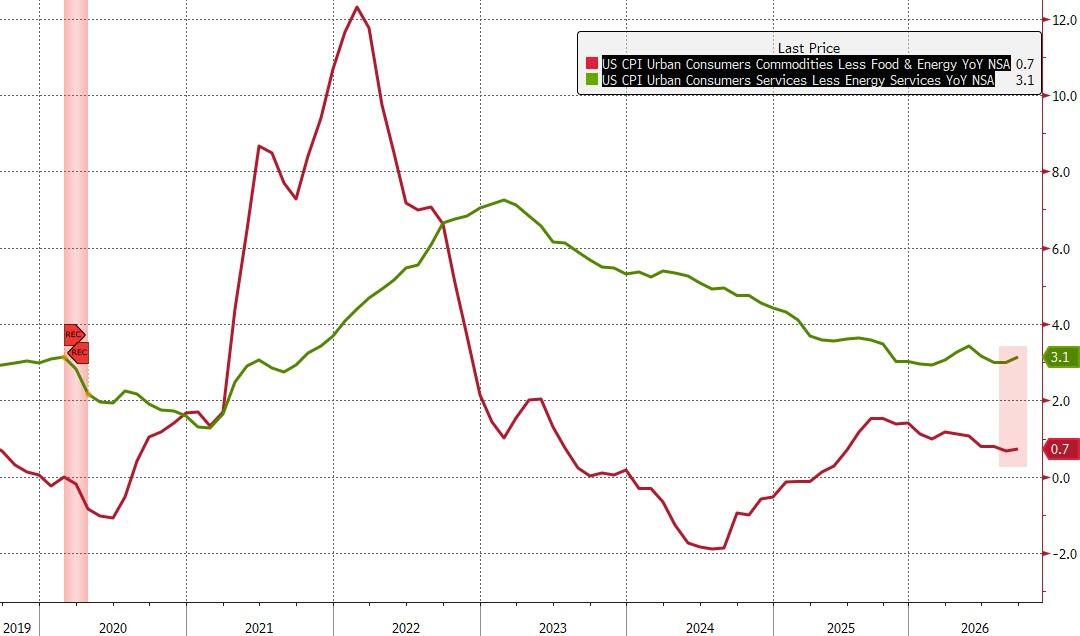
Both Goods and Services price gains accelerated in September...
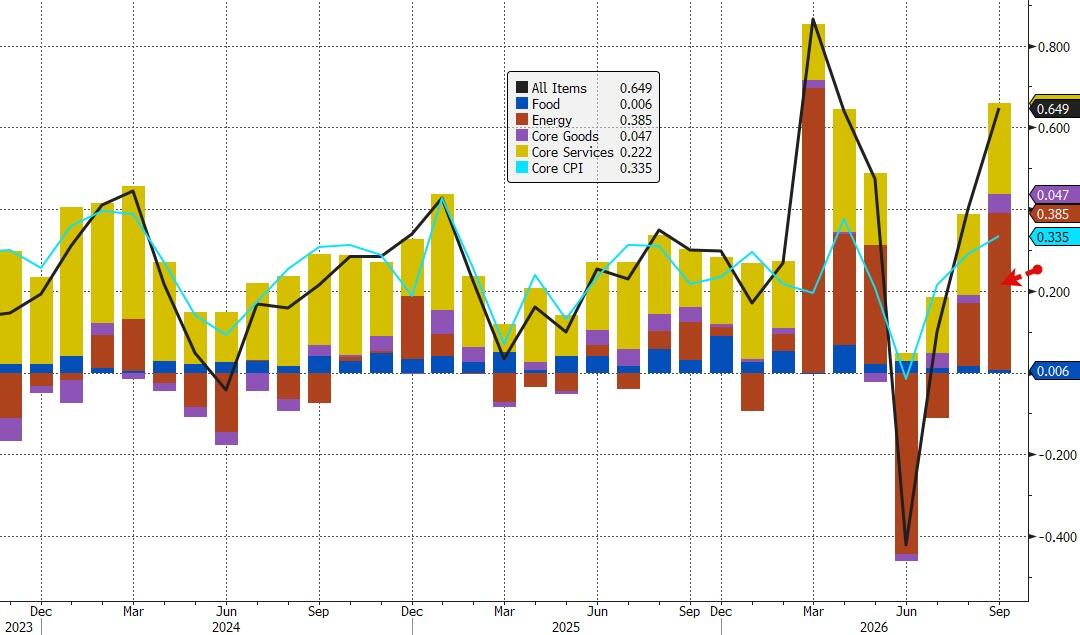
But it was Energy that was the biggest driver of the jump...
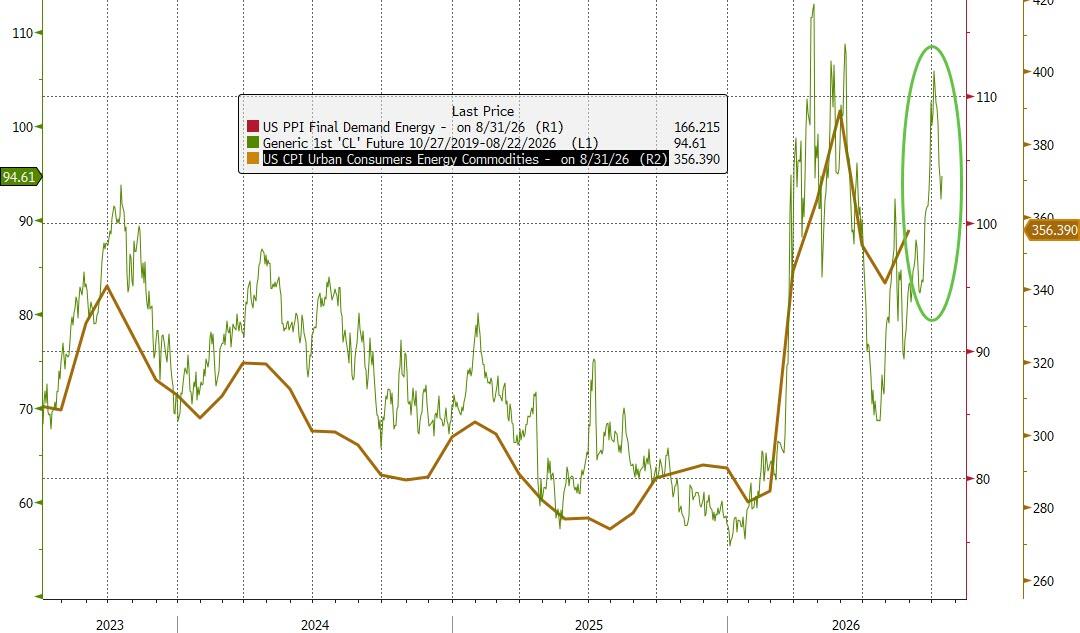
With Fuel Oil (Diesel) prices exploding higher...
And that is only going to get worse!
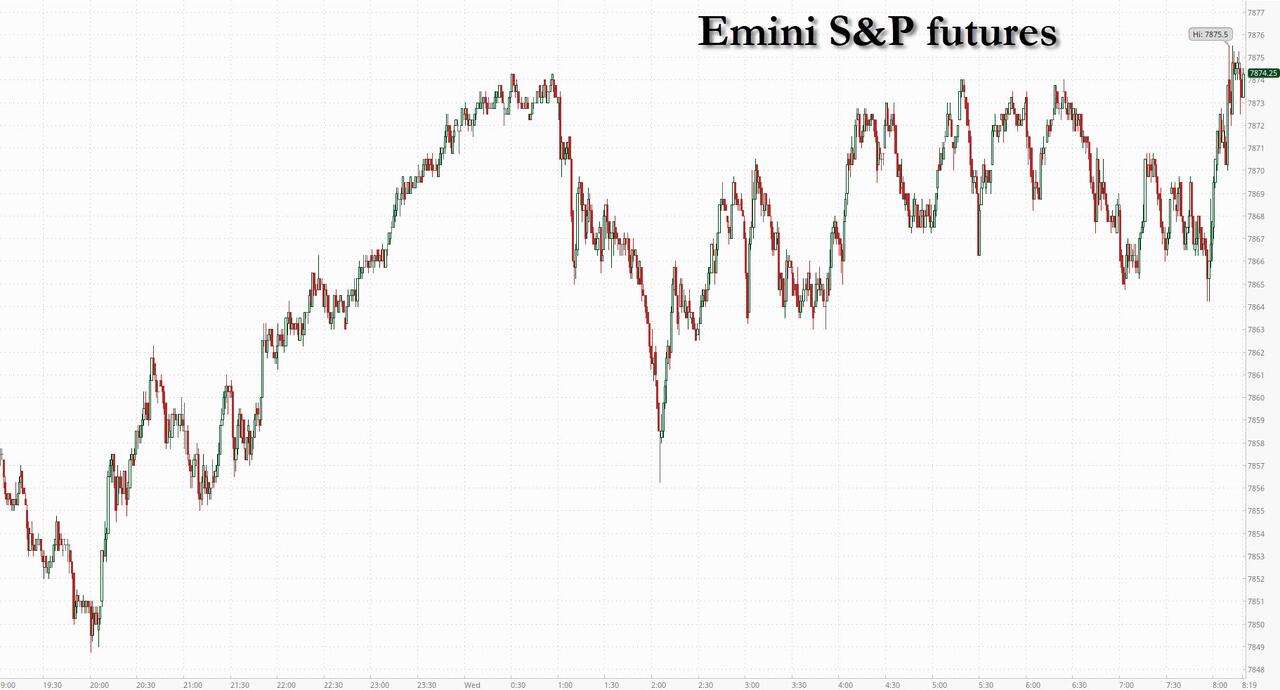
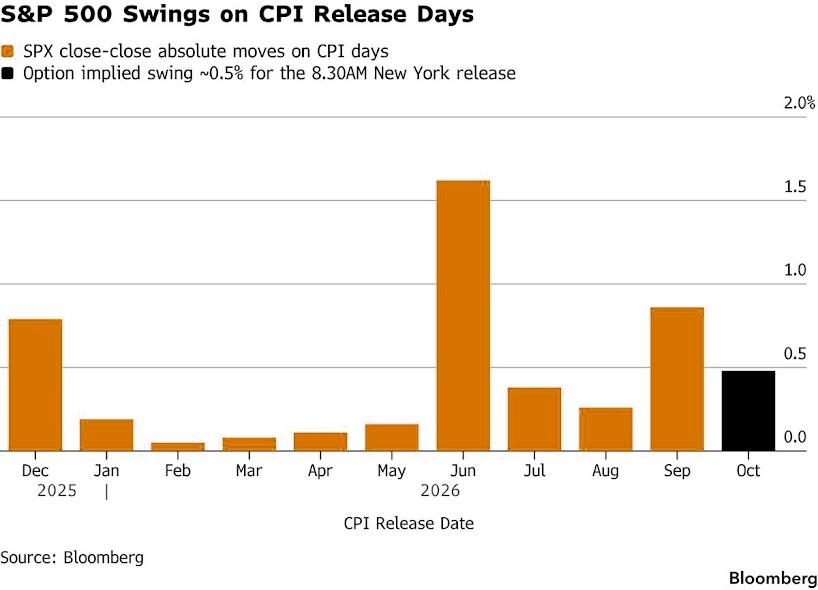
Finally, expectations were for some modest volatility today relative to the last few CPI days...
...but the dismally low volume/liquidity of the last couple of days may exaggerate any move.
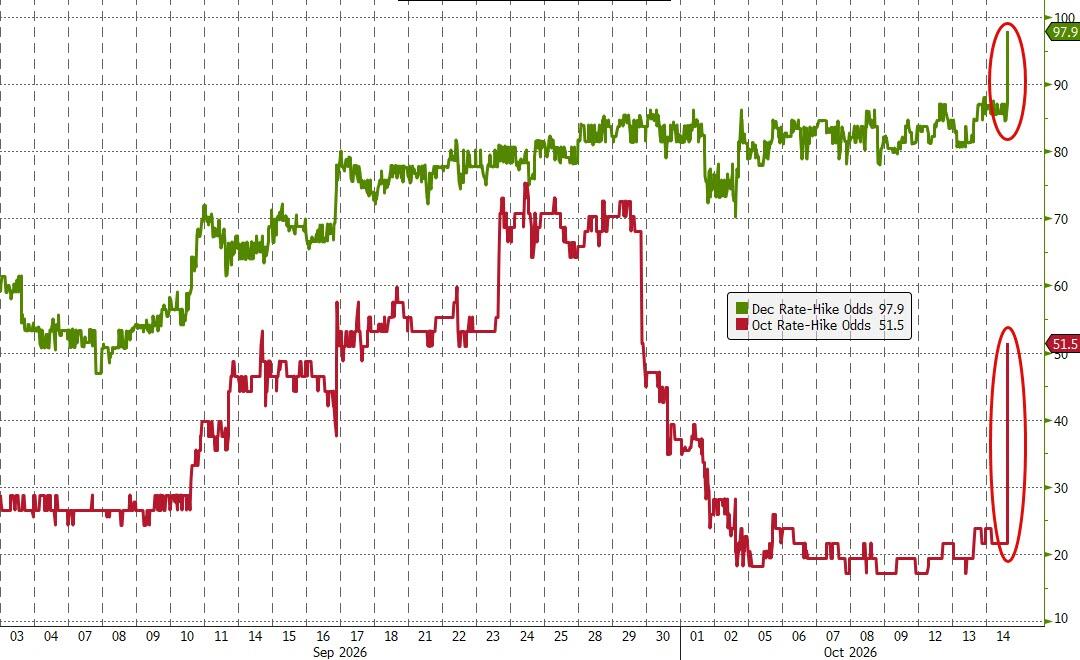
Rate-hike odds have soared to 50% for October...
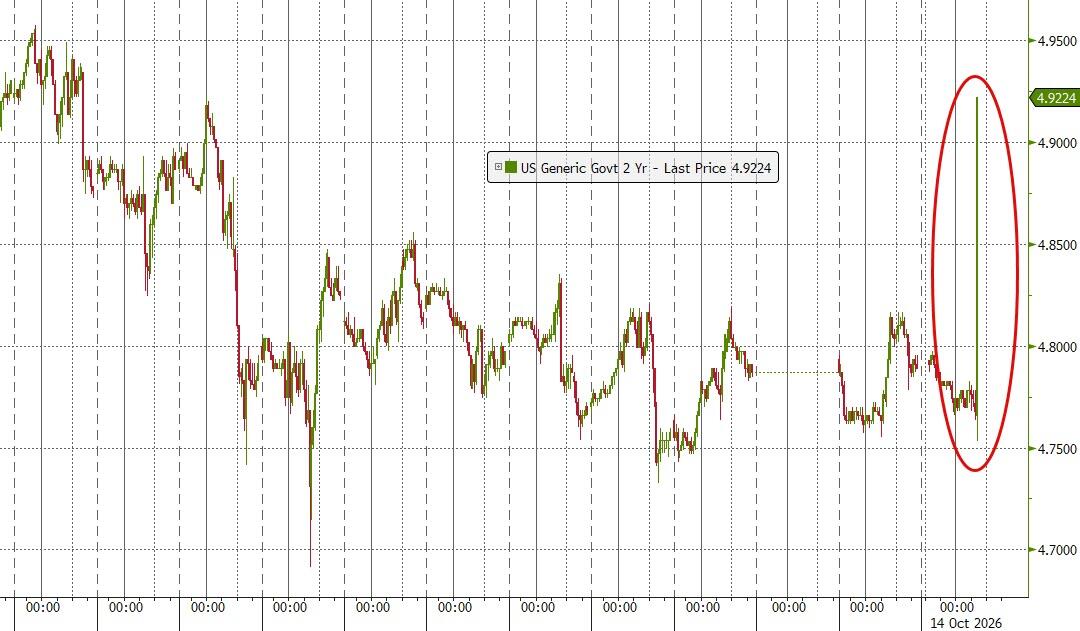
...and 2Y yields are spiking...
Christopher Hodge at Natixis confirms that these numbers put October in play:
The bottom line is that this print signals reasonably broad-based price pressures too (not just energy). Prices for recreation, used cars and trucks, education, airline fares, medical care, and apparel all increased. Some of that may be tariffs and the energy story, but some of it also suggest sticky inflation.
And that is what Warsh and his pals fear most... you can't "look through" that!
Tyler Durden Wed, 10/14/2026 - 08:43
Continue reading...
[ H/T ZeroHedge ]
Expectations were for a hot headline and cool core heading into this morning's most-watched macro signal from CPI with the October FOMC decision on the line. FedSpeak has clearly pushed the market to back away from a hawkish view, today's data may force a change.
Headline CPI did indeed come hot in September - but as expected - at +0.6% MoM, which pulls it up 3.7% YoY (hotter than the 3.6% YoY exp)...
- The index for gasoline rose 9.1% in September, accounting for over half of the monthly all items increase. The energy index increased 5.2% over the month following a 2.1% increase in August. Electricity CPI rose 0.2% over the month. In contrast, the natural gas index decreased 0.3% in September.
- The shelter index rose 0.4% in September after rising 0.3% in August.
- The index for food was unchanged in September, as the index for food away from home increased 0.2% and the index for food at home fell 0.1%. It increased 2.5% over the last year.
- Three of the six major grocery store food group indexes decreased in September, while the other three indexes increased. The meats, poultry, fish, and eggs index decreased 0.5% over the month, as the beef index fell 1.0%. The index for other food at home decreased 0.2 percent in September. The dairy and related products index decreased 0.9% over the month, as the milk index declined 2.0%.
- The energy index increased 20.4% YoY due in large part to the index for gasoline rising 34.2% over the same period. The natural gas index increased 5.0% YoY and the electricity index rose 4.4% YoY.
Core CPI also printed hotter than expected, up 0.3% MoM (+0.2% MoM exp). That has pulled Core CPI up 2.6% YoY (above the expected 2.5%)...
Indexes that increased over the month include recreation, used cars and trucks, education, airline fares, medical care, and apparel. Conversely, the index for communication was among the small number of major indexes that decreased in September.
- Shelter CPI increased 0.4% MoM, after rising 0.3% in August.
- Index for owners’ equivalent rent rose 0.3% in September, and the index for rent increased 0.2%.
- Lodging away from home index rose 2.0% in September after rising 2.4% the previous month.
- Index for recreation increased 0.5% over the month after being unchanged in August.
- Used cars and trucks index rose 0.7% in September, and the education index increased 0.6%.
- New vehicles index, the personal care index, and the motor vehicle insurance index also increased over the month.
- Index for airline fares increased 1.2% in September, and the index for apparel rose 0.3%.
- The medical care index increased 0.1% in September after falling 0.2% in August. The index for hospital services rose 0.7% over the month.
- Prescription drugs index declined 1.2% in September.
- Index for physicians’ services was unchanged over the month.
- Communication CPI declined 0.2% in September after rising 2.3% in August.
- Index for household furnishings and operations was unchanged over the month.
Services was the big driver of Core's jump (with Shelter dominating)...
Both Goods and Services price gains accelerated in September...
But it was Energy that was the biggest driver of the jump...
With Fuel Oil (Diesel) prices exploding higher...
And that is only going to get worse!
Finally, expectations were for some modest volatility today relative to the last few CPI days...
...but the dismally low volume/liquidity of the last couple of days may exaggerate any move.
Rate-hike odds have soared to 50% for October...
...and 2Y yields are spiking...
Christopher Hodge at Natixis confirms that these numbers put October in play:
The bottom line is that this print signals reasonably broad-based price pressures too (not just energy). Prices for recreation, used cars and trucks, education, airline fares, medical care, and apparel all increased. Some of that may be tariffs and the energy story, but some of it also suggest sticky inflation.
And that is what Warsh and his pals fear most... you can't "look through" that!
Tyler Durden Wed, 10/14/2026 - 08:43
Continue reading...
[ H/T ZeroHedge ]