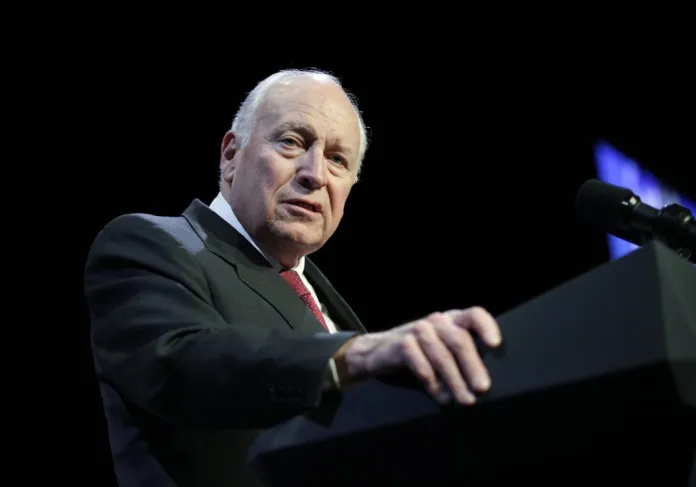
“Deficits don’t matter.” So said then-Vice President Dick Cheney during a high-level budget meeting in late 2002, after Republicans performed surprisingly well during that fall’s midterm elections. Voters, shocked by the Sept. 11, 2001, terrorist attacks, helped the Republican Party gain seats in both houses of Congress and win back the Senate.
According to conventional wisdom, the Republicans had won the election and earned the right to enact their spending program. Even though the federal government had run four years of budget surpluses, voters preferred new national security spending rather than fiscal responsibility.
Cheney may have been right from a political perspective, as little has changed since. Subsequent administrations of both political parties have paid lip service to fiscal responsibility while continuing massive deficit spending. This midterm election is no different. Political figures are still finding ways to spend other people’s money — from promising $5,000 checks to every citizen if Republicans win this November, to a campaign pledge for a new “Medicare for All” entitlement that could add $3 trillion a year to the federal budget, to the House’s $95 billion budget resolution passed without offsetting spending cuts.
With this generous (if economically misguided) election year spending in mind, it may seem like the good times will last forever. But to adapt a line attributed to Russian revolutionary Leon Trotsky: You may not be interested in the national debt. But the national debt is interested in you.
In August, the U.S. national debt reached $40 trillion — approximately $286,000 per taxpayer. The debt is now 124% of gross domestic product, up from 58% in 2002. It costs more than $1 trillion annually (19% of total federal spending in fiscal 2026) just to maintain interest payments on the debt — more than the U.S. spends on defense.
The exploding debt is already making people’s lives harder. When the government borrows to service the debt, it puts upward pressure on inflation, making everything cost more. Today, inflation remains stubbornly high at 3.4% — above the Federal Reserve’s goal of 2%, which we haven’t met since 2021.
When the Fed raises interest rates to fight inflation, as it did in mid-September and could do again this year, it makes consumer debt more expensive across the board. This month, the average home mortgage rate hit 7%, having doubled since 2022. Higher interest rates make it harder for people to borrow, whether to buy a car or a new house, start a business, or invest in their family’s education, or simply pay their bills, making life less affordable in the process.
But the average household isn’t alone. The government itself is straining under the weight of debt. When borrowing costs consume so much of the federal budget, it crowds out discretionary spending priorities such as national defense, border security, and transportation. With about 60% of the budget earmarked for mandatory programs such as Social Security and Medicare, the debt reduces the government’s flexibility to spend on important priorities in the future.
Other nations’ fiscal struggles highlight the concerning path we’re treading. The United Kingdom’s weak growth and rising interest costs have caused years of political turmoil, economic malaise, and hard choices between taxing, borrowing, and spending. During the Great Recession, Greece ran huge deficits and accumulated unsustainable public debt. Investors lost confidence, leading to a massive increase in borrowing costs. This ultimately led to significant bailouts and externally imposed budget measures. In Argentina, governments financed public spending and debt through decades of borrowing. Once its economy slowed, Argentina had few options. It defaulted on roughly $100 billion in debt, causing years of economic pain, inflation, and a severe decline in living standards.
Fortunately, the United States isn’t on an irreversible path yet. But to adapt a quote from Ernest Hemingway: Nations go bankrupt in two ways. Slowly, then suddenly. That’s why economic literacy — the understanding of the core economic principles that govern our lives, and how to apply them to economic decision-making — is critical to changing our nation’s fiscal course, before it’s too late.
CONGRESS PUSHED A $1.8 TRILLION SPENDING FIGHT PAST ELECTION DAY. THAT’S THE POINT
My organization, the Foundation for Teaching Economics, works to address gaps in our nation’s economic literacy by hosting programs for high school teachers, equipping them with the tools to teach economics to their students. Each year, more than 1,500 high school teachers participate in FTE programs, educating an estimated 175,000 students annually. Our popular program, Making Sense of the Federal Budget, Debt & Deficit, helps educators teach their students about the incentives, costs, and benefits that influence spending choices of American policymakers.
As we approach another midterm election, millions of 18-year-olds will cast their first votes as adults. We must continue to support programs that promote economic literacy among America’s next generation of leaders. Despite what political wisdom may say, deficits do matter, and fiscal responsibility is always on the ballot.
Ted Tucker is the executive director at the Foundation for Teaching Economics, a nonprofit educational organization that promotes experiential learning and the economic way of thinking. FTE was established in 1975 and operates as a program of The Fund for American Studies.
Continue reading...
[ H/T Washington Examiner ]