
US Jobs Soar By 165K Blowing Away Estimates; Unemployment Rate Drops Putting Dec Rate Hike Back In Play
In our preview of the October jobs report, we said that the labor data has rarely looked this solid going into a monthly payrolls report: claims near 57-year lows, the lowest October layoffs since 2023, JOLTS openings up 333K and ADP above expectations. If anything, the risk is to the upside of the 63K consensus, and the unemployment rate could well tick down.
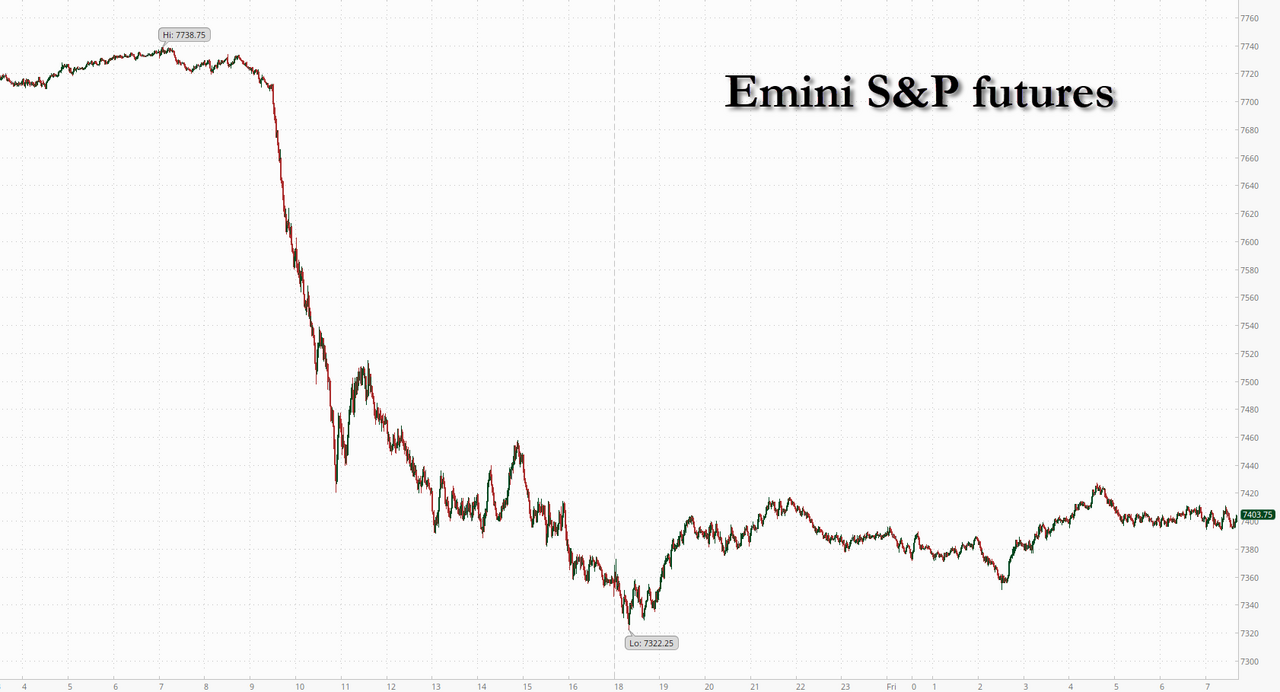
Which, as we noted, was the problem as "a strong print gives Warsh, Hammack and Barkin all the cover they need to hike in December, right as the Nasdaq is coming off its worst day since March 2020. Goldman's rates desk thinks a single print can't take the hikes out." We said that we agree with this take, and added that the more likely outcome is a decent number that puts December back in play and adds a rates problem to what has so far been an AI problem. Given where positioning is, CTAs already selling and long-only "frozen (again)," that's not a recipe for a relief rally.
Well, moments ago, the BLS reported the October jobs and it came extremely red hot, enough to indeed put a December rate hike back on the docket, AI collapse notwithstanding. Here are the numbers:
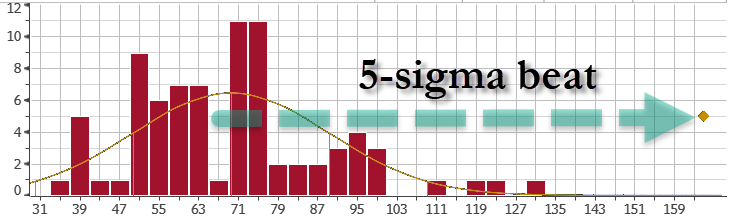
October monthly payrolls rose by 165K, up more than double the 70K expected bounce, and the third highest print of 2026.
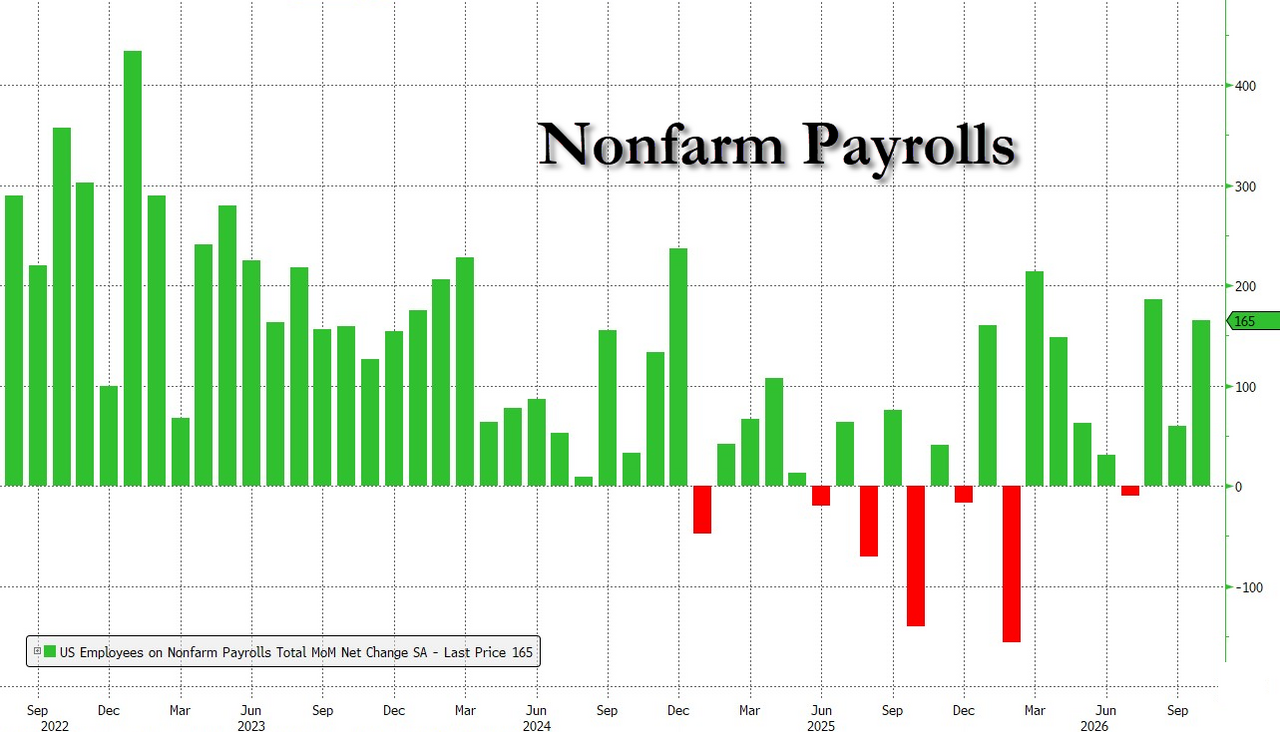
The number was so hot it not only printed above the highest Wall Street estimate...
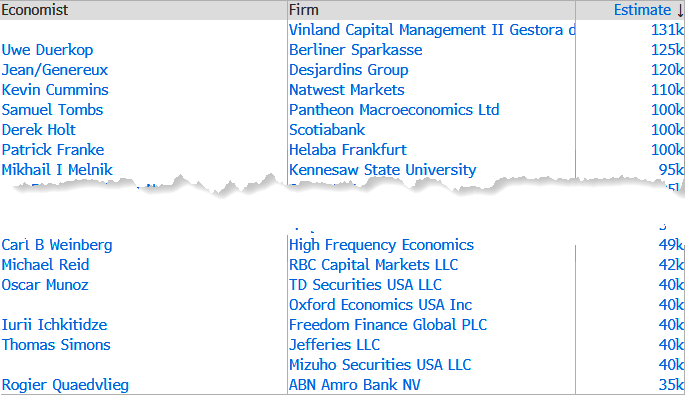
... it was a 5-sigma beat to the median consensus number.
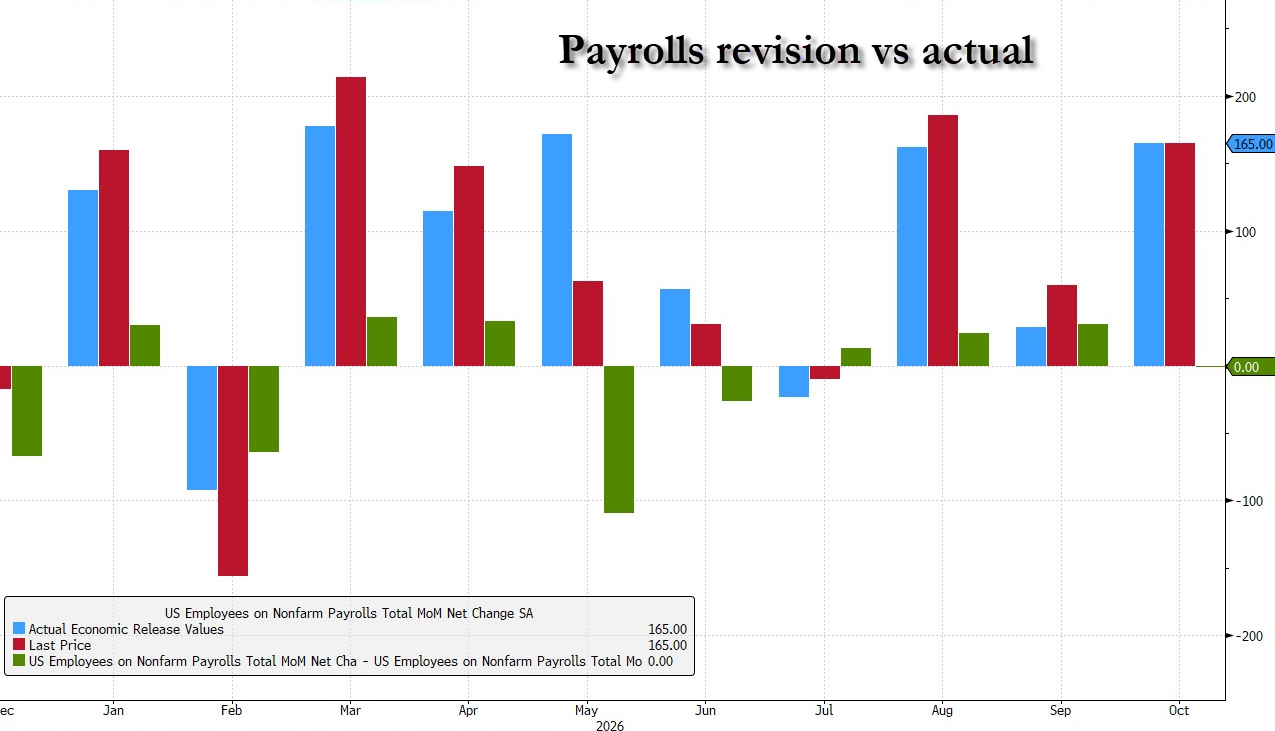
Not only was October red hot, prior month revision were all higher: the August was revised up by 53,000, from +133,000 to +186,000, and September was revised up by 31,000, from +29,000 to +60,000. With these revisions, employment in August and September combined is 84,000 higher than previously
reported.
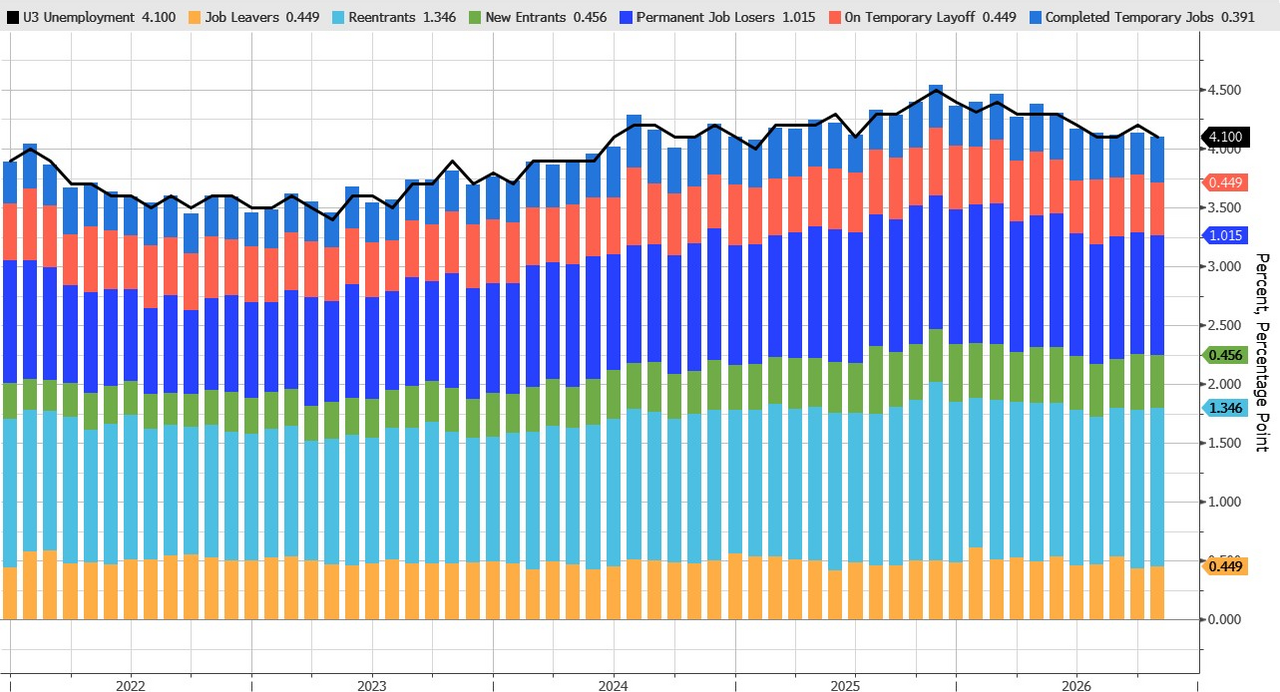
It wasn't just the job number that came in red hot: the unemployment rate unexpectedly dipped back to 4.1% from 4.2%, and against expectations of an unchanged print.
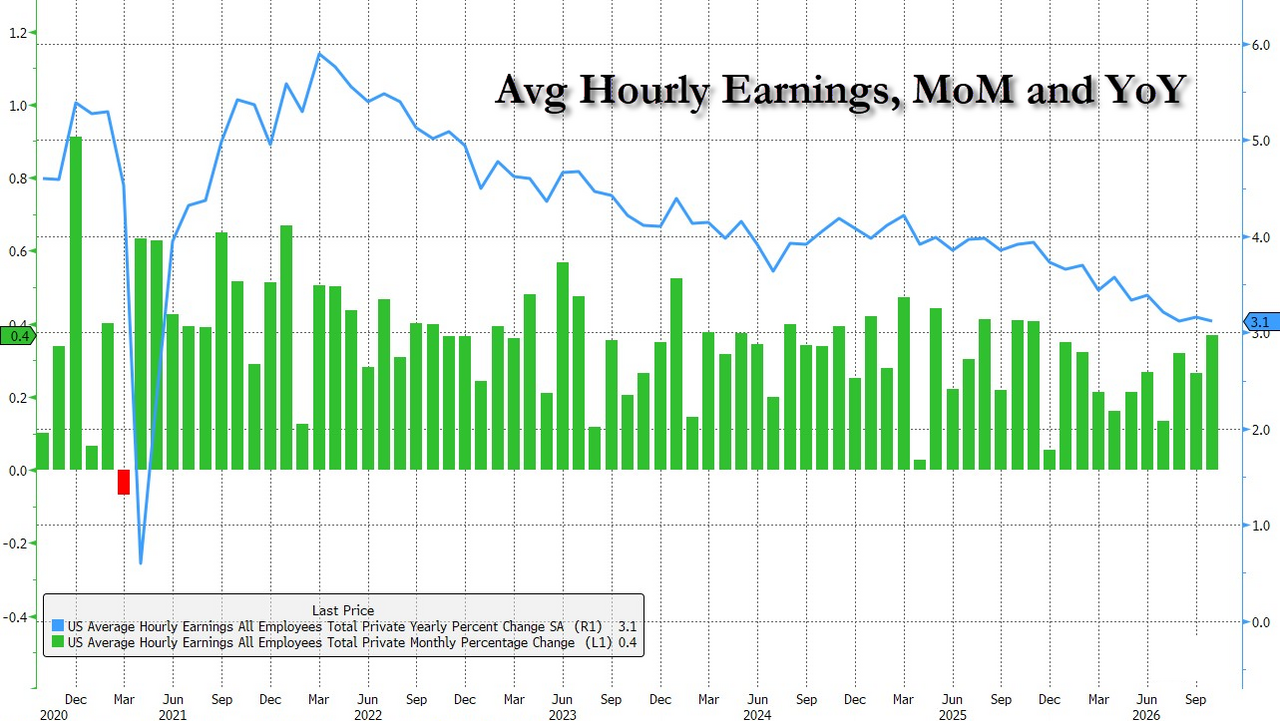
And completing the trifecta of hot data was the average hourly earnings which beat expectations both MoM and YoY, with the former printing 0.4%, above the 0.3% expected, and the highest since Nov 2025, while the annual change in earnings disappointed expectations of the first sub-3% print since covid, and instead rose from the pre-revision 3.0% to 3.1% (then again Sept was revised higher to 3.2%).
Developing.
Tyler Durden Fri, 11/06/2026 - 08:11
Continue reading...
[ H/T ZeroHedge ]
In our preview of the October jobs report, we said that the labor data has rarely looked this solid going into a monthly payrolls report: claims near 57-year lows, the lowest October layoffs since 2023, JOLTS openings up 333K and ADP above expectations. If anything, the risk is to the upside of the 63K consensus, and the unemployment rate could well tick down.
Which, as we noted, was the problem as "a strong print gives Warsh, Hammack and Barkin all the cover they need to hike in December, right as the Nasdaq is coming off its worst day since March 2020. Goldman's rates desk thinks a single print can't take the hikes out." We said that we agree with this take, and added that the more likely outcome is a decent number that puts December back in play and adds a rates problem to what has so far been an AI problem. Given where positioning is, CTAs already selling and long-only "frozen (again)," that's not a recipe for a relief rally.
Well, moments ago, the BLS reported the October jobs and it came extremely red hot, enough to indeed put a December rate hike back on the docket, AI collapse notwithstanding. Here are the numbers:
October monthly payrolls rose by 165K, up more than double the 70K expected bounce, and the third highest print of 2026.
The number was so hot it not only printed above the highest Wall Street estimate...
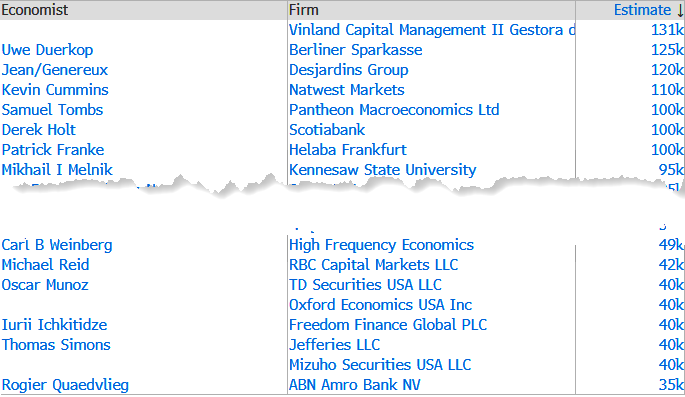
... it was a 5-sigma beat to the median consensus number.
Not only was October red hot, prior month revision were all higher: the August was revised up by 53,000, from +133,000 to +186,000, and September was revised up by 31,000, from +29,000 to +60,000. With these revisions, employment in August and September combined is 84,000 higher than previously
reported.
It wasn't just the job number that came in red hot: the unemployment rate unexpectedly dipped back to 4.1% from 4.2%, and against expectations of an unchanged print.
And completing the trifecta of hot data was the average hourly earnings which beat expectations both MoM and YoY, with the former printing 0.4%, above the 0.3% expected, and the highest since Nov 2025, while the annual change in earnings disappointed expectations of the first sub-3% print since covid, and instead rose from the pre-revision 3.0% to 3.1% (then again Sept was revised higher to 3.2%).
Developing.
Tyler Durden Fri, 11/06/2026 - 08:11
Continue reading...
[ H/T ZeroHedge ]