Guest Post by Peter Reagan
Family gatherings around the holidays have a funny way of reminding us just how difficult compromise can be.
My five-year-old nephew would happily eat McDonald’s chicken nuggets (because he wants the toy). My mother prefers the traditional sit-down meal – roast chicken, mashed potatoes, the whole thing. Then there’s that one cousin who insists on sushi or extra-spicy General Tso’s chicken…
Personally, I’m happy to let somebody else negotiate the menu.
I just want everyone fed and happy at the end of the evening.
Politics can feel like that.
Most Americans disagree about how Washington should get from here to there. But underneath all the partisan arguments, most of us want remarkably similar things from the economy:
The 2026 midterm elections changed who gets to decide how the federal government pursues those goals.
What they did not change is the arithmetic those lawmakers inherited.
And that may matter much more to our financial futures than which party won election night…
The election produced a major shift in Congress.
Democrats won majorities in both the House and Senate, according to the Associated Press, replacing the GOP majority in the House and the divided Senate.
That changes the balance of power considerably.
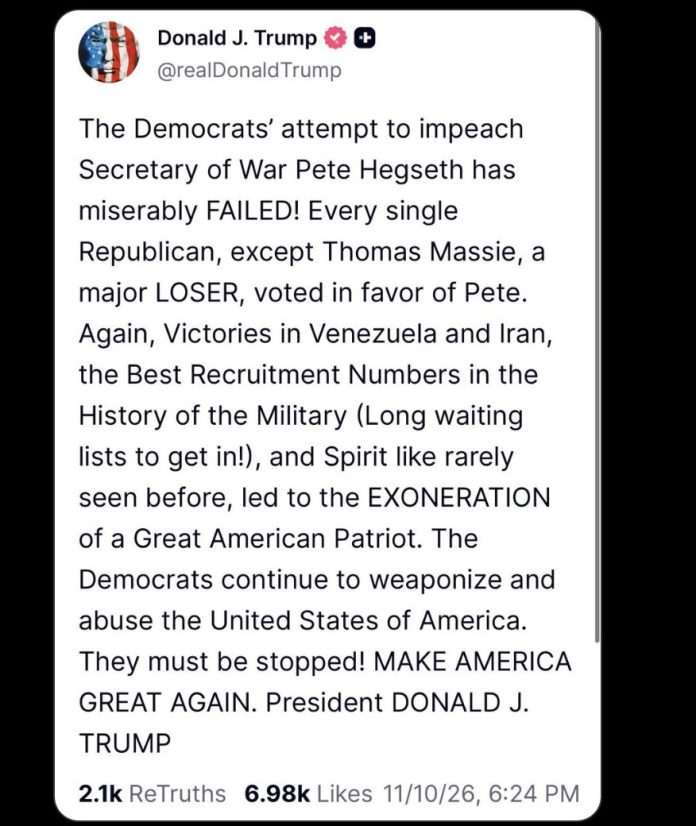
President Trump still controls the executive branch, as he recently reminded us:
Starting in January, though, Democrats will control Congress.
Usually, that means neither side can simply do whatever it wants.
Remember, Congress controls legislation and federal appropriations. The President can sign legislation into law or veto it. Congress can override a presidential veto, but only with the constitutionally required supermajorities. That doesn’t happen very often; historically, presidential vetos are only overridden about 0.5% of the time.
Trump has already signaled he intends to use his veto power when he disagrees with the new Congress…
So the next two years may involve a great deal of negotiation.
Or gridlock.
Probably some of both.
Now, there are circumstances in which gridlock can be perfectly healthy. If Congress can’t agree on some big new program, well, I believe doing nothing is preferable to doing the wrong thing. That’s probably what the authors of the Constitution intended, as well.
There’s just one problem with that theory: Doing nothing does not mean the federal government’s financial problems stand still.
The debt meter keeps running.
The Congressional Budget Office’s latest baseline puts the federal deficit for fiscal year 2026 at about $1.9 trillion.
That’s not the national debt.
That’s the projected shortfall for one year – the annual gap between what Washington’s income and spending.
The CBO does not expect that gap to disappear. Quite the opposite.
The agency projects the annual deficit will continue to rise, reaching $3.1 trillion by 2036.
Here’s another way of looking at those numbers…
CBO says deficits averaged about 3.8% of the economy over the last 50 years. This year’s deficit is projected at 5.8%.
By 2036? 6.7%.
That is not primarily a prediction about Democrats and their plans. It’s not a prediction about Republicans, either. The CBO is known as the least partisan office in the federal government.
No, this is a projection of what happens under laws already on the books.
That distinction matters. The CBO is describing the status quo.
Because elections can change the government overnight.
Elections don’t automatically change decades of spending commitments.
CBO projects federal debt held by the public at roughly 101% of GDP in 2026. We’re discussing “federal debt held by the public” because that’s the portion of the debt that actually represents borrowing from financial markets. For measures of fiscal pressure, interest costs, debt sustainability and capital markets, it’s the part of the national debt that matters most.
CBO explains this explicitly in their Budget and Economic Outlook: 2026 to 2036. Debt held by the public is the measure used because it “best captures federal borrowing that affects interest rates and private investment.” See, when the Treasury Department borrows from outside investors, they’re competing with corporate and private borrowers for available funds. That’s how federal debt can contribute to higher borrowing costs and “crowd out” private investment by making it too expensive.
The last time America carried this much debt, it took nearly three decades to bring the burden back down. And we didn’t simply “grow our way out of it.”
After World War II, Washington cut spending sharply enough to run primary budget surpluses (in other words, they paid down the debt). The economy boomed while inflation exploded (17.6% in 1946-1947!), reducing the value of the existing debt. And for years, the Federal Reserve deliberately held government borrowing costs below the rate of inflation. Inflation alone eliminated about 1/4th of the total debt.
The plan worked. Federal debt fell from 106% of GDP in 1946 to 23% by 1974. That’s right, it took nearly three decades to work off the debt burden… And the public paid a price: The dollar lost about 60% of its purchasing power along the way.
So history tells us America can escape a debt burden this large. It also tells us the cure wasn’t painless.
That’s bad enough. But here’s the uncomfortable part of that historical comparison: Today, we have the debt without the surpluses.
CBO doesn’t expect Washington to begin paying down the debt. That’s reasonable, since the last year of federal surplus was 2001, 25 years ago. CBO expects debt to climb from 101% of GDP today to 120% within ten years.
Now, ten years is a long time.
Economic growth could come in stronger than expected.
Congress may reduce spending.
Lawmakers might increase federal revenue.
Maybe the Federal Reserve holds interest rates below inflation.
Or some combination of all four could conceivably improve the picture.
Frankly, though, the opposite looks a lot more likely to me. And the longer those deficits continue, the more government pays just to refinance old debt.
CBO expects net interest costs to rise from 3.3% of GDP this year to 4.6% in 2036.
That may sound abstract. Trust me, it isn’t.
Every dollar devoted to servicing government debt is a dollar Washington cannot spend somewhere else. Not without either cutting another priority, collecting more revenue or borrowing even more.
That is the debt trap. Steve Bannon’s End of the Dollar Empire explores this concept in volume three, The Debt Trap.
And gridlock alone does not get us out of it.
Then there’s Social Security.
The 2026 Social Security Trustees Report projects that the Old-Age and Survivors Insurance Trust Fund – the fund that pays retirement and survivor benefits – will be able to pay full scheduled benefits until the fourth quarter of 2032.
That is one quarter earlier than last year’s projection.
Now, “trust fund depletion” does not mean Social Security suddenly disappears.
That distinction is important.
Social Security would continue collecting payroll taxes.
But according to the Trustees, continuing income at that point would be sufficient to pay only about 78% of scheduled OASI benefits unless Congress makes changes beforehand.
That is a much more accurate description than saying Social Security will “run out of money.”
But I doubt the distinction would be especially comforting to a retiree who had planned a household budget around receiving 100% of the benefits promised under current law.
Congress has options.
Lawmakers could adjust taxes.
They could adjust benefits.
They could change eligibility rules.
They could combine approaches.
What they cannot do is vote away the mathematics.
Some combination of money coming in and money going out eventually has to balance.
There’s going to be an enormous temptation over the next few months to interpret every economic development through a partisan lens.
If something improves, one side will take credit.
If something gets worse, the other side will get blamed.
That’s politics.
But I think it can distract us from something much more important.
The federal government entered this election spending substantially more money than it collects.
It exited the election doing exactly the same thing.
Social Security entered the election on a path toward reserve depletion.
It exited the election on exactly the same path.
Federal debt was rising on Monday.
It was still rising on Wednesday.
Election night changed the people holding some of the levers.
It did not change the machine.
And that means neither political party deserves to be treated as a substitute for your own financial planning.
Financial markets reacted quickly to the election.
Reuters reported that spot gold surged about 3.4% on November 4, its strongest daily gain since August, as the U.S. dollar weakened following the Democratic sweep of Congress.
By the end of the week, gold remained more than 5% higher despite giving back some of those gains.
It would be easy to draw a very simple conclusion from that:
Democrats won, therefore gold went up.
I don’t think that’s a very useful way to understand what happened.
Financial markets were digesting several things at once – a weaker dollar, changing expectations for government policy, inflation, monetary policy and the likelihood of political gridlock.
Gold frequently responds to uncertainty in the financial system.
But a one-day move tells us very little about what happens over the next five or ten years.
The more important lesson, in my view, is why investors turn toward assets like physical gold during periods when the economic or political path becomes harder to predict.
Maybe Democrats and Trump find areas of compromise.
I hope they do.
Maybe economic growth accelerates enough to make today’s fiscal projections look overly pessimistic.
I hope that happens, too.
Maybe Congress reaches a bipartisan agreement that puts Social Security on stronger footing and slows the growth of government debt.
Wonderful.
But if you’re planning for retirement – or simply trying to preserve what you’ve spent decades accumulating – I don’t think your financial future should require all of those things to go right.
That’s what diversification is for.
You don’t diversify because you know exactly what happens next.
You diversify because you don’t.
Physical precious metals are one way some Americans choose to diversify a portion of their savings outside the dollar-based financial system.
Gold isn’t guaranteed to rise.
Its price fluctuates.
And owning precious metals cannot eliminate financial risk.
But physical gold does not depend on Congress passing a budget on time.
It doesn’t depend on one political party defeating another.
And it doesn’t require a ten-year CBO forecast to come true.
That’s a useful quality when Washington itself seems increasingly difficult to forecast.
The midterms changed Washington.
They changed who controls Congress.
They changed what legislation is likely to pass.
They changed the balance of political power for the final two years of Trump’s presidency.
But they didn’t change the arithmetic.
And when it comes to your long-term savings, the arithmetic matters more than the election map.
The dollar buys less today than it did a year ago, a decade ago, a generation ago. That slide is the predictable result of endless printing and borrowing. Dr. Ron Paul believes the FED has the answer. But they’re keeping it to themselves. Fortunately, a new financial chart has publicly exposed their secret moves. See it for yourself: https://freekit.birchgold.com/lf/ro...D_v02a_article&placement=article&cid=rp_media
To learn more about how physical gold could help protect your retirement portfolio, click here to get your FREE info kit on Gold IRAs from Birch Gold Group. And now introducing a Crypto IRA to capitalize on the fastest growing market in the world.
Tweet
Continue reading...
[ H/T The Burning Platform ]
Family gatherings around the holidays have a funny way of reminding us just how difficult compromise can be.
My five-year-old nephew would happily eat McDonald’s chicken nuggets (because he wants the toy). My mother prefers the traditional sit-down meal – roast chicken, mashed potatoes, the whole thing. Then there’s that one cousin who insists on sushi or extra-spicy General Tso’s chicken…
Personally, I’m happy to let somebody else negotiate the menu.
I just want everyone fed and happy at the end of the evening.
Politics can feel like that.
Most Americans disagree about how Washington should get from here to there. But underneath all the partisan arguments, most of us want remarkably similar things from the economy:
- A decent standard of living
- Stable prices
- Freedom and opportunity for ourselves and our families
- Finally, enough savings to live with dignity when our working years are behind us
The 2026 midterm elections changed who gets to decide how the federal government pursues those goals.
What they did not change is the arithmetic those lawmakers inherited.
And that may matter much more to our financial futures than which party won election night…
What the midterms changed
The election produced a major shift in Congress.
Democrats won majorities in both the House and Senate, according to the Associated Press, replacing the GOP majority in the House and the divided Senate.
That changes the balance of power considerably.
President Trump still controls the executive branch, as he recently reminded us:
Starting in January, though, Democrats will control Congress.
Usually, that means neither side can simply do whatever it wants.
Remember, Congress controls legislation and federal appropriations. The President can sign legislation into law or veto it. Congress can override a presidential veto, but only with the constitutionally required supermajorities. That doesn’t happen very often; historically, presidential vetos are only overridden about 0.5% of the time.
Trump has already signaled he intends to use his veto power when he disagrees with the new Congress…
So the next two years may involve a great deal of negotiation.
Or gridlock.
Probably some of both.
Now, there are circumstances in which gridlock can be perfectly healthy. If Congress can’t agree on some big new program, well, I believe doing nothing is preferable to doing the wrong thing. That’s probably what the authors of the Constitution intended, as well.
There’s just one problem with that theory: Doing nothing does not mean the federal government’s financial problems stand still.
The debt meter keeps running.
The election didn’t change this $1.9 trillion number
The Congressional Budget Office’s latest baseline puts the federal deficit for fiscal year 2026 at about $1.9 trillion.
That’s not the national debt.
That’s the projected shortfall for one year – the annual gap between what Washington’s income and spending.
The CBO does not expect that gap to disappear. Quite the opposite.
The agency projects the annual deficit will continue to rise, reaching $3.1 trillion by 2036.
Here’s another way of looking at those numbers…
CBO says deficits averaged about 3.8% of the economy over the last 50 years. This year’s deficit is projected at 5.8%.
By 2036? 6.7%.
That is not primarily a prediction about Democrats and their plans. It’s not a prediction about Republicans, either. The CBO is known as the least partisan office in the federal government.
No, this is a projection of what happens under laws already on the books.
That distinction matters. The CBO is describing the status quo.
Because elections can change the government overnight.
Elections don’t automatically change decades of spending commitments.
Government debt keeps growing despite gridlock
CBO projects federal debt held by the public at roughly 101% of GDP in 2026. We’re discussing “federal debt held by the public” because that’s the portion of the debt that actually represents borrowing from financial markets. For measures of fiscal pressure, interest costs, debt sustainability and capital markets, it’s the part of the national debt that matters most.
CBO explains this explicitly in their Budget and Economic Outlook: 2026 to 2036. Debt held by the public is the measure used because it “best captures federal borrowing that affects interest rates and private investment.” See, when the Treasury Department borrows from outside investors, they’re competing with corporate and private borrowers for available funds. That’s how federal debt can contribute to higher borrowing costs and “crowd out” private investment by making it too expensive.
The last time America carried this much debt, it took nearly three decades to bring the burden back down. And we didn’t simply “grow our way out of it.”
After World War II, Washington cut spending sharply enough to run primary budget surpluses (in other words, they paid down the debt). The economy boomed while inflation exploded (17.6% in 1946-1947!), reducing the value of the existing debt. And for years, the Federal Reserve deliberately held government borrowing costs below the rate of inflation. Inflation alone eliminated about 1/4th of the total debt.
The plan worked. Federal debt fell from 106% of GDP in 1946 to 23% by 1974. That’s right, it took nearly three decades to work off the debt burden… And the public paid a price: The dollar lost about 60% of its purchasing power along the way.
So history tells us America can escape a debt burden this large. It also tells us the cure wasn’t painless.
That’s bad enough. But here’s the uncomfortable part of that historical comparison: Today, we have the debt without the surpluses.
CBO doesn’t expect Washington to begin paying down the debt. That’s reasonable, since the last year of federal surplus was 2001, 25 years ago. CBO expects debt to climb from 101% of GDP today to 120% within ten years.
Now, ten years is a long time.
Economic growth could come in stronger than expected.
Congress may reduce spending.
Lawmakers might increase federal revenue.
Maybe the Federal Reserve holds interest rates below inflation.
Or some combination of all four could conceivably improve the picture.
Frankly, though, the opposite looks a lot more likely to me. And the longer those deficits continue, the more government pays just to refinance old debt.
CBO expects net interest costs to rise from 3.3% of GDP this year to 4.6% in 2036.
That may sound abstract. Trust me, it isn’t.
Every dollar devoted to servicing government debt is a dollar Washington cannot spend somewhere else. Not without either cutting another priority, collecting more revenue or borrowing even more.
That is the debt trap. Steve Bannon’s End of the Dollar Empire explores this concept in volume three, The Debt Trap.
And gridlock alone does not get us out of it.
Social Security didn’t get an Election Day reprieve, either
Then there’s Social Security.
The 2026 Social Security Trustees Report projects that the Old-Age and Survivors Insurance Trust Fund – the fund that pays retirement and survivor benefits – will be able to pay full scheduled benefits until the fourth quarter of 2032.
That is one quarter earlier than last year’s projection.
Now, “trust fund depletion” does not mean Social Security suddenly disappears.
That distinction is important.
Social Security would continue collecting payroll taxes.
But according to the Trustees, continuing income at that point would be sufficient to pay only about 78% of scheduled OASI benefits unless Congress makes changes beforehand.
That is a much more accurate description than saying Social Security will “run out of money.”
But I doubt the distinction would be especially comforting to a retiree who had planned a household budget around receiving 100% of the benefits promised under current law.
Congress has options.
Lawmakers could adjust taxes.
They could adjust benefits.
They could change eligibility rules.
They could combine approaches.
What they cannot do is vote away the mathematics.
Some combination of money coming in and money going out eventually has to balance.
This is why I don’t think the election solved the real problem
There’s going to be an enormous temptation over the next few months to interpret every economic development through a partisan lens.
If something improves, one side will take credit.
If something gets worse, the other side will get blamed.
That’s politics.
But I think it can distract us from something much more important.
The federal government entered this election spending substantially more money than it collects.
It exited the election doing exactly the same thing.
Social Security entered the election on a path toward reserve depletion.
It exited the election on exactly the same path.
Federal debt was rising on Monday.
It was still rising on Wednesday.
Election night changed the people holding some of the levers.
It did not change the machine.
And that means neither political party deserves to be treated as a substitute for your own financial planning.
Gold’s post-election move was interesting – but don’t oversimplify it
Financial markets reacted quickly to the election.
Reuters reported that spot gold surged about 3.4% on November 4, its strongest daily gain since August, as the U.S. dollar weakened following the Democratic sweep of Congress.
By the end of the week, gold remained more than 5% higher despite giving back some of those gains.
It would be easy to draw a very simple conclusion from that:
Democrats won, therefore gold went up.
I don’t think that’s a very useful way to understand what happened.
Financial markets were digesting several things at once – a weaker dollar, changing expectations for government policy, inflation, monetary policy and the likelihood of political gridlock.
Gold frequently responds to uncertainty in the financial system.
But a one-day move tells us very little about what happens over the next five or ten years.
The more important lesson, in my view, is why investors turn toward assets like physical gold during periods when the economic or political path becomes harder to predict.
Your savings shouldn’t depend on Washington getting everything right
Maybe Democrats and Trump find areas of compromise.
I hope they do.
Maybe economic growth accelerates enough to make today’s fiscal projections look overly pessimistic.
I hope that happens, too.
Maybe Congress reaches a bipartisan agreement that puts Social Security on stronger footing and slows the growth of government debt.
Wonderful.
But if you’re planning for retirement – or simply trying to preserve what you’ve spent decades accumulating – I don’t think your financial future should require all of those things to go right.
That’s what diversification is for.
You don’t diversify because you know exactly what happens next.
You diversify because you don’t.
Physical precious metals are one way some Americans choose to diversify a portion of their savings outside the dollar-based financial system.
Gold isn’t guaranteed to rise.
Its price fluctuates.
And owning precious metals cannot eliminate financial risk.
But physical gold does not depend on Congress passing a budget on time.
It doesn’t depend on one political party defeating another.
And it doesn’t require a ten-year CBO forecast to come true.
That’s a useful quality when Washington itself seems increasingly difficult to forecast.
The midterms changed Washington.
They changed who controls Congress.
They changed what legislation is likely to pass.
They changed the balance of political power for the final two years of Trump’s presidency.
But they didn’t change the arithmetic.
And when it comes to your long-term savings, the arithmetic matters more than the election map.
The dollar buys less today than it did a year ago, a decade ago, a generation ago. That slide is the predictable result of endless printing and borrowing. Dr. Ron Paul believes the FED has the answer. But they’re keeping it to themselves. Fortunately, a new financial chart has publicly exposed their secret moves. See it for yourself: https://freekit.birchgold.com/lf/ro...D_v02a_article&placement=article&cid=rp_media
To learn more about how physical gold could help protect your retirement portfolio, click here to get your FREE info kit on Gold IRAs from Birch Gold Group. And now introducing a Crypto IRA to capitalize on the fastest growing market in the world.
Tweet
Continue reading...
[ H/T The Burning Platform ]