

There has been a hidden financial war behind the scenes for at least two decades. China has diagnosed a “new/old economy crossover” challenging the Western US dollar-based global financial system.
Protect & SurviveThe Financial Jigsaw Part 2 (Episode 91) Leading on from last week, the focus is why gold is now taking on its true position of protecting against a crisis of confidence in US Treasuries. “The banks and their regulators assign government debt privileged treatment because they have declared it “risk-free,” but no investment is free of risk. The label exists because government needs financial institutions to purchase its bonds, and admitting that sovereign debt can become unstable would expose the fraud supporting the entire system. The BIS estimates that the probability of a financial-stress event comparable to the Global Financial Crisis is increasing.” Martin Armstrong explains.
Something significant is happening in the global financial system. Central banks, the institutions responsible for managing national currencies and monetary policy, have been quietly accumulating gold at a pace not seen in generations. This isn’t a temporary blip or a reaction to a single crisis. It’s a structural shift in how the world’s most powerful financial institutions think about money, risk, and the future of global reserves. So why are central banks buying gold again?
I wrote last week: “…every dollar in circulation began its life as somebody’s debt. The mathematics of this arrangement contain a problem the inventors understood and the public refuses to recognise. When the principal is created and the loan is made, the interest is not. The interest must come from a future loan, made by someone else, and that loan in turn carries its own interest, which must come from a third loan, and so on into perpetuity.” This is the basis of the Western Global Financial System, which relied entirely on an expanding economy over some 200 years, and gave America is exceptional privilege of US dollar supremacy inherited from the City of London after WW2.
Austrian’s Newsletter is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
This happy situation (for the West) is coming to an end as the driving force of finite cheap resources, especially energy, begins to slow and eventually reverse. This calls for a new global financial model to match production with real investments as opposed to speculation in complex fiat derivatives. I suspect that the extreme US AI buildout is driven by the need to preserve the current fiat system using, among other things, Digital ID and CBDCs as a total control system using a programmable money alternative.
“In 2013, a think tank from London proposed a new public body to decide how to spend the money central banks create. The New Economics Foundation called it the Monetary Allocation Committee in a report titled Strategic Quantitative Easing. It would sit alongside the Bank of England’s Monetary Policy Committee but with a different job: while the MPC decided how much money to create, the Monetary Allocation Committee would decide where it went.”
“The report came out eighteen months before Mark Carney’s ‘Tragedy of the Horizon’ speech, two years before the Paris Agreement, and four years before the Network for Greening the Financial System was founded. The body to direct centrally created money was designed before the ‘voluntary’ rules that would eventually make that direction compulsory. That framework’s now largely built. The question is how, and by whom.” This is explained in detail HERE.
China’s financial model has already adapted to the prevailing conditions which I will explain in the coming episodes.
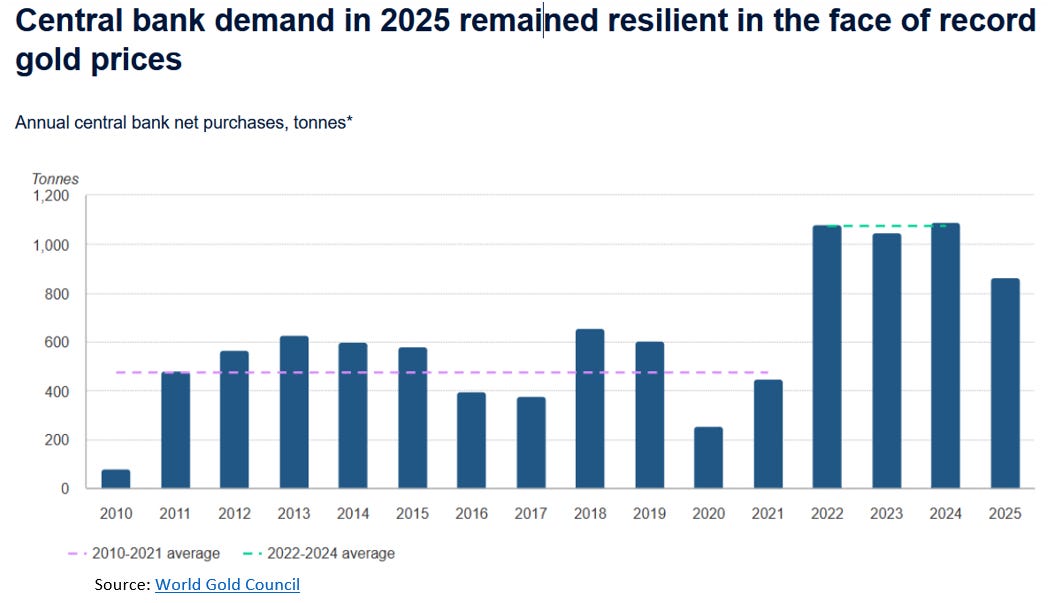
In the meantime, I will let the numbers tell the story. The scale of central bank gold buying in recent years is staggering. According to the World Gold Council, central banks added over 1,000 tonnes of gold to their reserves in 2022-4, with the 2022’s 1,082 tonnes marking the highest level of net purchases since 1950. In 2023, purchases reached 1,037 tonnes, the second-highest annual total on record, followed by approximately 1,045 tonnes in 2024. Full-year 2025 data shows 863 tonnes added globally, below the four-figure pace of recent years, but still well above the long-run historical average as shown in the chart above.
To understand how extraordinary this is: from 2010 to 2021, the average annual pace was around 473 tonnes. In just three years, central banks nearly doubled their rate of accumulation. And even as buying moderated in 2025, partly due to record-high gold prices prompting a more measured approach, the broad strategic commitment remained intact, with 23 countries adding to reserves in H1 2025 alone. Central banks have now been net buyers of gold for 16 consecutive years. (Note the date of 2013 in the above referenced extract.)
For decades, the US dollar has served as the world’s dominant reserve currency. Central banks held US Treasuries as their primary store of value. But confidence in this arrangement has been eroding. A major turning point came when the US and its allies froze Russia’s foreign exchange reserves following the 2022 invasion of Ukraine. The message was clear to governments worldwide: dollar-denominated assets held abroad can be seized or restricted during geopolitical conflicts. Gold, by contrast, carries no such risk. It cannot be frozen, sanctioned, or devalued by a foreign government’s policy decision.
This has accelerated reserve diversification, particularly among emerging markets. China especially, India, Poland, Singapore, Turkey, and dozens of other nations have been steadily reducing their dependence on dollar assets while building gold holdings. Japan has recently entered the picture as the yen has come under pressure and the US Treasury is attempting to manage the risk of their bond price declining and thus interest rates rising.
Beyond the Russia-Ukraine conflict, the broader geopolitical landscape has grown considerably more complex. Tensions between major powers, regional wars, and shifting trade alliances have all contributed to a flight toward assets considered politically neutral and universally accepted.
Gold has historically served this role. It holds no nationality, carries no counterparty risk, and has been recognised as a store of value across civilizations for thousands of years. In a world where alliances are shifting and financial infrastructure can be weaponised, central banks are treating gold as the ultimate form of financial insurance. An example is Scott Bessent’s recent threat of secondary sanctions on any nation or entity that continues to trade with Iran, buy its oil, or facilitate its financial transactions.
As one analyst from the Official Monetary and Financial Institutions Forum (OMFIF) noted, geopolitical events have laid a foundation for gold to become prominent once again in central bank reserve portfolios and as a means of settling payments between certain countries. China is reshaping not only production and consumption patterns but also the role and architecture of its financial system. This shift marks the entrance of where finance is deliberately subordinated to the needs of the real economy, productive accumulation and high-quality development, rather than permitted to pursue self-referential expansion as seen in the current Western global financial system.
The inflationary surge following 2020 reminded central banks of a fundamental vulnerability in fiat currency systems: governments can print money, and when they do, purchasing power erodes. Gold cannot be printed. While central banks spent 2022-3 raising interest rates to fight inflation, many simultaneously bought gold, a seemingly contradictory move, that reflects sophisticated long-term thinking. Gold isn’t a short-term trade for these institutions; it’s a multi-decade hedge against the systemic risks of debt-fuelled monetary expansion. One might speculate that it also provides a hedge against the Chinese financial model prevailing, at least in the global south.
For most of the post WW2 era, US Treasuries were considered the safest asset in the world. That status is increasingly being questioned. Rising debt levels, fiscal dysfunction, and the risk of real returns being eroded by inflation have made central banks more sceptical of sovereign debt as a reserve asset. Gold, by contrast, has no credit risk, no counterparty, and no maturity date. Its value doesn’t depend on any government’s ability or willingness to honour an obligation. For institutions managing national reserves over decades-long time horizons, these properties are deeply attractive.
The buying is being led by emerging market central banks, though the trend has now spread to developed economies as well. China remains one of the most prominent buyers, having officially added 225 tonnes between late 2022 and 2023, with total reported reserves reaching approximately 2,300 tonnes. Gold still accounts for only about 5-7% of China’s total reserve portfolio suggesting significant room to continue accumulating.
The financialised logic of Western capitalism tends toward over-accumulation of fictitious capital and periodic Minsky-style crises compared with China’s strategy. China seeks to ensure finance remains tethered to the metabolic capabilities of the energy and material substrate of the real economy thereby preventing detachment into speculative shells whilst mobilising dormant savings into productive applications.
Poland has been one of the most aggressive gold buyers among European nations, adding over 100 tonnes in 2025 alone. Its reserves now stand at 550 tonnes and account for roughly 28% of total international reserves, approaching an updated target of 30%, a goal Poland raised from its prior 20% target in October 2025.
India has steadily increased its gold reserves, adding over 200 tonnes since 2017. In 2024, India repatriated 100 tonnes of its gold from the Bank of England’s vaults to return homeward, a signal of shifting trust in Western custodianship. Singapore, Turkey, Kazakhstan, Brazil, Czech Republic, and many others have all added meaningfully to their gold holdings in recent years. The breadth of buying is arguably as significant as the volume. Notably, 68% of central banks now store most of their gold within their own borders, up from roughly 50% in 2020. The freezing of Russia’s overseas assets prompted many nations to repatriate their gold rather than hold it in Western vaults.
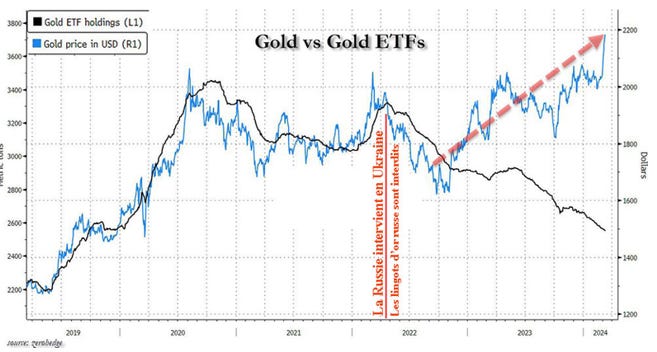
The scale of central bank demand has fundamentally reshaped gold market dynamics. These institutions generally buy based on long-term strategic reserve management goals rather than short-term price movements which create a persistent floor beneath gold prices. That said, the WGC noted that the record-high price environment in 2025 did prompt some moderation in the pace of buying, a reminder that central banks are not entirely immune to price considerations.
From 2021 to mid-2024, gold exchange traded funds (ETFs) were actually net sellers and yet gold prices rose significantly anyway. That divergence is highly unusual. Historically, ETF flows and gold prices move closely together. The decoupling reveals just how powerful central bank demand has become as an independent price driver. This is one reason why gold demand has remained robust even during periods of high interest rates and a strong US dollar; conditions that historically weighed on gold prices.
Is This a Sign of Economic Uncertainty? It is, but it’s more than that. Central banks don’t make reserve allocation decisions lightly. These institutions manage sovereign wealth across multi-decade horizons, and when they shift their behaviour as dramatically as they have done since 2022, it reflects deep structural concerns rather than short-term market sentiment. The shift to gold signals three things simultaneously:
- declining confidence in the dollar-centric reserve system
- rising concern about geopolitical and financial instability
- long-term reassessment of what “safe” actually means in a reserve portfolio.
This trend is worth paying close attention to. When the world’s most sophisticated and well-resourced financial institutions consistently move in the same direction, it’s a signal worth understanding.
Central banks aren’t buying gold because they expect a quick profit. They’re buying it because the global financial system is undergoing a meaningful structural shift away from dollar dominance, toward a more multipolar reserve landscape where no single currency holds absolute sway.
Gold, with its universal acceptance, political neutrality, and centuries-long track record as a store of value, sits at the centre of that transition. The institutions with the deepest research capabilities, the longest time horizons, and the most at stake have been making this bet consistently for 16 years and doubling down recently. That’s a signal worth taking seriously:
“Bloomberg’s index of how easy it is to raise money across stocks, credit, and rates just closed at the easiest level in its 35-year history, looser than 2021 and looser than the dot-com peak. This is the liquidity holding stocks, gold, and credit near records all at once. Conditions this loose have never lasted. When they tighten, the most leveraged trades, AI and credit, unwind first.”
“Kurt Altrichter explains just how easy the Fed and their owners are acting when it comes to credit, as we enter the crash zone. Everyone is going to keep dancing until the music stops, just as they were doing in 2007. There is a reason Berkshire Hathaway was sitting on $400 billion of cash in the first quarter. The market is 50% more overvalued than it was in 2008 before the last Fed induced financial crash. Winter is coming.” Sources
- Jim Quinn (TBP) “The financial history of the last century shows a steady increase in the amount of public indebtedness. Nobody believes that the states will eternally drag the burden of these interest payments. It is obvious that sooner or later all these debts will be liquidated in some way or other, but certainly not by payment of interest and principal according to the terms of the contract.” [Ludwig von Mises] https://www.theburningplatform.com/...s-coming-because-they-planned-it/#more-421382
- Central Banks are buying gold – edited extracts https://goldsilver.com/industry-news/article/why-central-banks-are-buying-gold-again/
Tweet
Continue reading...
[ H/T The Burning Platform ]