
Jefferies Beats On Record Stock Trading, But Asset Management Revenue Plunges 50% On First Brands, Radiant "Cockroaches"
Jefferies is once again the first major Wall Street firm to report its quarter, and once again the story is of two very different banks under one roof: a trading and banking franchise running near record highs, and an asset-management arm that keeps finding new ways to lose money on receivables that may or may not exist.
The good news first. In the fiscal third quarter ended August 31, Jefferies reported EPS of $1.08, beating the $1.00 consensus (core EPS of $1.08 also beat Goldman's $1.03 and the Street's $1.01). Core pre-tax income came in 9% ahead of the Street, driven by:
And then there's the asset-management unit, where net revenue fell to $85.6 million from almost $177 million a year earlier. That's a 52% drop, and it comes from the same two names that have been following Jefferies around for a year: First Brands and Radiant World, both held through Leucadia Asset Management's Point Bonita trade-finance fund.
The stock fell 1.1% in early trading, taking the YTD decline past 25%. That is a strange reaction to a record quarter, unless you remember how the last twelve months have gone.
Goldman's James Yaro headlined his overnight note "Equities trading and expense beat, outlook and momentum remain largely the same." That is sell-side for "fine, nothing to see here," and Goldman does expect "a slightly constructive response to results." Look closer, though, and the note is a good deal less relaxed than the title.
First, the good parts, per Goldman:
Now the less good parts, starting with the quality of the beat:
And then there is asset management, where the headline number actually understates the damage. Strip out merchant banking and Jefferies' core asset-management revenue was just $13 million, against Goldman's $38MM estimate and the Street's $36MM. That's a 66%/64% miss, "primarily driven by lower investment returns." In response, Goldman cut its 2026E/27E/28E asset management revenue by 22%/11%/6%.
Goldman's rating is still Buy, but look at what it did to valuation. The bank (full report here) cut its target multiple by 2.5x to 11.0x and its 12-month price target by ~15%, from $67 to $57, even as its 2026 EPS estimate rose 2%. It also offered a telling explanation for the stock's persistent discount: "we believe that the market discounts the multiples assigned to these businesses, given their volatility." Put simply, even when Jefferies beats, investors won't pay up for the kinds of earnings it produces.
The chart in the Goldman note shows the result: JEF is down 29.4% over twelve months, and 39.4% behind the S&P 500. The stock peaked just as First Brands was about to blow up and has spent the year since trailing the market.
Vital Knowledge's Adam Crisafulli gave the quarter a fitting grade: "Not amazing, not horrible." He also questioned how long the equities boom can last, which is a reasonable question when the entire Street is printing record equities revenue on the same trade.
The wider read-across is positive for the rest of the Street's equity desks. BofA's Brian Moynihan said earlier this month that equity trading was up in the quarter through mid-September, and Goldman's David Solomon said equities remained "very strong." In FICC, BofA warned that revenue was down and "bouncing around," and Jefferies' -26% suggests that was an understatement.
Management kept the upbeat tone. CEO Rich Handler and President Brian Friedman said they "remain confident in the long-term outlook" for asset management as they "reposition the platform by reducing capital allocated to certain existing funds." In other words, Point Bonita is being wound down. The plan is to put the capital into Hildene, the credit manager Jefferies agreed in December 2025 to buy 50% of, alongside Hildene's $550 million purchase of annuity writer SILAC. Replacing a trade-finance fund that blew up on receivables with a credit shop that owns an insurer is one way to diversify, at least.
As a reminder of how we got here:
That view lasted about a month. Since then:
Then there is the question of how much Jefferies actually has at risk. Bloomberg has put Jefferies' exposure at "less than $300 million." But according to a creditor schedule the founder submitted to the court, Jefferies is Radiant's largest creditor at $353 million, well ahead of Intesa ($238MM), Deutsche Bank ($103MM) and Mizuho ($97MM), out of $870 million total. The fraud claim filed by the fund is for $500 million. Pick a number.
For the rest of the Street, the Jefferies print is good news: equities are booming, the ECM window is wide open, advisory is at records, and backlogs are "broad and strong" ("very optimistic about the balance of 2026 and our momentum heading into 2027," per Handler and Friedman). JPM's Market Intel desk, which this morning went back to "Tactically Bullish," said that outside of AI plays it favors banks, given "the growth reboot, potentially steeper yield curve, and favorable capital markets outlook."
For Jefferies itself, the market is saying something different. The stock is down more than 25% YTD and nearly 30% over twelve months despite record trading and advisory. Goldman's Buy rating now sits on a price target 15% lower and on a multiple that assumes investors will keep charging a volatility discount. Goldman even lists "a much longer timeframe to wind down the merchant bank" among its downside risks.
After First Brands, MFS, and now an iron-ore trader with $10,000 in its account and a fake Glencore email, the market isn't asking whether there are more cockroaches. It's asking where the next one is.
Tyler Durden Tue, 09/29/2026 - 12:30
Continue reading...
[ H/T ZeroHedge ]
Jefferies is once again the first major Wall Street firm to report its quarter, and once again the story is of two very different banks under one roof: a trading and banking franchise running near record highs, and an asset-management arm that keeps finding new ways to lose money on receivables that may or may not exist.
The good news first. In the fiscal third quarter ended August 31, Jefferies reported EPS of $1.08, beating the $1.00 consensus (core EPS of $1.08 also beat Goldman's $1.03 and the Street's $1.01). Core pre-tax income came in 9% ahead of the Street, driven by:
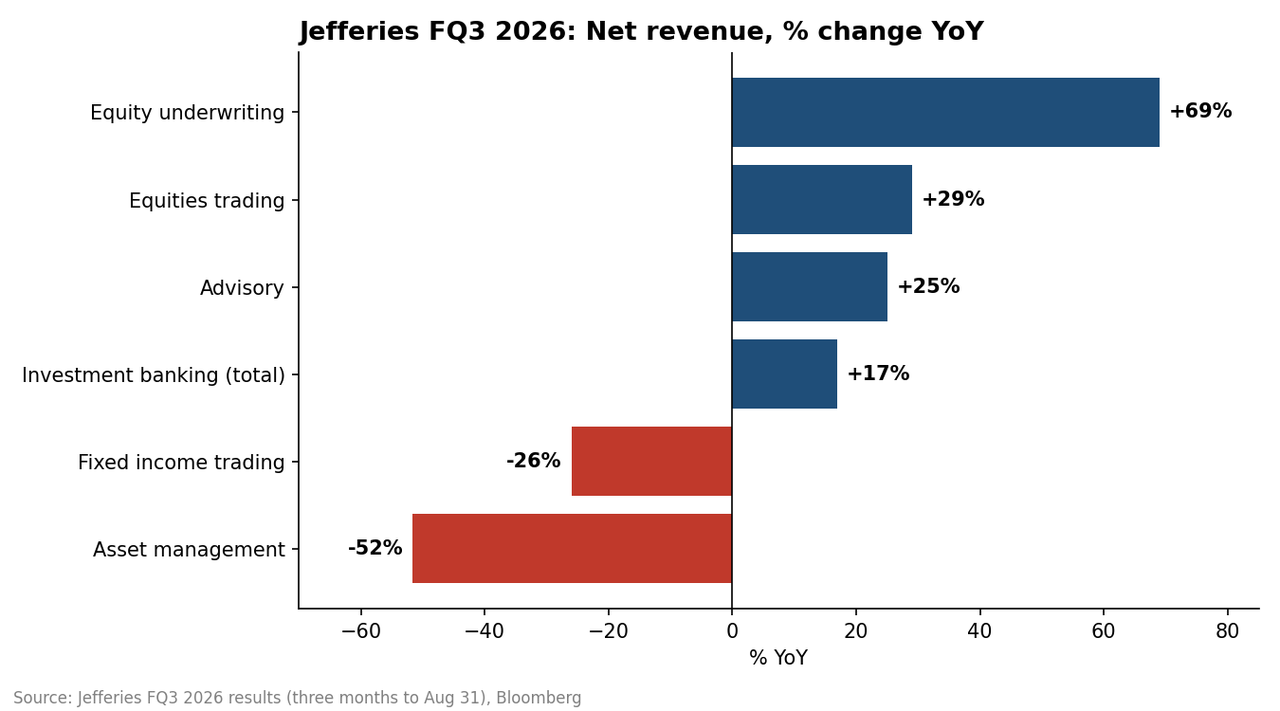
- Equities trading: $626 million, up 29% YoY and a record, helped by cash, electronic trading and prime services (i.e., hedge funds levering up into the AI melt-up).
- Investment banking: $1.3 billion, up 17%, with advisory up 25% (also a record) and equity underwriting up 69%.
- Fixed income trading: the laggard, with net revenue down 26% in what the bank called a sluggish market.
And then there's the asset-management unit, where net revenue fell to $85.6 million from almost $177 million a year earlier. That's a 52% drop, and it comes from the same two names that have been following Jefferies around for a year: First Brands and Radiant World, both held through Leucadia Asset Management's Point Bonita trade-finance fund.
The stock fell 1.1% in early trading, taking the YTD decline past 25%. That is a strange reaction to a record quarter, unless you remember how the last twelve months have gone.
Goldman: Buy... with a 15% lower price target
Goldman's James Yaro headlined his overnight note "Equities trading and expense beat, outlook and momentum remain largely the same." That is sell-side for "fine, nothing to see here," and Goldman does expect "a slightly constructive response to results." Look closer, though, and the note is a good deal less relaxed than the title.
First, the good parts, per Goldman:
- Equities: A second consecutive record at $626MM, 10%/14% ahead of GSe/Street, "with strength across all products, especially in prime."
- Advisory: Record quarterly revenue, "in part driven by a sponsor recovery, as well as broad-based share gains across sectors."
- Margins: A core pre-tax margin of 15.8%, about 150bps above consensus, thanks to a non-comp ratio about 145bps below the Street.
- Buybacks: 1.3MM shares repurchased in the quarter.
Now the less good parts, starting with the quality of the beat:
- The banking beat is the volatile kind. It "was primarily driven by other investment banking ($31mn vs. GSe/consensus at $5mn/11mn), the most volatile of JEF's IBanking business." Underwriting actually missed by 3%. ECM came in 4% short of the Street, even while growing 69% YoY, so expectations were running even hotter than the deal flow.
- Some of the expense discipline is really just shrinkage. A portion "likely relates to merchant banking wind-downs, which appear to have been larger than anticipated in terms of both revenue and expenses." Jefferies is spending less partly because there is less business left to spend on.
- FICC missed badly: 18% below the Street and 15% below Goldman.
And then there is asset management, where the headline number actually understates the damage. Strip out merchant banking and Jefferies' core asset-management revenue was just $13 million, against Goldman's $38MM estimate and the Street's $36MM. That's a 66%/64% miss, "primarily driven by lower investment returns." In response, Goldman cut its 2026E/27E/28E asset management revenue by 22%/11%/6%.
Goldman's rating is still Buy, but look at what it did to valuation. The bank (full report here) cut its target multiple by 2.5x to 11.0x and its 12-month price target by ~15%, from $67 to $57, even as its 2026 EPS estimate rose 2%. It also offered a telling explanation for the stock's persistent discount: "we believe that the market discounts the multiples assigned to these businesses, given their volatility." Put simply, even when Jefferies beats, investors won't pay up for the kinds of earnings it produces.
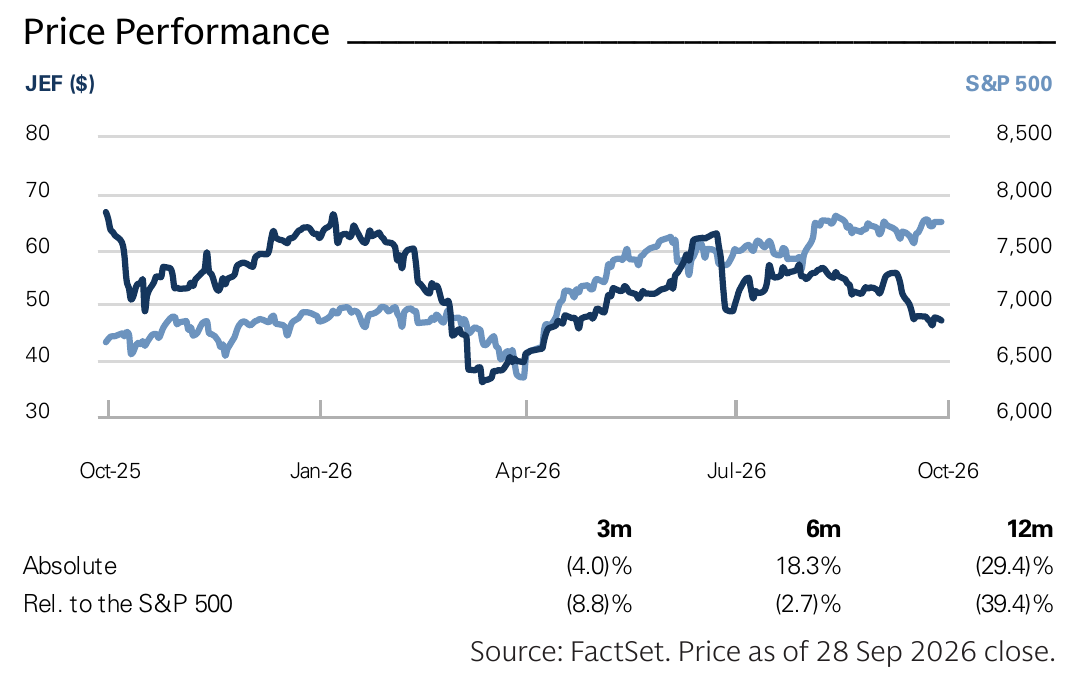
The chart in the Goldman note shows the result: JEF is down 29.4% over twelve months, and 39.4% behind the S&P 500. The stock peaked just as First Brands was about to blow up and has spent the year since trailing the market.
Vital Knowledge's Adam Crisafulli gave the quarter a fitting grade: "Not amazing, not horrible." He also questioned how long the equities boom can last, which is a reasonable question when the entire Street is printing record equities revenue on the same trade.
The wider read-across is positive for the rest of the Street's equity desks. BofA's Brian Moynihan said earlier this month that equity trading was up in the quarter through mid-September, and Goldman's David Solomon said equities remained "very strong." In FICC, BofA warned that revenue was down and "bouncing around," and Jefferies' -26% suggests that was an understatement.
The cockroach problem
Management kept the upbeat tone. CEO Rich Handler and President Brian Friedman said they "remain confident in the long-term outlook" for asset management as they "reposition the platform by reducing capital allocated to certain existing funds." In other words, Point Bonita is being wound down. The plan is to put the capital into Hildene, the credit manager Jefferies agreed in December 2025 to buy 50% of, alongside Hildene's $550 million purchase of annuity writer SILAC. Replacing a trade-finance fund that blew up on receivables with a credit shop that owns an insurer is one way to diversify, at least.
As a reminder of how we got here:
- First Brands. When the auto-parts roll-up collapsed into bankruptcy in the fall of 2025, it turned out that Point Bonita, which once managed roughly $3 billion, had about a quarter of its assets tied to First Brands receivables (around $715 million, per Jefferies' own October 2025 update). The DOJ then opened a probe into what we called First Brands' "shocking bankruptcy" (Oct 2025). A week later, Jamie Dimon's "when you see one cockroach, there are probably more" line became the market's official slogan, and JEF crashed more than 10% in a single session as regional banks crashed as more credit "cockroaches" emerged (Oct 16, 2025).
- Market Financial Solutions. Then, in February, Jefferies was again scrambling to recover what it could (Feb 27, 2026) after the collapse of UK bridging lender MFS, where we noted that "Banco Santander and Jefferies – both of which sank in the First Brands swamp" were once more in the line of fire.
- Radiant World. This is the latest one, and it is the ugliest. Radiant is a Singapore iron-ore trader that bought receivables from counterparties like Glencore and Vitol and financed them through banks and funds, including - drumroll - Point Bonita. In August, Hedgeweek reported that payments to the fund had "slowed," and several commodity houses stopped trading with Radiant over questions about its invoices. Jefferies was said to believe the underlying trades "remain legitimate."
That view lasted about a month. Since then:
- Sep 5: Jefferies' LAM Trade Finance fund won a UK freezing order against Radiant, founder Pinkesh Nahar, and affiliate Sapphire Minmetals. Parallel orders followed in Hong Kong and Singapore.
- Sep 8-9: The fund formally accused Radiant of fraud in a $500 million claim, alleging the iron-ore receivables "either did not exist or were not validly assigned."
- Sep 17: Radiant disclosed that it had about $10,000 in cash, compared with audited financials showing more than $200 million. Somewhere, an auditor is updating their LinkedIn.
- Sep 19: Radiant sued Glencore for $2 billion in Singapore, which is an interesting move for a company with $10K in the bank. Glencore has reportedly already taken a $480 million provision and told Mizuho that Radiant sent it a fake Glencore email about repaying a $95.5 million loan.
- Sep 24-25: KPMG was appointed interim judicial manager, a Singapore judge questioned Radiant's claimed $1 billion of receivables, and Bloomberg reported that Singapore police had received a fraud report months before the crisis, with Intesa Sanpaolo apparently suspicious of the invoices before anyone else.
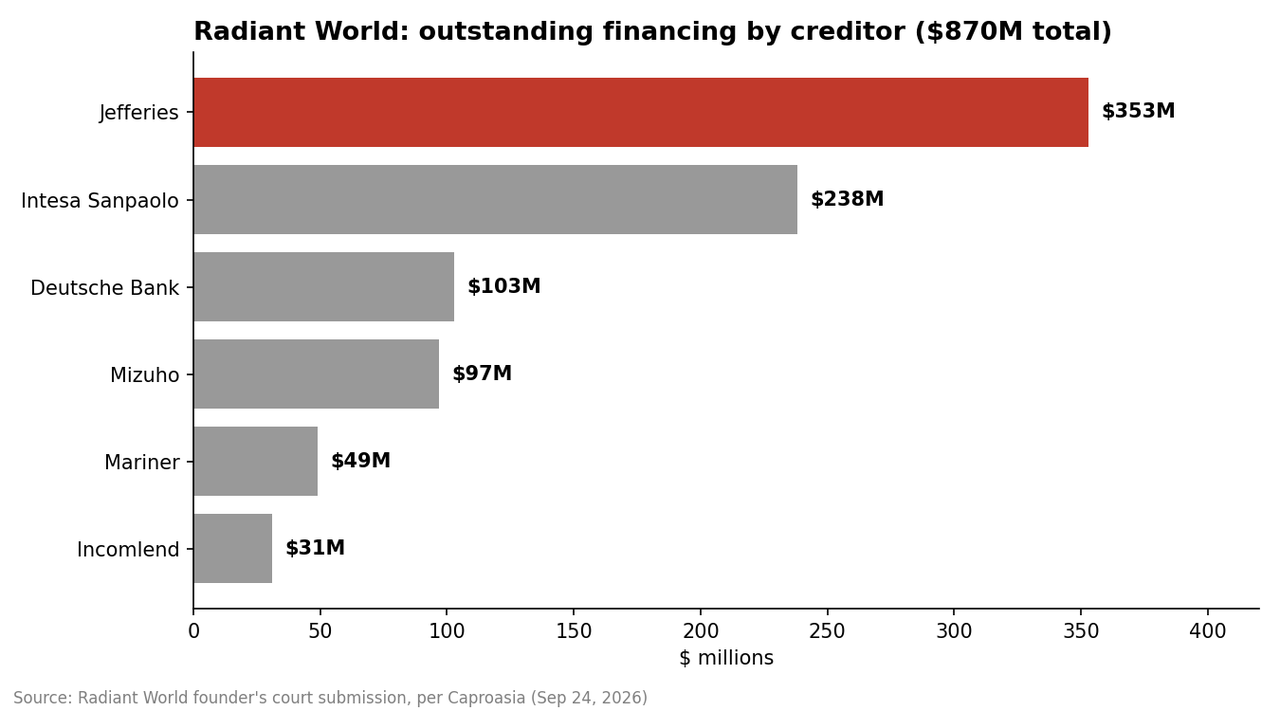
Then there is the question of how much Jefferies actually has at risk. Bloomberg has put Jefferies' exposure at "less than $300 million." But according to a creditor schedule the founder submitted to the court, Jefferies is Radiant's largest creditor at $353 million, well ahead of Intesa ($238MM), Deutsche Bank ($103MM) and Mizuho ($97MM), out of $870 million total. The fraud claim filed by the fund is for $500 million. Pick a number.
Bottom line
For the rest of the Street, the Jefferies print is good news: equities are booming, the ECM window is wide open, advisory is at records, and backlogs are "broad and strong" ("very optimistic about the balance of 2026 and our momentum heading into 2027," per Handler and Friedman). JPM's Market Intel desk, which this morning went back to "Tactically Bullish," said that outside of AI plays it favors banks, given "the growth reboot, potentially steeper yield curve, and favorable capital markets outlook."
For Jefferies itself, the market is saying something different. The stock is down more than 25% YTD and nearly 30% over twelve months despite record trading and advisory. Goldman's Buy rating now sits on a price target 15% lower and on a multiple that assumes investors will keep charging a volatility discount. Goldman even lists "a much longer timeframe to wind down the merchant bank" among its downside risks.
After First Brands, MFS, and now an iron-ore trader with $10,000 in its account and a fake Glencore email, the market isn't asking whether there are more cockroaches. It's asking where the next one is.
Tyler Durden Tue, 09/29/2026 - 12:30
Continue reading...
[ H/T ZeroHedge ]