Intel Crashes 25% As "Surprisingly Severe PC Correction" Shocks Wall Street
AI infrastructure stocks tumbled in premarket trading in New York after disappointing results from Amazon and Intel. Amazon is down about 7% following Thursday's earnings report, as cash burn surged and weak guidance spooked investors.
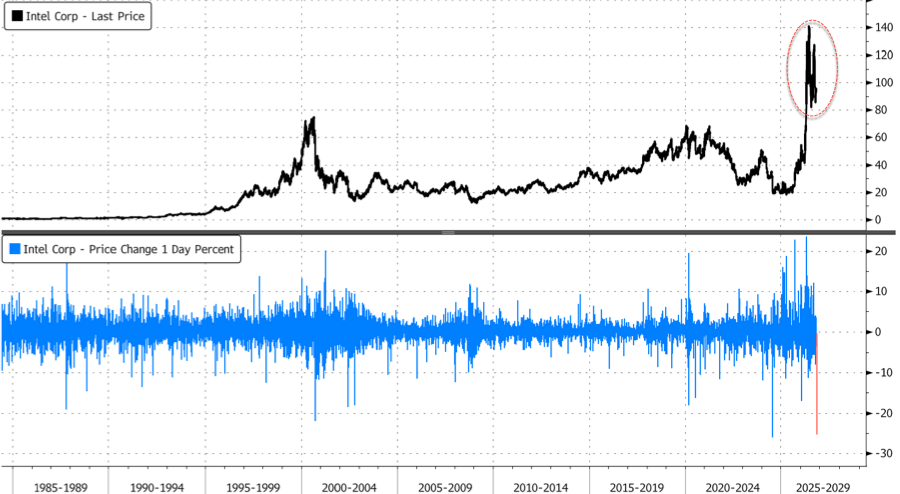
Shifting focus to Intel, shares are down 25% in premarket trading. If losses carry into the cash session and exceed 26%, the stock could be on track for its worst intraday decline in Bloomberg data going back to 1982.
For traders just waking up to the Intel bloodbath on their terminals, Thursday's outlook fell well below Bloomberg consensus expectations as weak PC demand and supply constraints overshadowed surging data-center sales.
Intel expects fourth-quarter revenue of $15 billion to $16 billion, compared with analysts' estimates of $17.05 billion. Adjusted earnings are projected at 25 cents a share versus expectations of 43 cents, while adjusted gross margin is forecast at 38%, below the 42.8% consensus.
The weak outlook overshadowed third-quarter adjusted earnings of 52 cents a share, which beat estimates of 41 cents. Revenue rose 21% to $16.51 billion, roughly matching expectations.
The results showed a massive divergence between Intel's businesses: Data Center & AI revenue surged 78% to $7.32 billion in the third quarter, exceeding the $6.67 billion estimate. But Client Computing sales fell 5.1% to $8.10 billion, missing expectations of $8.82 billion.
"Despite near-term headwinds affecting the broader PC industry, we continue to see robust demand for CPUs and more broadly, for all our computing platforms in the long term," CEO Lip-Bu Tan said.
CFO David Zinsner said, "Looking ahead, we see the PC slowdown continuing at least through the first half of next year."
Morgan Stanley analysts called the quarter a setback driven by a "surprisingly severe PC correction" and company-specific server issues. They also said, "Server CPU also slightly lower amid supply issues around the Israel fab accident and the ongoing substrate shortage."
Vital Knowledge analysts called the outlook "pretty horrible, and the stock will undoubtedly get crushed, although it would be much worse if Data Center/AI caused the weakness (it's not) as opposed to PCs."
"AI, which is why people are bulled up on INTC, is killing PCs, a business that still contributes a big chunk of the company's top line, as the data center boom drives up the price of memory, causing ASPs to rise which is hurting demand," Vital Knowledge analysts said.
Citi semiconductor analyst Atif Malik offered clients his first take on the earnings and outlook:
Here is Goldman's take:
Intel shares plunged 25% in premarket trading.
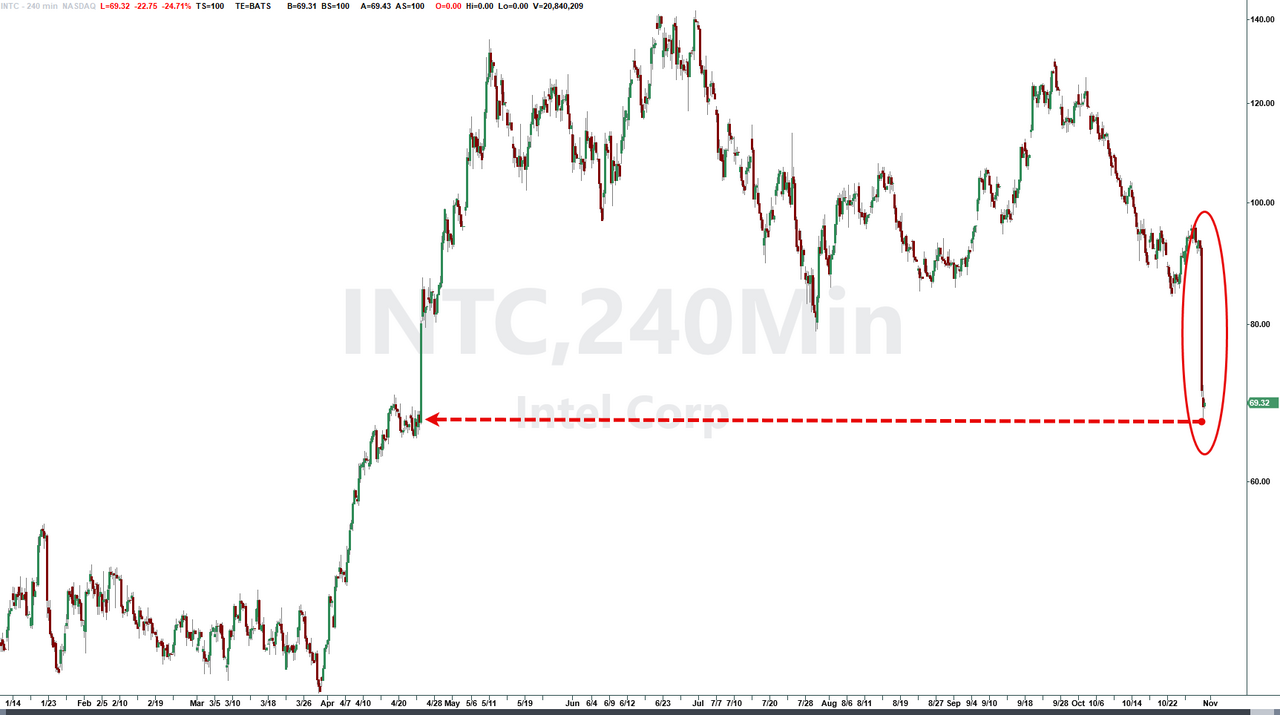
If losses exceed 26% by the close of the cash session, the decline could mark the stock's worst single-day performance in Bloomberg data going back to 1982.
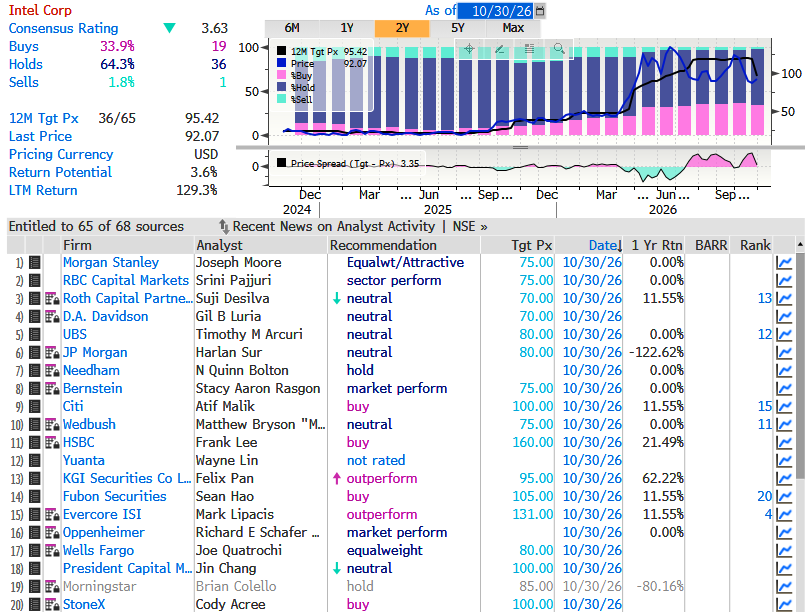
Analysts tracked by Bloomberg have an average 12-month price target of $95.42.
Read: "The Great Tech Unwind: Nasdaq Hits Make-Or-Break Levels."
Tyler Durden Fri, 10/30/2026 - 08:35
Continue reading...
[ H/T ZeroHedge ]
AI infrastructure stocks tumbled in premarket trading in New York after disappointing results from Amazon and Intel. Amazon is down about 7% following Thursday's earnings report, as cash burn surged and weak guidance spooked investors.
Shifting focus to Intel, shares are down 25% in premarket trading. If losses carry into the cash session and exceed 26%, the stock could be on track for its worst intraday decline in Bloomberg data going back to 1982.
For traders just waking up to the Intel bloodbath on their terminals, Thursday's outlook fell well below Bloomberg consensus expectations as weak PC demand and supply constraints overshadowed surging data-center sales.
Intel expects fourth-quarter revenue of $15 billion to $16 billion, compared with analysts' estimates of $17.05 billion. Adjusted earnings are projected at 25 cents a share versus expectations of 43 cents, while adjusted gross margin is forecast at 38%, below the 42.8% consensus.
The weak outlook overshadowed third-quarter adjusted earnings of 52 cents a share, which beat estimates of 41 cents. Revenue rose 21% to $16.51 billion, roughly matching expectations.
The results showed a massive divergence between Intel's businesses: Data Center & AI revenue surged 78% to $7.32 billion in the third quarter, exceeding the $6.67 billion estimate. But Client Computing sales fell 5.1% to $8.10 billion, missing expectations of $8.82 billion.
"Despite near-term headwinds affecting the broader PC industry, we continue to see robust demand for CPUs and more broadly, for all our computing platforms in the long term," CEO Lip-Bu Tan said.
CFO David Zinsner said, "Looking ahead, we see the PC slowdown continuing at least through the first half of next year."
Morgan Stanley analysts called the quarter a setback driven by a "surprisingly severe PC correction" and company-specific server issues. They also said, "Server CPU also slightly lower amid supply issues around the Israel fab accident and the ongoing substrate shortage."
Vital Knowledge analysts called the outlook "pretty horrible, and the stock will undoubtedly get crushed, although it would be much worse if Data Center/AI caused the weakness (it's not) as opposed to PCs."
"AI, which is why people are bulled up on INTC, is killing PCs, a business that still contributes a big chunk of the company's top line, as the data center boom drives up the price of memory, causing ASPs to rise which is hurting demand," Vital Knowledge analysts said.
Citi semiconductor analyst Atif Malik offered clients his first take on the earnings and outlook:
Here is Goldman's take:
Intel shares plunged 25% in premarket trading.
If losses exceed 26% by the close of the cash session, the decline could mark the stock's worst single-day performance in Bloomberg data going back to 1982.
Analysts tracked by Bloomberg have an average 12-month price target of $95.42.
Read: "The Great Tech Unwind: Nasdaq Hits Make-Or-Break Levels."
Tyler Durden Fri, 10/30/2026 - 08:35
Continue reading...
[ H/T ZeroHedge ]