Inflation Is 'Broadening Out' As Producer Prices Soar Most In 4 Years
After yesterday's accelerating CPI scare, this morning analysts expected a concomitant surge in producer prices - the big question remains whether it's all energy... or are price-hikes 'broadening out' making The Fed's job harder.
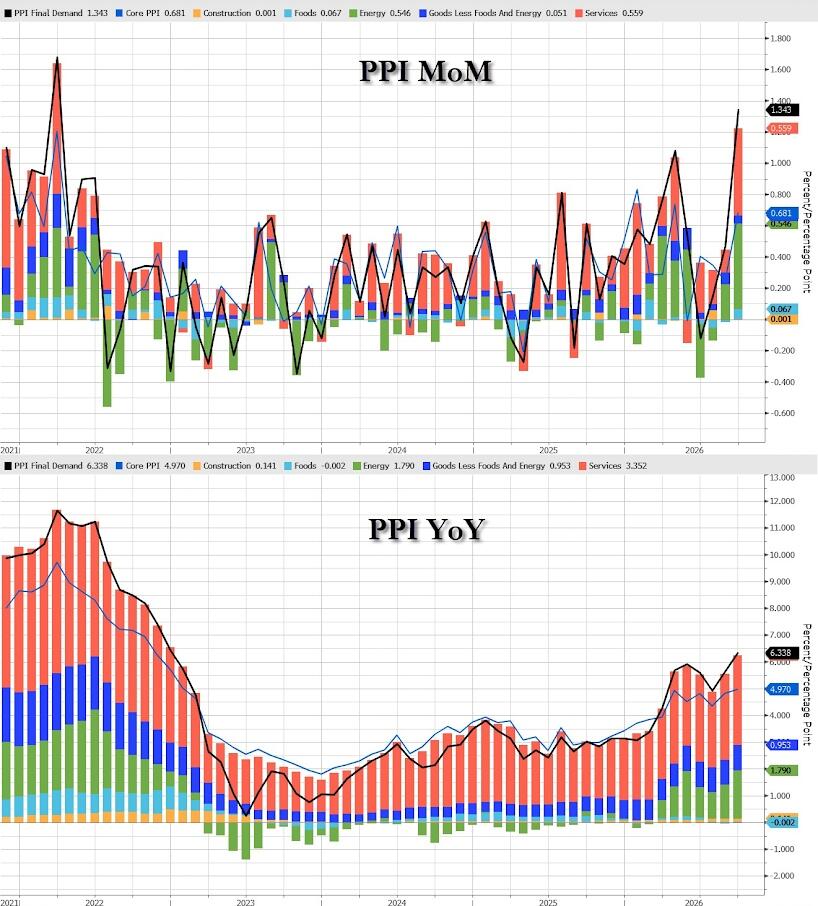
Headline PPI exploded higher in September, rising 1.3% MoM (more than double the 0.6% expected and biggest monthly jump since March 2022), dragging producer prices up 6.3% YoY (+5.4% exp) - the highest since Dec 2022...
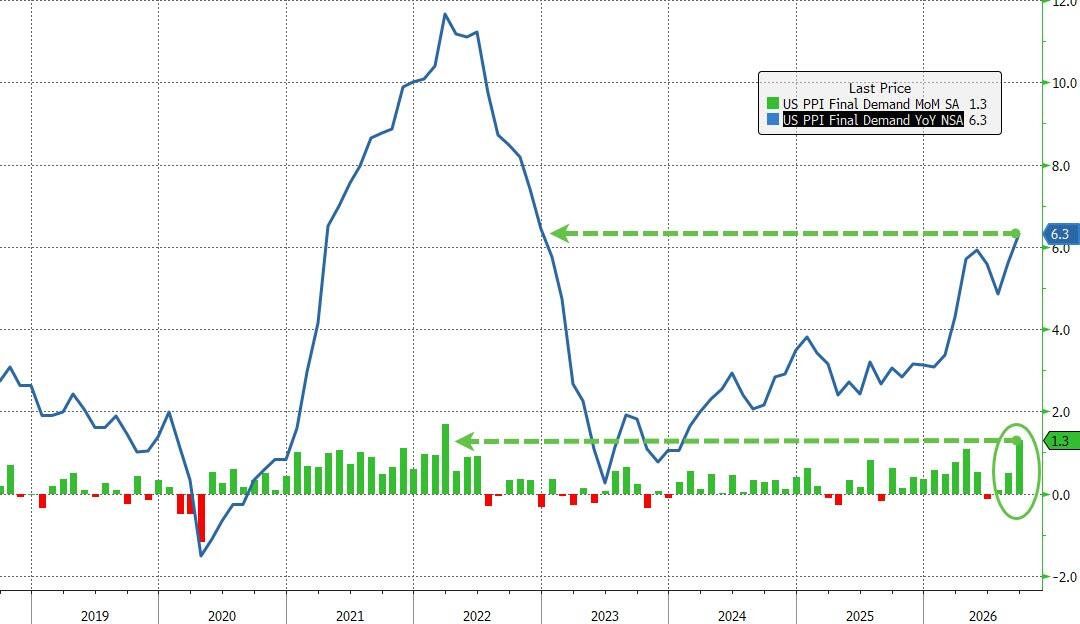
Energy dominated the surge in prices...
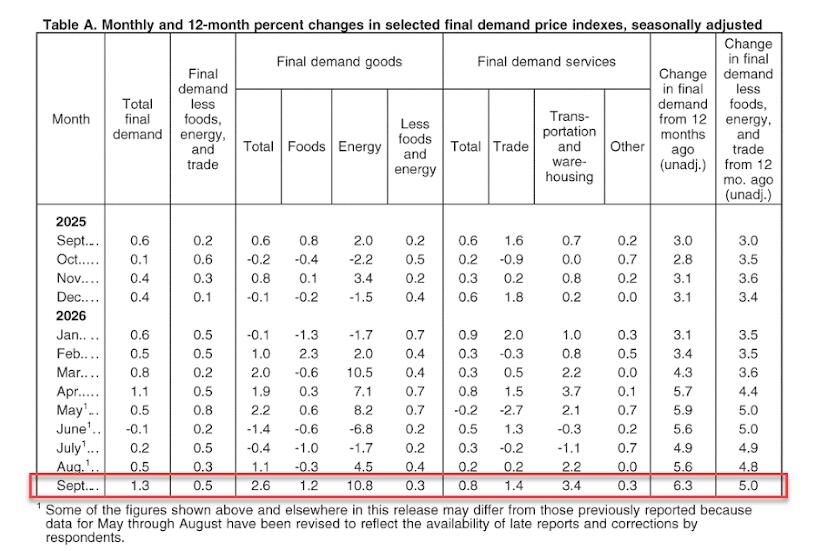
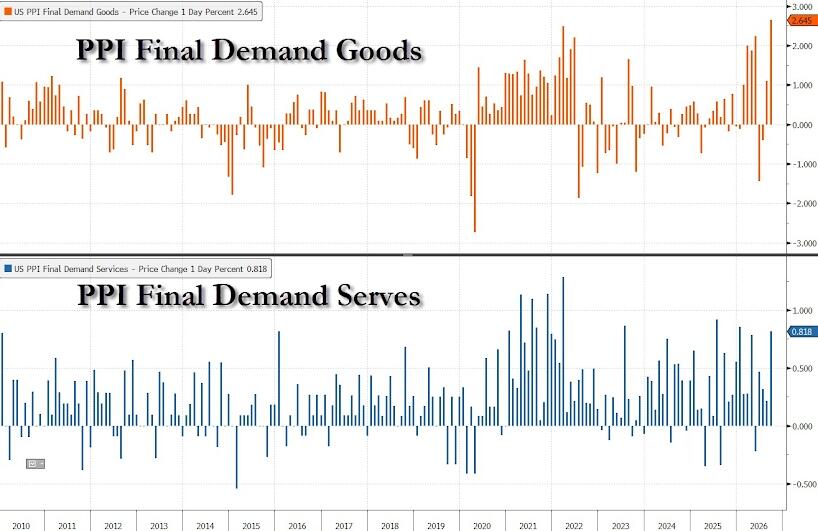
Final demand goods: Prices for final demand goods advanced 2.6%, in September, the largest increase since data were first calculated in December 2009. Over 80 percent of the broad-based rise in September is attributable to the index for final demand energy, which jumped 10.8 percent. Prices for final demand foods and for final demand goods less foods and energy advanced 1.2 percent and 0.3 percent, respectively.
Final demand services: Prices for final demand services moved up 0.8% in September, the largest rise since advancing 0.8% in April. Nearly half of the broad-based September increase can be attributed to a 1.4-percent rise in margins for final demand trade services. The indexes for final demand transportation and warehousing services and for final demand services less trade, transportation, and warehousing also advanced, 3.4 percent and 0.3 percent, respectively.
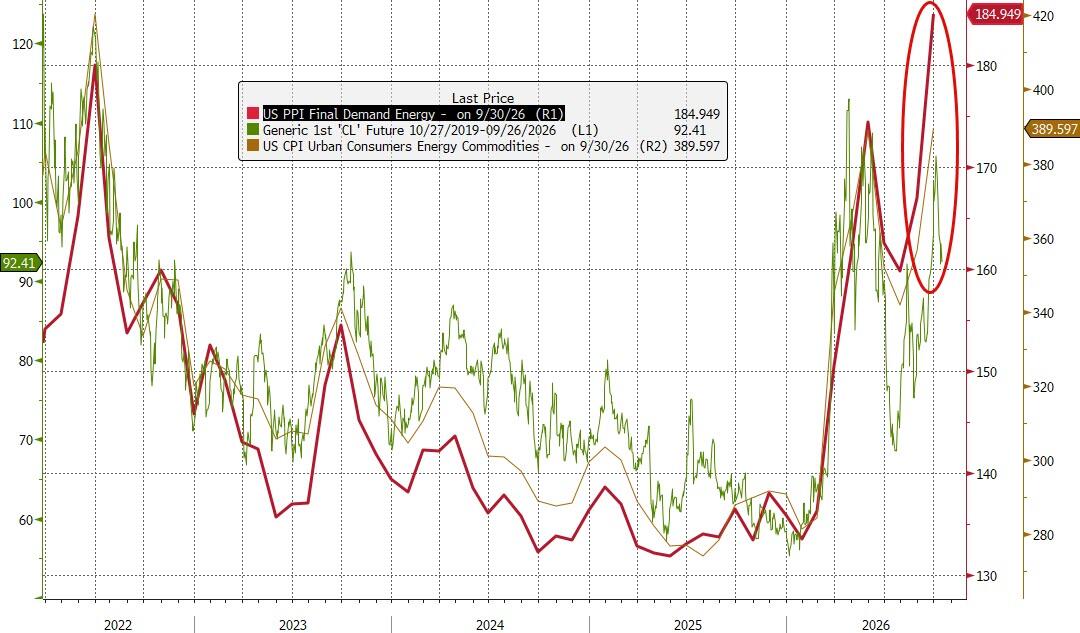
The Energy PPI component is now at a record high (clearly tracking diesel prices more than crude)...
Over 80 percent of the broad-based rise in September is attributable to the index for final demand energy, which jumped 10.8 percent
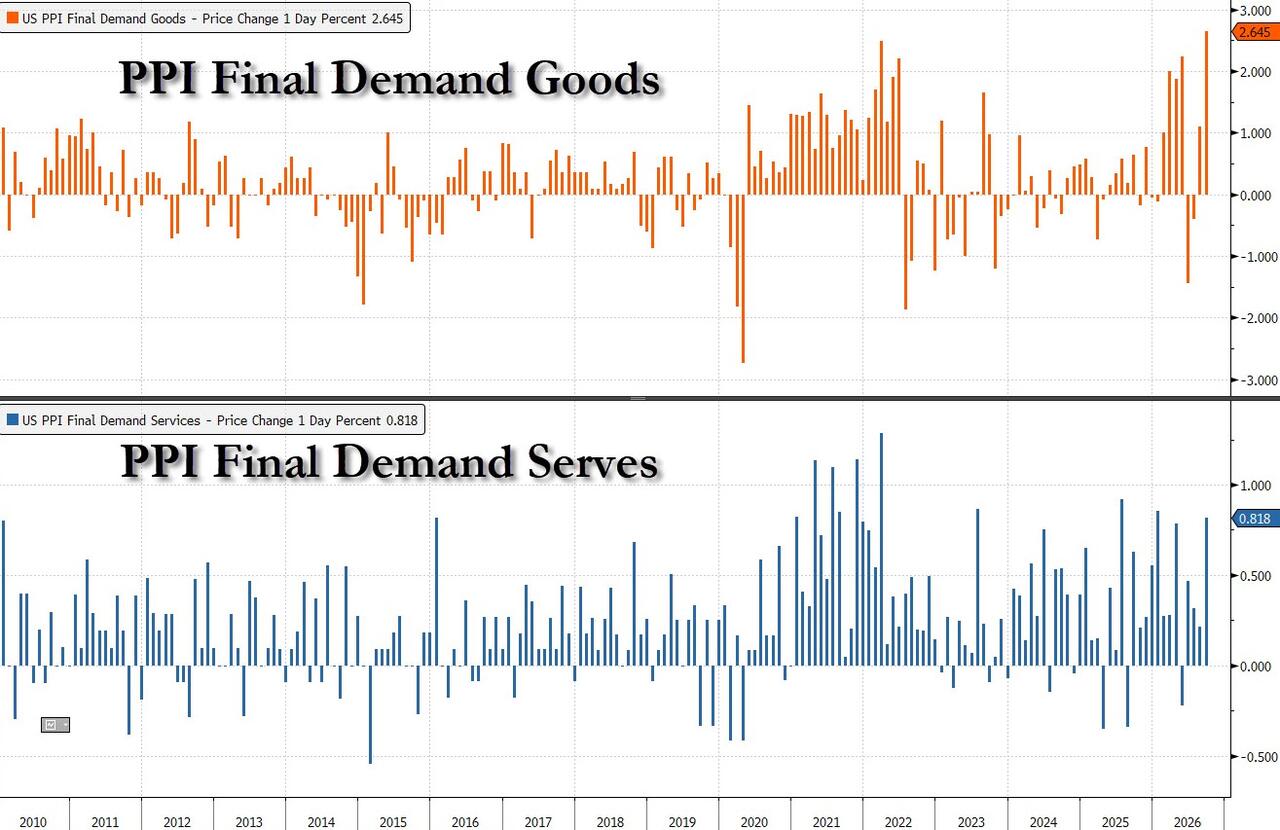
More problematically, Services costs are soaring too as energy costs spread across the economy...
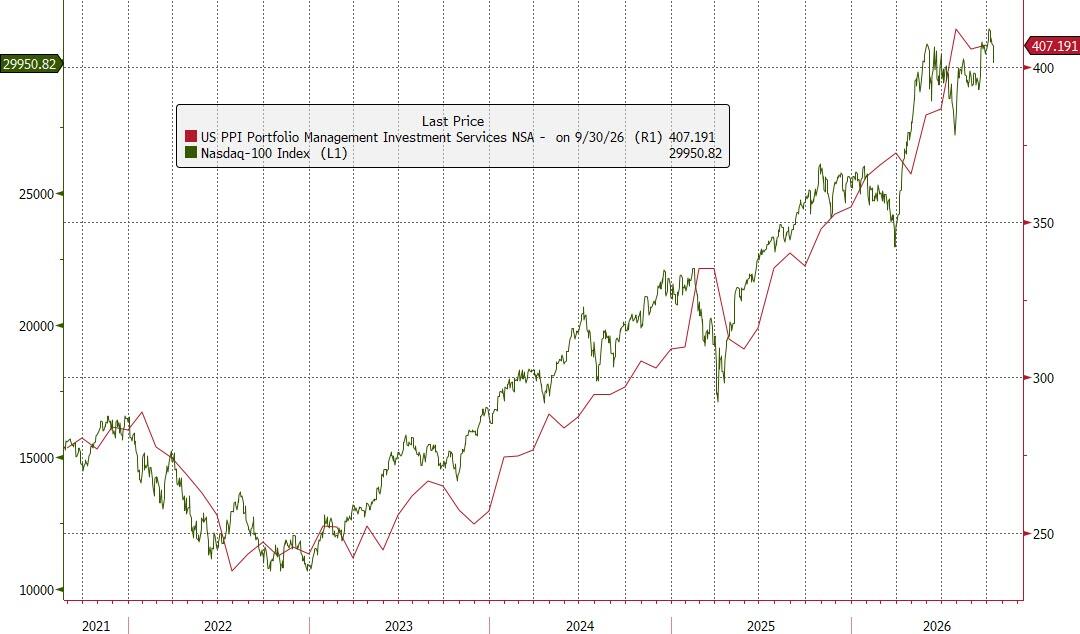
Portfolio management costs ticked up along with stocks yet again...
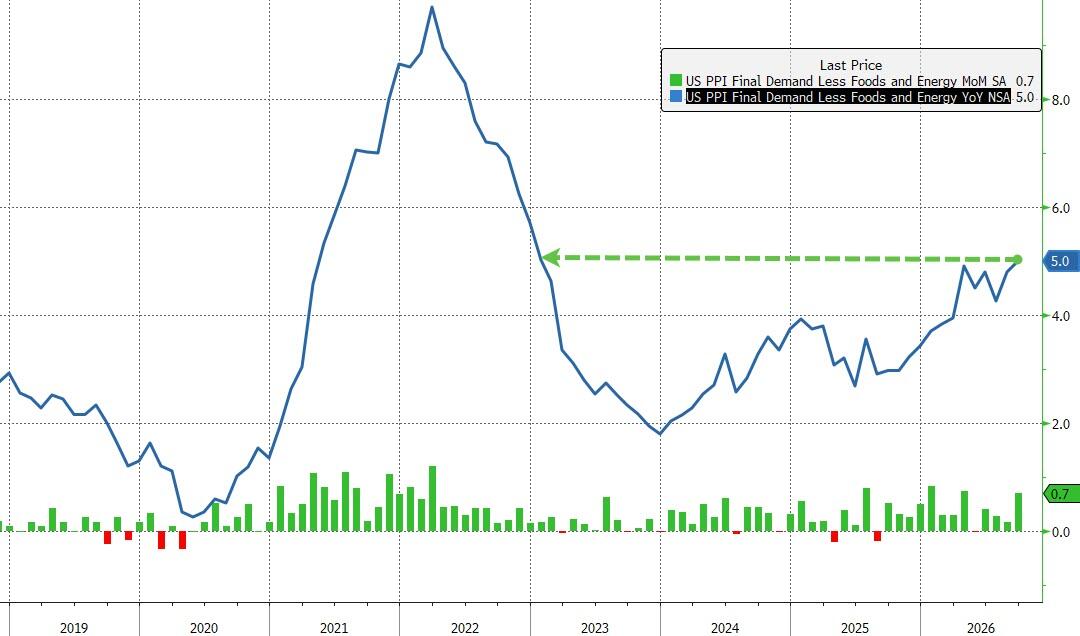
Core PPI was just as bad, rising 0.7% (more than double the 0.3% expected) and that pulled core Producer Prices up 5.0% YoY (the hottest since Dec 2022)...
Prices for final demand goods advanced 2.6%, in September, the largest increase since data were first calculated in December 2009' but Services costs are also jumping...
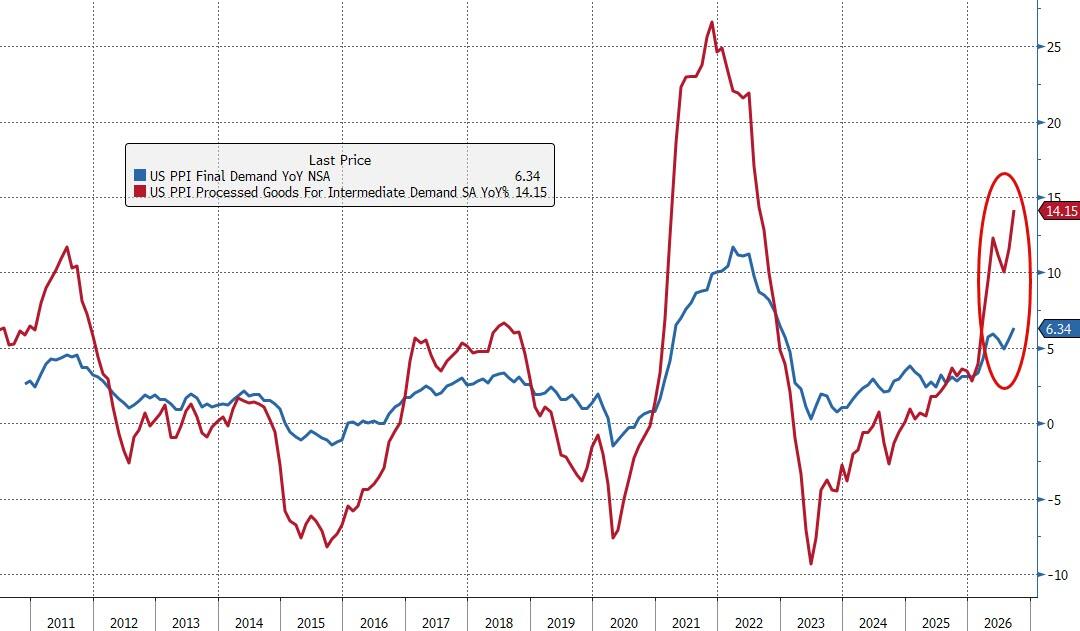
Worse still, the pipeline for future producer prices is ugly with intermediate demand prices surging...
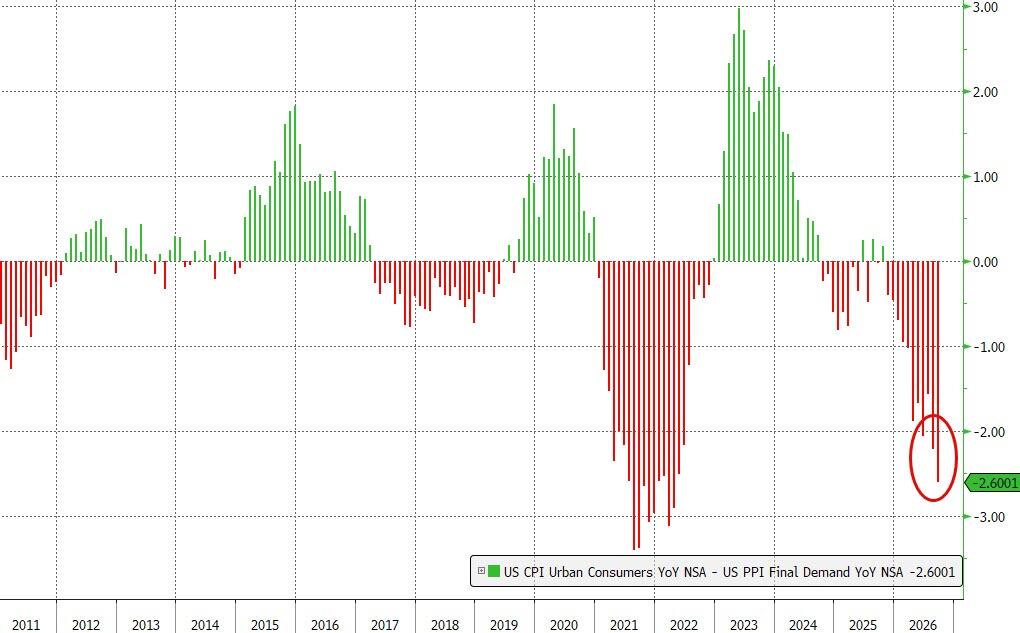
The CPI-PPI spread continues to (broadly speaking) signal increased pressure on corporate margins...
None of this provides any support for doves at The Fed and 2Y Yields and rate-hike odds are rising again, but not like they did post-CPI.
Tyler Durden Thu, 10/15/2026 - 08:43
Continue reading...
[ H/T ZeroHedge ]
After yesterday's accelerating CPI scare, this morning analysts expected a concomitant surge in producer prices - the big question remains whether it's all energy... or are price-hikes 'broadening out' making The Fed's job harder.
Headline PPI exploded higher in September, rising 1.3% MoM (more than double the 0.6% expected and biggest monthly jump since March 2022), dragging producer prices up 6.3% YoY (+5.4% exp) - the highest since Dec 2022...
Energy dominated the surge in prices...
Final demand goods: Prices for final demand goods advanced 2.6%, in September, the largest increase since data were first calculated in December 2009. Over 80 percent of the broad-based rise in September is attributable to the index for final demand energy, which jumped 10.8 percent. Prices for final demand foods and for final demand goods less foods and energy advanced 1.2 percent and 0.3 percent, respectively.
Final demand services: Prices for final demand services moved up 0.8% in September, the largest rise since advancing 0.8% in April. Nearly half of the broad-based September increase can be attributed to a 1.4-percent rise in margins for final demand trade services. The indexes for final demand transportation and warehousing services and for final demand services less trade, transportation, and warehousing also advanced, 3.4 percent and 0.3 percent, respectively.
The Energy PPI component is now at a record high (clearly tracking diesel prices more than crude)...
Over 80 percent of the broad-based rise in September is attributable to the index for final demand energy, which jumped 10.8 percent
Half of the September increase in the index for final demand goods can be traced to prices for gasoline, which jumped 20.3 percent.
The indexes for diesel fuel, fresh and dry vegetables, jet fuel, residential electric power, and crude petroleum also rose.
More problematically, Services costs are soaring too as energy costs spread across the economy...
Portfolio management costs ticked up along with stocks yet again...
Core PPI was just as bad, rising 0.7% (more than double the 0.3% expected) and that pulled core Producer Prices up 5.0% YoY (the hottest since Dec 2022)...
Prices for final demand goods advanced 2.6%, in September, the largest increase since data were first calculated in December 2009' but Services costs are also jumping...
Worse still, the pipeline for future producer prices is ugly with intermediate demand prices surging...
The CPI-PPI spread continues to (broadly speaking) signal increased pressure on corporate margins...
None of this provides any support for doves at The Fed and 2Y Yields and rate-hike odds are rising again, but not like they did post-CPI.
Tyler Durden Thu, 10/15/2026 - 08:43
Continue reading...
[ H/T ZeroHedge ]