




Guest Post by John Rubino
The following chart explains today’s “frozen” housing market.
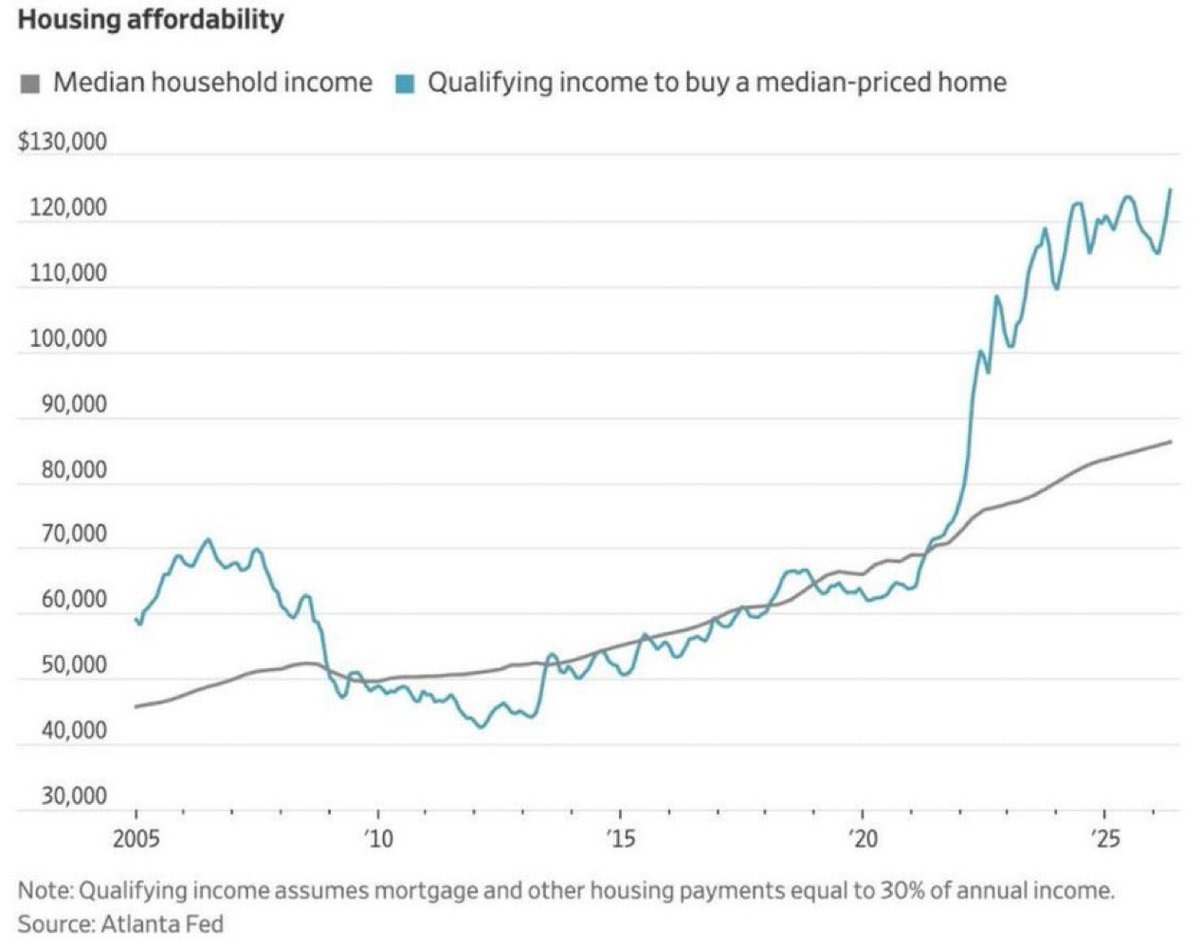
It also guarantees that at least one of three things will happen to restore balance in the sector.
Let’s consider each scenario:
Cutting today’s 7% mortgage rates in half would lower monthly payments to a tolerable level for many home buyers.
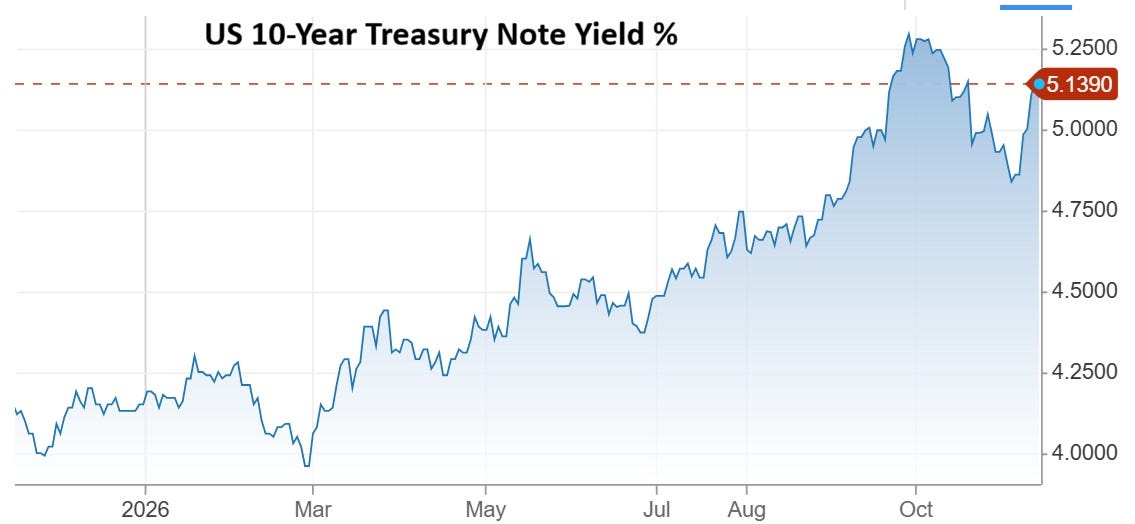
Is it likely? Well, mortgage rates key off of the yield on 10-year Treasury notes, which in turn key off of inflation expectations. With inflation now running at nearly twice the Fed’s target rate, the 10-year yield has been rising, not falling. So 7% mortgages are vastly more likely than 3% in the coming year.
Incomes, alas, are more likely to fall than rise in the next few years:
Now for a feasible number. A 30% drop would bring home prices more or less into line with the incomes required to buy them.
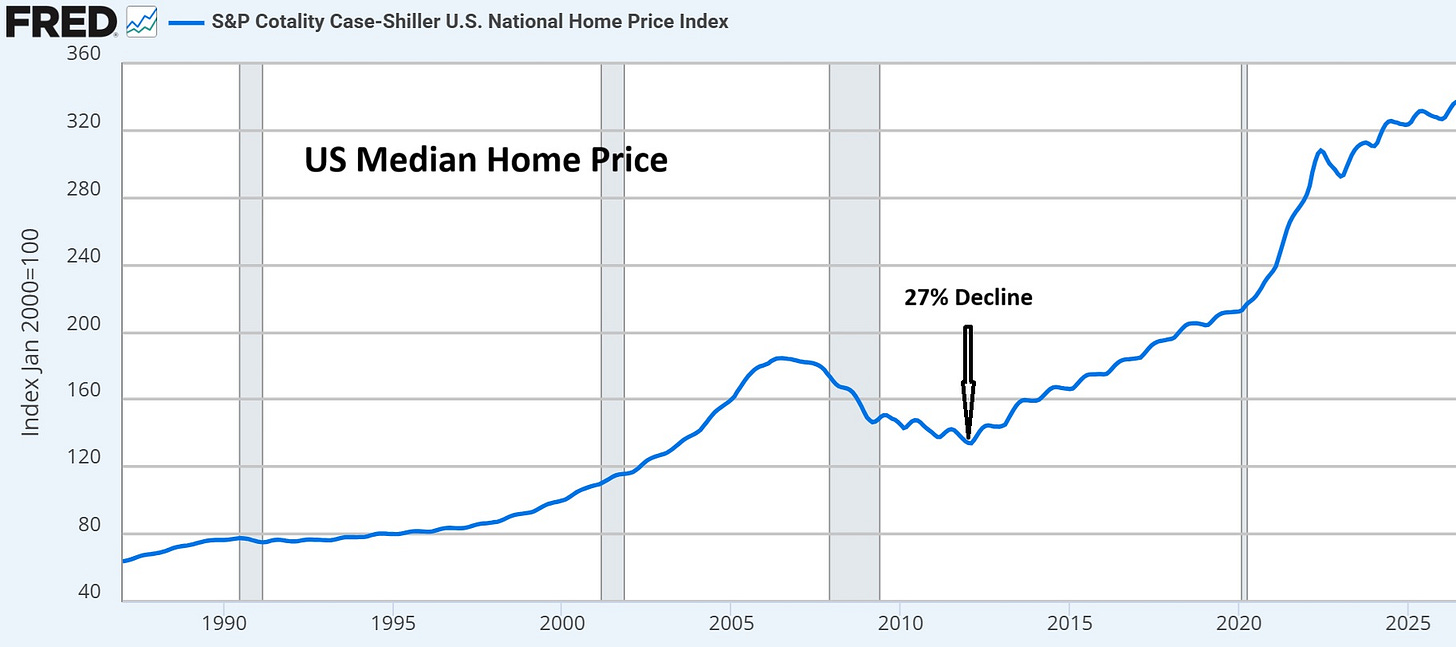
And there’s historical precedent for this kind of decline: During the previous decade’s housing bust, the Case-Shiller home price index fell by 27%.
But as with everything else in this inflationary decade, home prices are now at levels that make a 30% cut hard to imagine. On a $500,000 house (typical in today’s middle-class neighborhoods), 30% equals $150,000 off the asking price, something for which today’s sellers are not prepared.
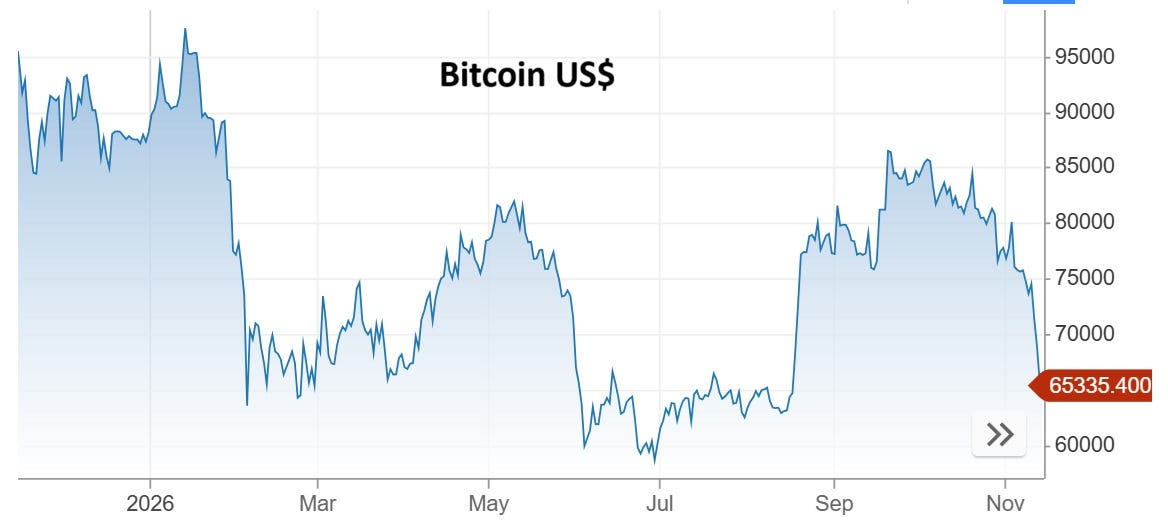
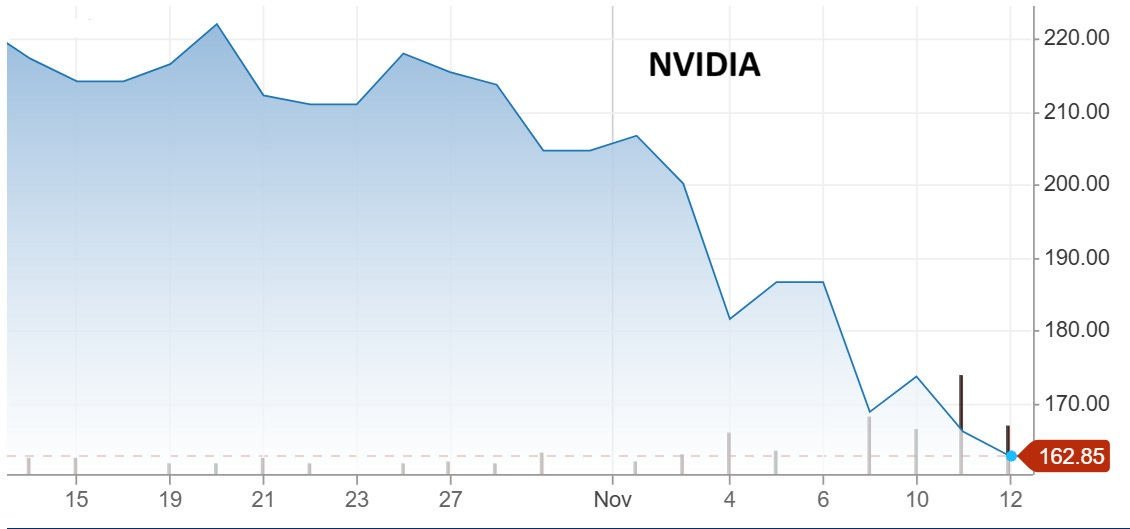
Getting from here to there will feel like a crisis. But it might happen surprisingly fast. Consider Bitcoin this year and NVIDIA this month:
Whether what’s coming is good or bad depends on whether you’re a buyer or a seller. So, useful aphorisms for each:
Patience is bitter, but its fruit is sweet — Jean‑Jacques Rousseau
He who panics first, panics bestt — anonymous
Tweet
Continue reading...
[ H/T The Burning Platform ]
The following chart explains today’s “frozen” housing market.
It also guarantees that at least one of three things will happen to restore balance in the sector.
- Mortgage interest rates fall to 3%
- Household incomes rise by 40%
- Home prices fall by 30%
Let’s consider each scenario:
3% Mortgages
Cutting today’s 7% mortgage rates in half would lower monthly payments to a tolerable level for many home buyers.
Is it likely? Well, mortgage rates key off of the yield on 10-year Treasury notes, which in turn key off of inflation expectations. With inflation now running at nearly twice the Fed’s target rate, the 10-year yield has been rising, not falling. So 7% mortgages are vastly more likely than 3% in the coming year.
40% Higher Household Incomes
Incomes, alas, are more likely to fall than rise in the next few years:
30% Lower Home Prices
Now for a feasible number. A 30% drop would bring home prices more or less into line with the incomes required to buy them.
And there’s historical precedent for this kind of decline: During the previous decade’s housing bust, the Case-Shiller home price index fell by 27%.
But as with everything else in this inflationary decade, home prices are now at levels that make a 30% cut hard to imagine. On a $500,000 house (typical in today’s middle-class neighborhoods), 30% equals $150,000 off the asking price, something for which today’s sellers are not prepared.
Getting from here to there will feel like a crisis. But it might happen surprisingly fast. Consider Bitcoin this year and NVIDIA this month:
Whether what’s coming is good or bad depends on whether you’re a buyer or a seller. So, useful aphorisms for each:
Patience is bitter, but its fruit is sweet — Jean‑Jacques Rousseau
He who panics first, panics bestt — anonymous
Tweet
Continue reading...
[ H/T The Burning Platform ]