


"Every Chart, Every Asset": Goldman's Privorotsky Says The Rotation Is Now Outright Liquidation As Financial Conditions
Thursday was supposed to be the day the AI trade got its groove back.
Nvidia had beaten and raised even without Jensen, Anthropic had priced the biggest IPO in history at $83, and hedge funds were sitting 11 points underweight tech, which is why Goldman's Rich Privorotsky told clients in his Thursday morning note that "today feels important" and that it "doesn't take much good news to squeeze." Instead, the S&P swung from a gain of more than 1% to a 2% loss, its sixth straight decline and longest losing streak since April 2024, and closed on its lows, back below its 200-day moving average. Only 38 S&P constituents went up. 464 went down.
So what went wrong? In his Friday morning note ("China Restrictions. 2018 Playbook. FCI Tight.", available to pro subs), Goldman's head of EMEA Delta One trading admits he got blindsided too:
Those "few things" turn out to be: a far more aggressive China chip regime, a Fed that wants to "shock" people, and real yields sitting near their highs just as breakevens collapse. Put them together and Privorotsky sees a familiar movie, and readers who were around in late 2018 will remember how that one went before the happy ending.
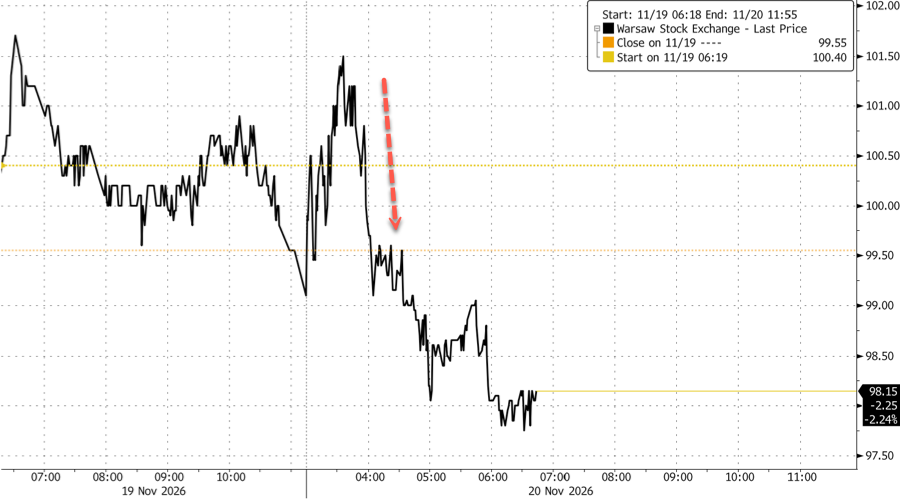
Start with the micro. Regular readers know that on Monday Washington closed the "cloud loophole", putting AI chip rentals to Chinese companies (and shipments to five "diversion" hubs including Singapore and Malaysia) under license. We flagged the headline in real time:
The rule took effect on Thursday, the same day the S&P puked, and Privorotsky thinks the market is only now grasping how big it is:
The important nuance: Privorotsky's most immediate worry is the uncertainty, with permanently lost Chinese demand further down the list. Nobody knows who is allowed to buy what, and under which licensing regime, which in his words is "potentially enough to freeze incremental investment decisions." That freeze, he argues, partly explains why the Asian data center trade has been "so acutely weak", alongside broader China weakness and a Shanghai market testing its lows, with knock-on effects for copper and gold. On Thursday morning he had already warned the rule was "clearly not fully priced in Asia"; the first domino had in fact fallen days earlier.
And the chip curbs only stack on top of the four things that were already crushing AI multiples, which Privorotsky lists as a) cost of capital (further challenged by the change of leadership at NVDA), b) DC restrictions, c) oversupply/efficiency unlocks for inference and d) lack of revenue to support capex. Point (a) is one we have been pounding the table on since October 2025, when AI quietly overtook the banks to become the largest debt sector in the market. Point (d), well... the market just valued a model lab at $2 trillion on its opening print, so maybe that one is still a work in progress.
The technical damage was, to use the trader's own phrase, comprehensive:
The negative gamma part should surprise nobody: Nomura's Charlie McElligott warned this week that dealers were the most short gamma since 2019 heading into the NVDA-Anthropic-opex pileup, and on Tuesday the S&P had already slipped under its 200DMA for the first time since April. Much of that short gamma was tied to today's monthly expiration, which is why the afternoon leg lower looked the way it did:
What really bothers Privorotsky, however, is what didn't work:
Indeed, all 11 S&P sectors finished red on Thursday, with health care and staples leading the declines. In other words, when even the staples can't hide you, nobody is rotating anymore: they are raising cash. Which, incidentally, is exactly what desk chatter had suggested all week: a chunk of the gold, crypto, copper and Nvidia selling was about funding the Anthropic allocation, a deal that raised $81.3 billion ($107.3 billion with the vendor placement). The IPO got its money. Everything else got the bill. Gold slid below $3,700 for the first time since September 2025 and copper dropped about 5%, prompting this observation:
And as we noted earlier this morning, even the record day-one retail crowd in Anthropic was nearly half sellers.
Then there is the macro, and this is where the 2018 comparison comes in. Waller's 50bp talk "certainly helped shock the market" (shocking people being, after all, the stated goal), and a "litany" of mostly hawkish Fed speakers did the rest, on top of minutes showing almost the entire FOMC sees more hikes. The result, per Privorotsky, is that "financial conditions have tightened extraordinarily quickly." He attached the chart to prove it:
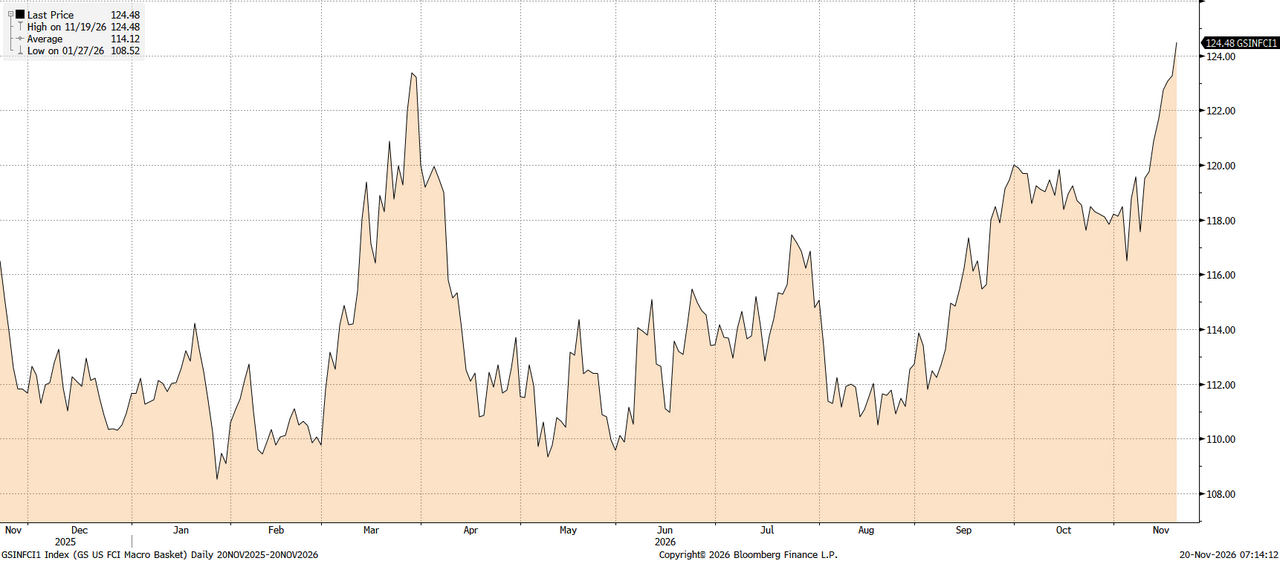
Goldman's US FCI macro basket closed Thursday at 124.48, the highest reading of the past year, above even the March spike. It was roughly 116.5 in early November (chart read, approximate), so call it 8 points of tightening in about two weeks, most of it straight up. If the Fed was hoping markets would do some of the tightening for it, markets have very much obliged.
Here is the core of the note:
For those who need the refresher: in late 2018 the Powell Fed kept hiking and insisted balance sheet runoff was on autopilot, the S&P fell roughly 20% from its September peak to Christmas Eve, and by January 4 Powell was promising to be "patient." Privorotsky had already flagged "a lot of parallels to end of 2018" in the bond market on Thursday morning; one ugly session later, the analogy has gone from footnote to headline. Goldman isn't alone either: BTIG's Jonathan Krinsky noted that in the past 30 years, a six-day S&P losing streak ending below the 200DMA (but by no more than 3%) has happened just three times: 9/27/00, 10/11/18 and 2/27/20. All three were higher five days later. All three then saw meaningful downside. Not exactly a list you want to be on.
The twist this time is that the bond market may already be calling the mistake:
Put differently, the Fed is still fighting last quarter's war. Rates traders aren't buying it, equity traders are panicking, and Goldman's own economists still expect 25bps in December and a third hike in March 2027. Somebody here is going to be very wrong, and probably very soon.
So what do you do with all this? Privorotsky concedes there may have been "some forced funding or liquidation that won't repeat," but he isn't hiding behind it:
That squares with the "long front-end bonds alongside equities" trade he laid out on Wednesday, though the equity leg has clearly had a rough 48 hours. He also wants gold watched as a "coincidental indicator" alongside stocks, since its selloff looks like a "clear liquidation/reaction to real rates/FCI."
As for a bottom, the contrarian case is there, for what it's worth: "the sheer depth of current pessimism and one sided de-grossing suggests the market may be approaching a tactical local low." The catch is that there's not much on the calendar to trigger one: PCE next Wednesday, then payrolls and the December FOMC. Privorotsky thinks November CPI is the print that matters, "potentially the one that forces a recalibration from the Fed", but it is far enough away that it "probably won't register just yet."
Last week we noted that it would take a "marketwide gamma squeeze or the ANT IPO" to get things moving. We got the IPO. The squeeze didn't survive the morning.
Our take: the tactical low may well be close, and with funds this underweight a bounce could be violent. But the 2018 playbook had a crucial second act, the Powell pivot, and nobody at the Warsh Fed is reading from that page yet. Until someone does, every rally is probably one to sell into, and the bond market, which tends to figure these things out first, is already pricing the ending. Back in 2018 stocks didn't bottom until Christmas Eve. With December FOMC on the 9th and CPI not long after, we may not have to wait quite that long... or we may get a December that rhymes uncomfortably well.
Much more in the full Privorotsky note and his Thursday "Pivotal" note, both available to pro subs.
Tyler Durden Fri, 11/20/2026 - 08:00
Continue reading...
[ H/T ZeroHedge ]
Thursday was supposed to be the day the AI trade got its groove back.
Nvidia had beaten and raised even without Jensen, Anthropic had priced the biggest IPO in history at $83, and hedge funds were sitting 11 points underweight tech, which is why Goldman's Rich Privorotsky told clients in his Thursday morning note that "today feels important" and that it "doesn't take much good news to squeeze." Instead, the S&P swung from a gain of more than 1% to a 2% loss, its sixth straight decline and longest losing streak since April 2024, and closed on its lows, back below its 200-day moving average. Only 38 S&P constituents went up. 464 went down.
So what went wrong? In his Friday morning note ("China Restrictions. 2018 Playbook. FCI Tight.", available to pro subs), Goldman's head of EMEA Delta One trading admits he got blindsided too:
Those "few things" turn out to be: a far more aggressive China chip regime, a Fed that wants to "shock" people, and real yields sitting near their highs just as breakevens collapse. Put them together and Privorotsky sees a familiar movie, and readers who were around in late 2018 will remember how that one went before the happy ending.
Three Fronts, One Freeze
Start with the micro. Regular readers know that on Monday Washington closed the "cloud loophole", putting AI chip rentals to Chinese companies (and shipments to five "diversion" hubs including Singapore and Malaysia) under license. We flagged the headline in real time:
The rule took effect on Thursday, the same day the S&P puked, and Privorotsky thinks the market is only now grasping how big it is:
The important nuance: Privorotsky's most immediate worry is the uncertainty, with permanently lost Chinese demand further down the list. Nobody knows who is allowed to buy what, and under which licensing regime, which in his words is "potentially enough to freeze incremental investment decisions." That freeze, he argues, partly explains why the Asian data center trade has been "so acutely weak", alongside broader China weakness and a Shanghai market testing its lows, with knock-on effects for copper and gold. On Thursday morning he had already warned the rule was "clearly not fully priced in Asia"; the first domino had in fact fallen days earlier.
And the chip curbs only stack on top of the four things that were already crushing AI multiples, which Privorotsky lists as a) cost of capital (further challenged by the change of leadership at NVDA), b) DC restrictions, c) oversupply/efficiency unlocks for inference and d) lack of revenue to support capex. Point (a) is one we have been pounding the table on since October 2025, when AI quietly overtook the banks to become the largest debt sector in the market. Point (d), well... the market just valued a model lab at $2 trillion on its opening print, so maybe that one is still a work in progress.
"Broke Just About Every Level Possible"
The technical damage was, to use the trader's own phrase, comprehensive:
The negative gamma part should surprise nobody: Nomura's Charlie McElligott warned this week that dealers were the most short gamma since 2019 heading into the NVDA-Anthropic-opex pileup, and on Tuesday the S&P had already slipped under its 200DMA for the first time since April. Much of that short gamma was tied to today's monthly expiration, which is why the afternoon leg lower looked the way it did:
What really bothers Privorotsky, however, is what didn't work:
Indeed, all 11 S&P sectors finished red on Thursday, with health care and staples leading the declines. In other words, when even the staples can't hide you, nobody is rotating anymore: they are raising cash. Which, incidentally, is exactly what desk chatter had suggested all week: a chunk of the gold, crypto, copper and Nvidia selling was about funding the Anthropic allocation, a deal that raised $81.3 billion ($107.3 billion with the vendor placement). The IPO got its money. Everything else got the bill. Gold slid below $3,700 for the first time since September 2025 and copper dropped about 5%, prompting this observation:
And as we noted earlier this morning, even the record day-one retail crowd in Anthropic was nearly half sellers.
The FCI Chart
Then there is the macro, and this is where the 2018 comparison comes in. Waller's 50bp talk "certainly helped shock the market" (shocking people being, after all, the stated goal), and a "litany" of mostly hawkish Fed speakers did the rest, on top of minutes showing almost the entire FOMC sees more hikes. The result, per Privorotsky, is that "financial conditions have tightened extraordinarily quickly." He attached the chart to prove it:
Goldman's US FCI macro basket closed Thursday at 124.48, the highest reading of the past year, above even the March spike. It was roughly 116.5 in early November (chart read, approximate), so call it 8 points of tightening in about two weeks, most of it straight up. If the Fed was hoping markets would do some of the tightening for it, markets have very much obliged.
Waller's Rear-View Mirror
Here is the core of the note:
For those who need the refresher: in late 2018 the Powell Fed kept hiking and insisted balance sheet runoff was on autopilot, the S&P fell roughly 20% from its September peak to Christmas Eve, and by January 4 Powell was promising to be "patient." Privorotsky had already flagged "a lot of parallels to end of 2018" in the bond market on Thursday morning; one ugly session later, the analogy has gone from footnote to headline. Goldman isn't alone either: BTIG's Jonathan Krinsky noted that in the past 30 years, a six-day S&P losing streak ending below the 200DMA (but by no more than 3%) has happened just three times: 9/27/00, 10/11/18 and 2/27/20. All three were higher five days later. All three then saw meaningful downside. Not exactly a list you want to be on.
The twist this time is that the bond market may already be calling the mistake:
Put differently, the Fed is still fighting last quarter's war. Rates traders aren't buying it, equity traders are panicking, and Goldman's own economists still expect 25bps in December and a third hike in March 2027. Somebody here is going to be very wrong, and probably very soon.
When Does The Fed Blink?
So what do you do with all this? Privorotsky concedes there may have been "some forced funding or liquidation that won't repeat," but he isn't hiding behind it:
That squares with the "long front-end bonds alongside equities" trade he laid out on Wednesday, though the equity leg has clearly had a rough 48 hours. He also wants gold watched as a "coincidental indicator" alongside stocks, since its selloff looks like a "clear liquidation/reaction to real rates/FCI."
As for a bottom, the contrarian case is there, for what it's worth: "the sheer depth of current pessimism and one sided de-grossing suggests the market may be approaching a tactical local low." The catch is that there's not much on the calendar to trigger one: PCE next Wednesday, then payrolls and the December FOMC. Privorotsky thinks November CPI is the print that matters, "potentially the one that forces a recalibration from the Fed", but it is far enough away that it "probably won't register just yet."
Last week we noted that it would take a "marketwide gamma squeeze or the ANT IPO" to get things moving. We got the IPO. The squeeze didn't survive the morning.
Our take: the tactical low may well be close, and with funds this underweight a bounce could be violent. But the 2018 playbook had a crucial second act, the Powell pivot, and nobody at the Warsh Fed is reading from that page yet. Until someone does, every rally is probably one to sell into, and the bond market, which tends to figure these things out first, is already pricing the ending. Back in 2018 stocks didn't bottom until Christmas Eve. With December FOMC on the 9th and CPI not long after, we may not have to wait quite that long... or we may get a December that rhymes uncomfortably well.
Much more in the full Privorotsky note and his Thursday "Pivotal" note, both available to pro subs.
Tyler Durden Fri, 11/20/2026 - 08:00
Continue reading...
[ H/T ZeroHedge ]