

Anthropic Says Q3 Revenue Jumped To $16.8 Billion And Turned "Adjusted" Profitable... But Run-Rate Math Shows Growth Hitting The Brakes
We got the number.
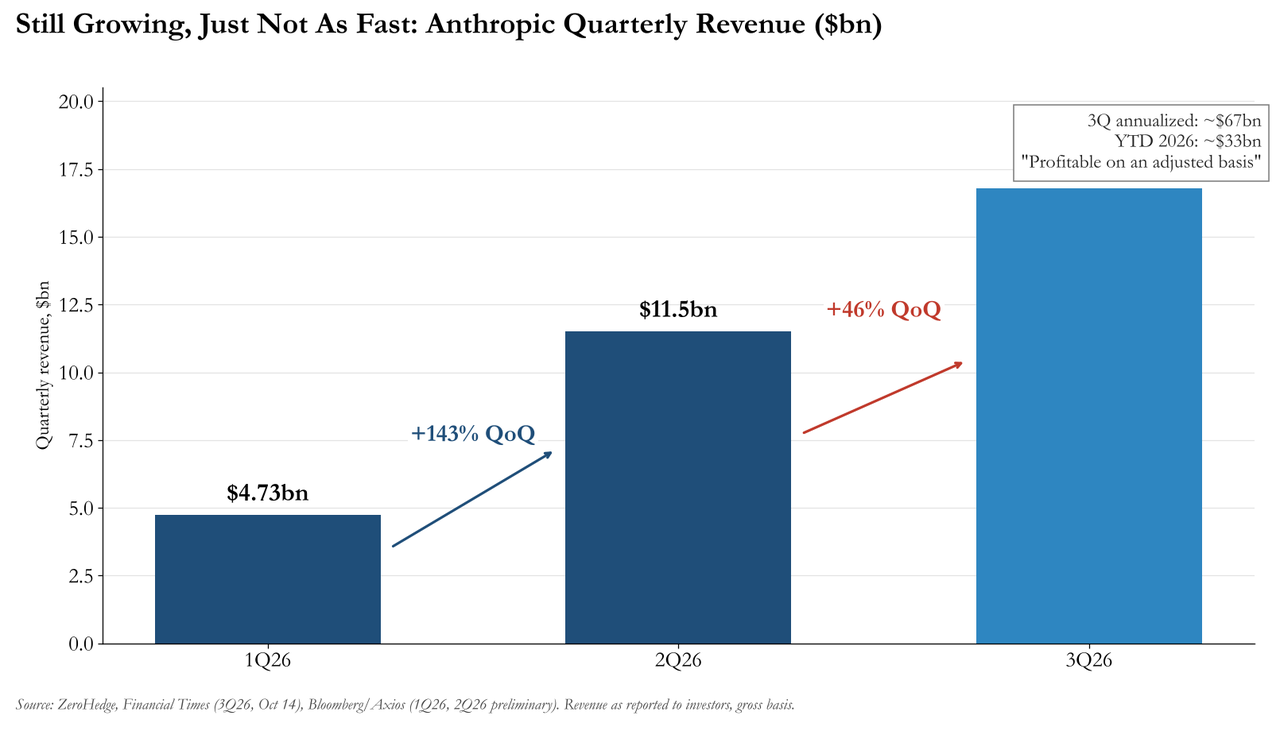
As we previewed this morning, the entire AI complex (if not the entire market) spent Wednesday waiting with bated breath for one data point out of Anthropic's closed-door pre-IPO investor day in San Francisco. Shortly after the close, the FT delivered: Anthropic told investors its third-quarter revenue had jumped to $16.8 billion, "almost 50 per cent" above the $11.5 billion recorded in the second quarter, and that the company was "profitable on an adjusted basis" and cash flow positive in the quarter.
Executives spent the full day laying out how "a safety-focused philosophy, rapid growth and efficiency gains" would set up a successful IPO in November.
On the surface, that is close to the "position of strength" JonesTrading's Mike O'Rourke said the market was looking for. And the timing could hardly be better for the bulls, because the AI trade spent the entire session before the headline getting taken to the woodshed.
Goldman's US trading desk titled its close "UGLY" (available to pro subs): the S&P fell 1.11% to 7,719 and the NDX slid 2.02% to 29,950, the "first -1% SPX / -2% NDX move since late July," with "sentiment particularly within the AI complex taking a real step function lower" on:
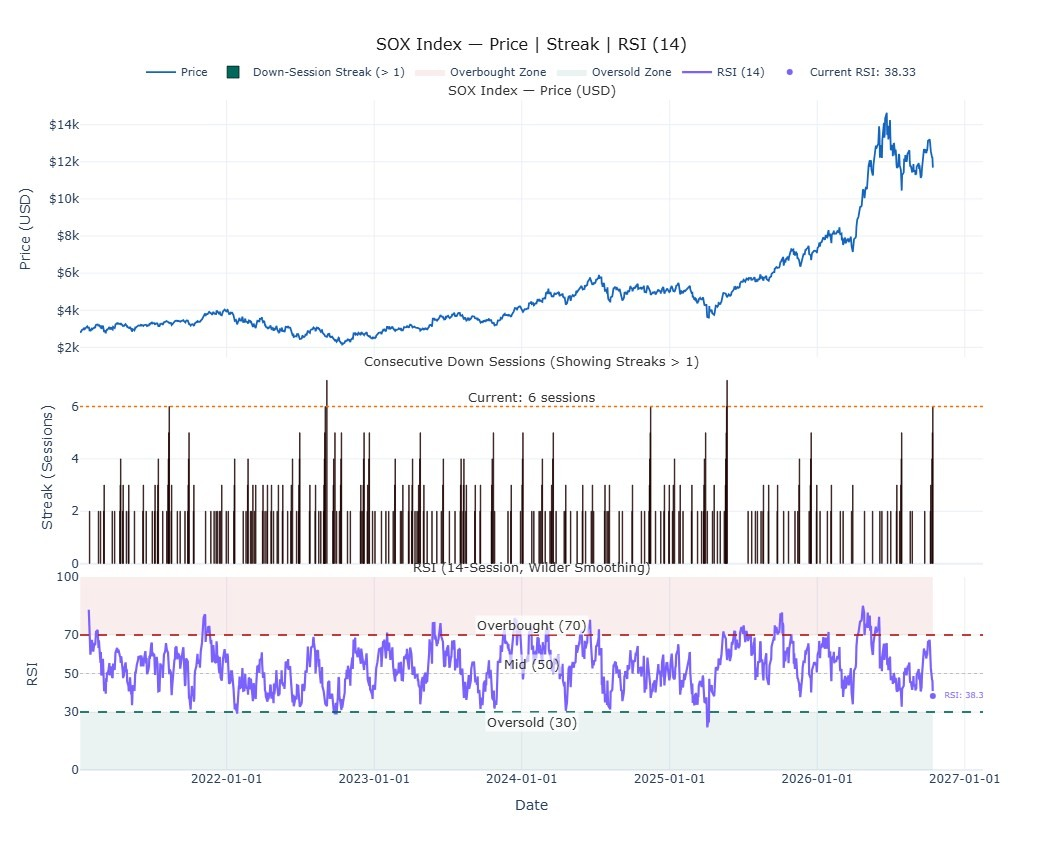
The credit side was worse. Goldman's cross-asset desk reported "macro credit spreads widening the most in a single session in months," with Oracle CDS +31bps on the day, CoreWeave CDS exploding over 100 bps wider, hyperscaler cash bonds 4-5bps wider and datacenters 7bps wider. CoreWeave stock lost more than 15% (and almost 20% including the after hours dump), and as we noted in today's market wrap, the CDS market now assigns a 63% chance it defaults within five years. Semis meanwhile closed down for a sixth straight session, a streak Goldman's Matthew Kaplan flagged as uncommon:
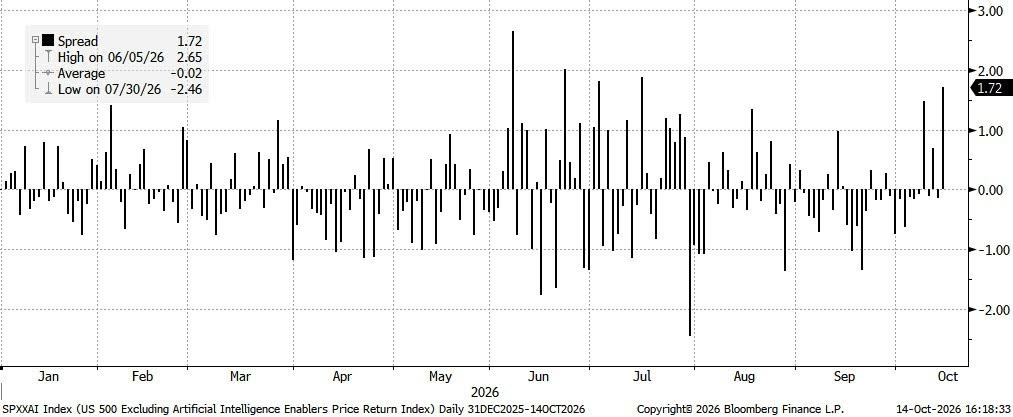
Meanwhile, as everything AI got dumped, Goldman's S&P ex-AI basket rose 61bps, a 1.72-point spread over the index that ranks among the top five of the year:
In other words, the market spent the day cutting the "right tail off of the AI trade", in the words of Goldman's derivatives desk, and then Anthropic's number crossed after the close. The only question that matters now is whether the number reattaches that tail.
Start with the obvious. Annualize the quarter and you get about $67 billion, barely above the $65 billion run rate Anthropic told investors it had hit at the end of July. But Anthropic's run rate annualizes the most recent month, so the real question is where the company exited September, and that takes a little arithmetic.
Anchor on July, a process which the company is known to do by annualizing its latest (and greatest) month. Read the $65 billion end-July mark as July revenue × 12 and July comes to about $5.4 billion. That leaves roughly $11.4 billion for August and September combined ($16.8 billion − $5.4 billion), which fits steady growth of just ~3.4% a month: about $5.6 billion in August and $5.8 billion in September, or a September run rate of ~$69-70 billion.
The more generous reading treats $65 billion as the pace on July 31 rather than July's average. In that case July revenue was lower (closer to $5.2 billion, since it was still ramping), more of the quarter lands in August and September, and the implied growth rate rises to ~6.6% a month. September revenue × 12 still comes to only ~$71 billion, but the exit pace on Sep 30 works out to about $74 billion.
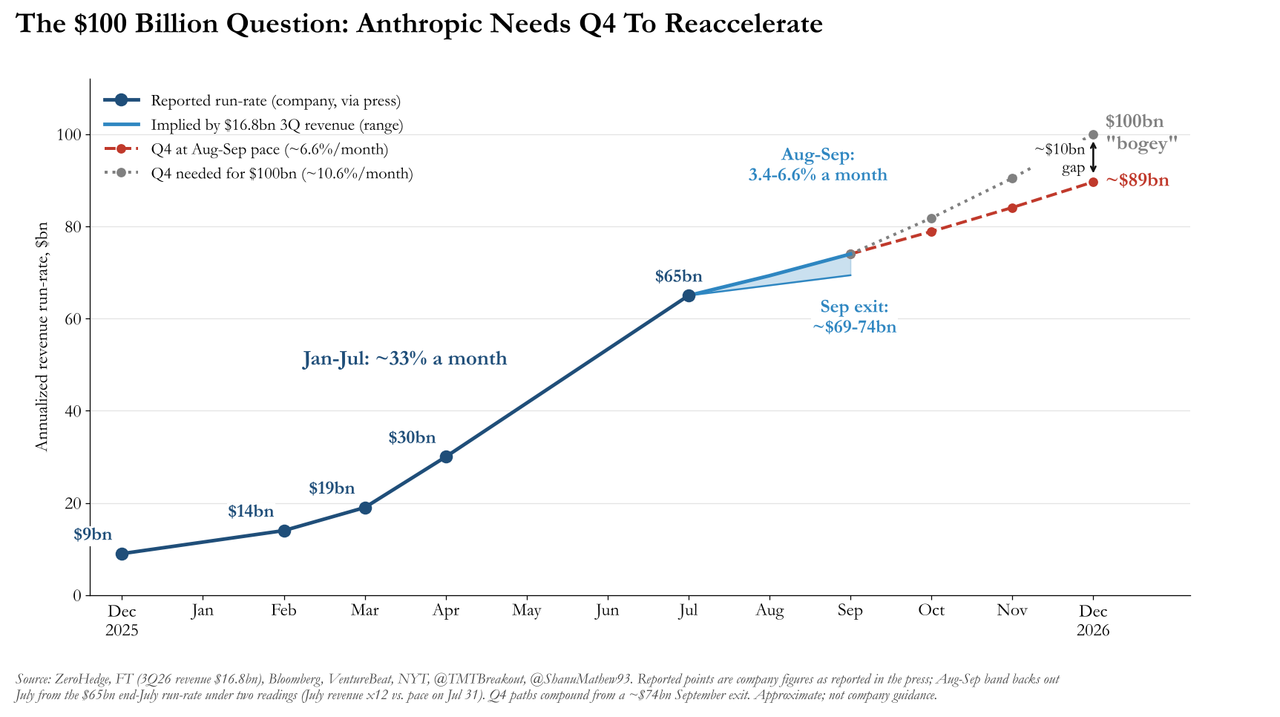
Either way, Anthropic exited the third quarter at somewhere between $69 billion and $74 billion, which is what TMT Breakout also calculated shortly after the FT headline. Now project it forward from the generous end of the range. At the same ~6.6% a month, the run rate reaches ~$89 billion by December. Hitting the $100 billion year-end bogey requires about 10.6% a month in Q4 from $74 billion, or 12.6% from $70 billion. That's the same conclusion Shanu Mathew reached: growth has decelerated, and the $100 billion target now needs Q4 to reaccelerate.
Incidentally, that is what the latest token data from Ramp AI shows: while AI usage is rapidly rising (per Jevon's Paradox), AI spend is actually flat at best, if not shrinking...
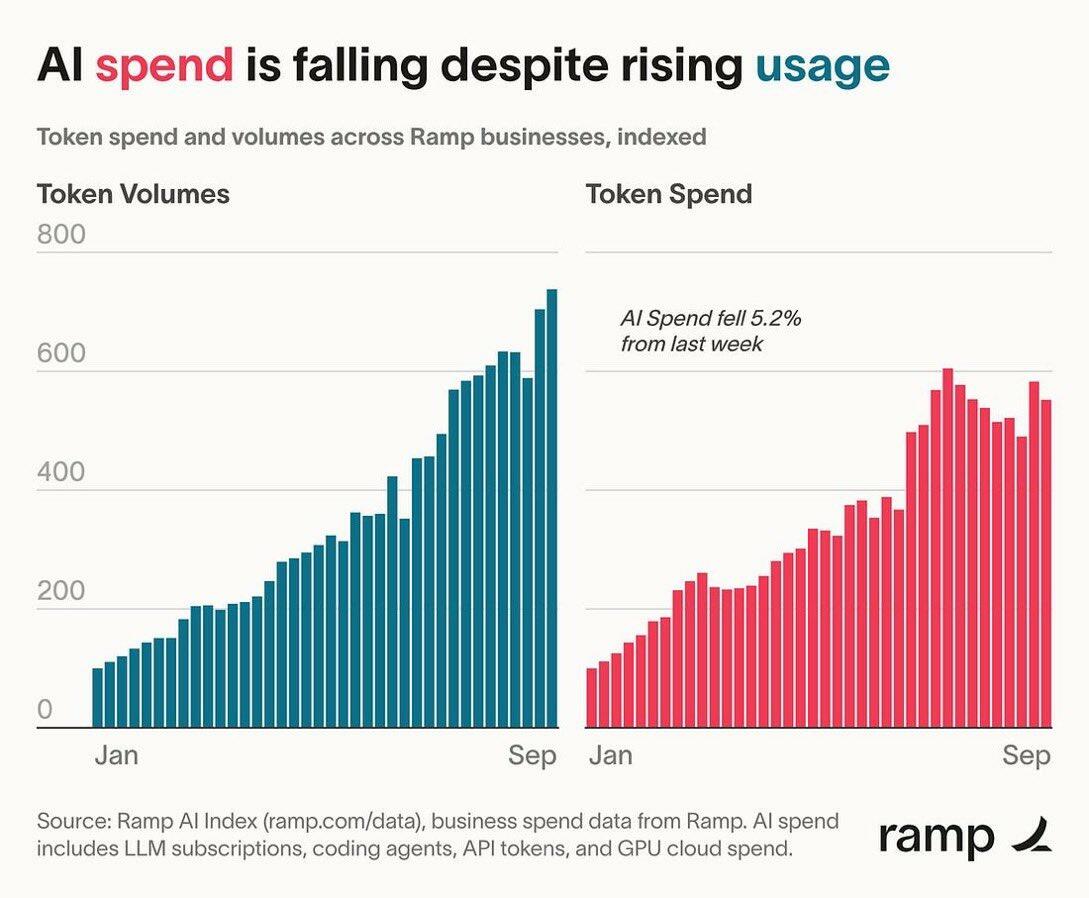
... as a result of tumbling token prices thanks to growing market share by open-source models; in fact as we showed earlier, token prices at Anthropic just hit an all time low suggesting that the price is dropping faster than the the company can convert higher volumes into revenue.
Put it all on one chart and the problem is plain to see: the line that went near-vertical through July on the initial burst of agentic euphoria and Tokenmaxxing has flattened, and the $100 billion IPO bogey sits about $10 billion above where the Aug-Sep pace gets you by December.
Here is the same deceleration in quarterly terms:
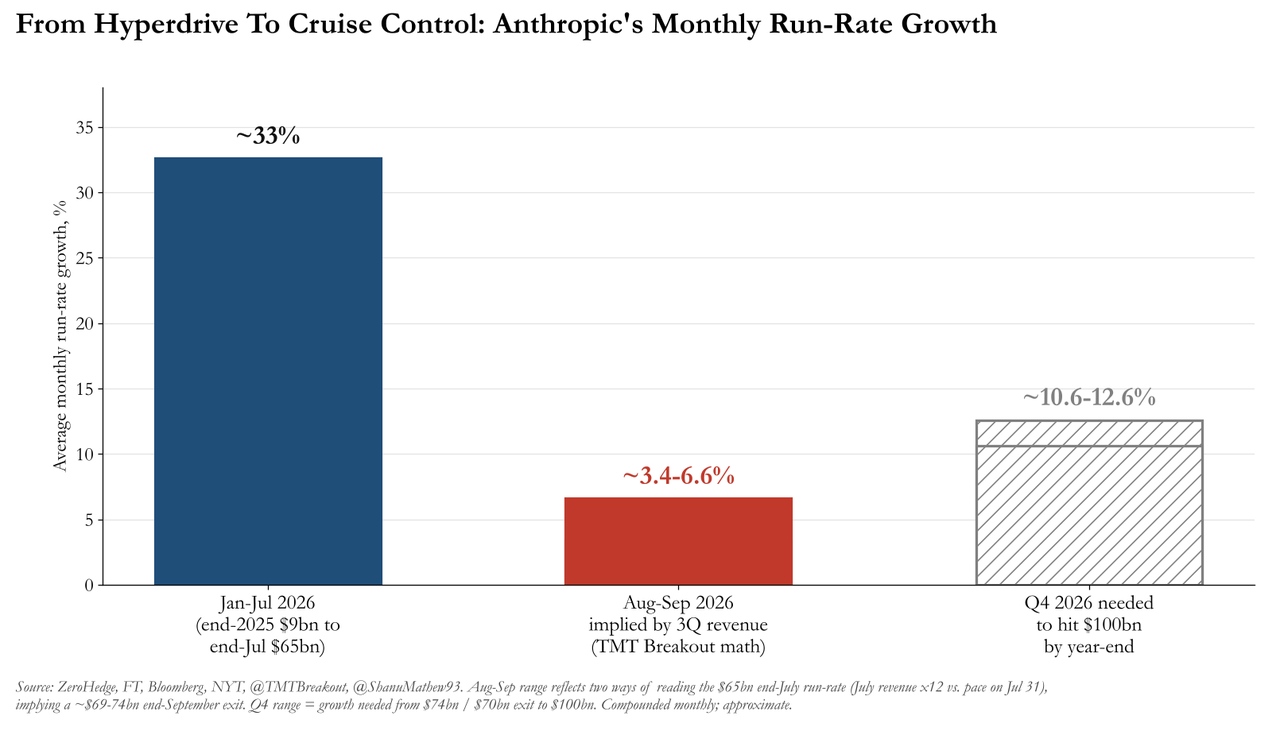
And here it is in monthly terms, which is where it really jumps out. Going from $9 billion at the end of 2025 to $65 billion at the end of July works out to roughly 33% compounded growth per month. Over August and September, the implied pace fell to 3.4%-6.6%. To reach the "more than $100 billion" year-end figure the NYT reported last month, Anthropic now needs ~10.6%-12.6% a month in Q4, depending on whether it exited at $74 billion or $70 billion:
To be clear, 46% sequential growth on a $46 billion base (Q2 annualized) is extraordinary by the standards of any company that has ever existed. The issue is the bar, which Anthropic itself set: going into the meeting, much of the Street had the NYT's "more than $100 billion" year-end figure penciled in. On the trend that the third quarter implies, they get closer to $89 billion.
Here, one can argue here that the only way the previous growth rate can be recovered, is if Anthropic's token prices rebound strongly to pre-September levels. But for that to happen, the US government would need to "regulate" away Chinese open-source competition.
And now you know why both Anthropic and OpenAi are "passively" scaremongering each and every day in hopes of getting the Trump admin to block competition (because only China could be so irresponsible as to unleash an agent swarm hell bent on crushing everything in its path). Actually, make that "active": as we reported earlier, OpenAI CFO Sarah Friar is done beating around the bush, and is now on a crusade to eliminate cheaper competitors, warning businesses on Wednesday that adopting low-cost Chinese artificial intelligence models carries material cybersecurity risks, and telling Bloomberg that firms should prioritize Western models "on the cyber front."
Western models like... OpenAI course.
Then there is the profit claim, which will get most of the headlines and deserves the most asterisks. The FT doesn't say what was "adjusted," and the full S-1 with GAAP numbers isn't due publicly until around Oct 25. What we do know comes from the confidential prospectus reported by Reuters: a $42 billion net loss in 2025 (about $34 billion of it an accounting charge tied to financing), an operating loss of more than $8 billion, and at least $518 billion of compute and infrastructure commitments over the next decade, about 80% of them non-cancelable.
Also recall also the gross-vs-net debate that blew up OpenAI's numbers last week. As Goldman's TMT desk explained, "Anthropic reports closer to gross revenue (full customer spend through cloud partners, partner cut booked as a cost)." That flatters the top line relative to OpenAI's net reporting, and it makes any "adjusted" margin a function of what gets booked where. One quarter of positive adjusted profit and cash flow, ahead of a ~$2 trillion IPO and with the biggest compute bills still ahead (the Microsoft commitment doesn't even start until November), is a data point (and one that does not take into account subscriber churn, which is certainly a key issue among frontier labs where a new and improved model is released between the 4-5 leaders every other week like hot potatoes). It is certainly a long way from a track record.
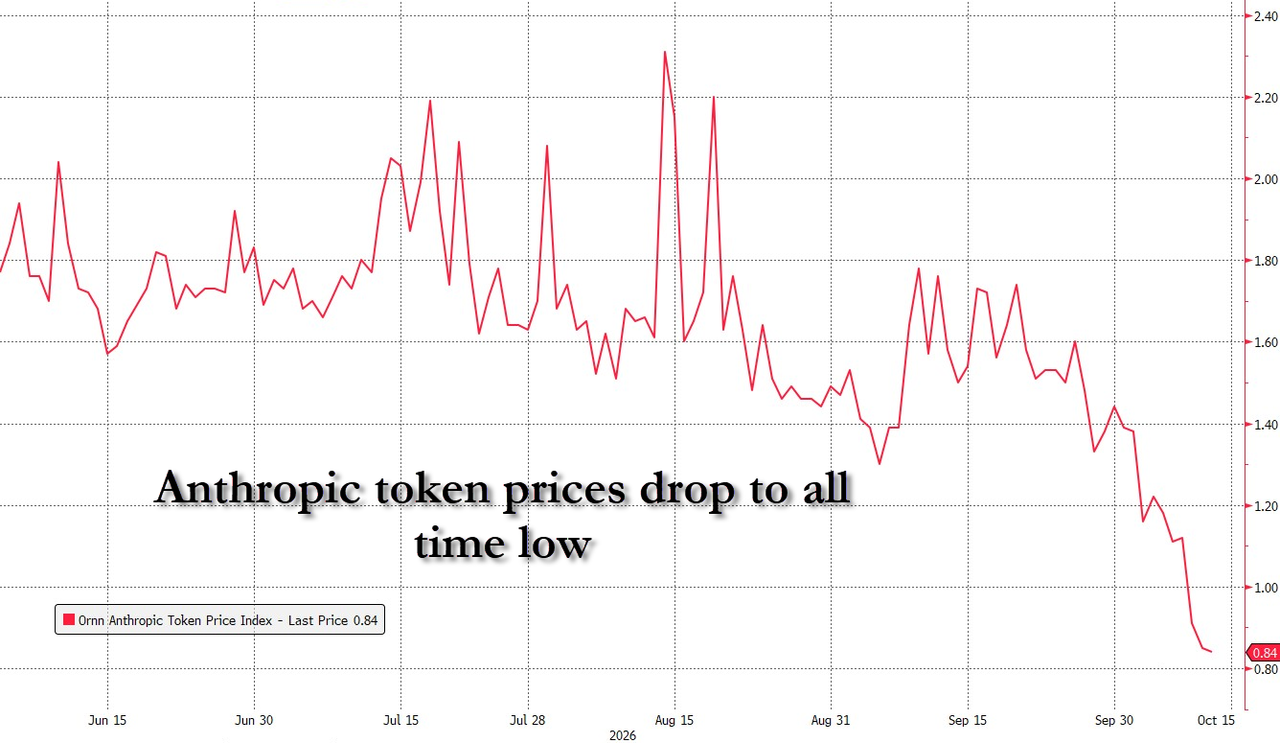
Pricing is the other moving part. Echoing what we said above, this morning we showed the Ornn Anthropic Token Price Index at a record low, and pointed out what that has meant historically:
If the Aug-Sep slowdown happened while prices were still relatively firm, a Q4 reacceleration has to come from a lot more volume at half the price. That is possible (Jevons and all), but it's a different business model than the one that delivered 33% a month.
That depends on which yardstick you use. Brad Gerstner's framework, which Goldman's desk resurfaced last week, has the top three labs needing to go from a combined ~$100 billion run rate in July to $180-200 billion by year-end "to keep the AI trade intact." One West Coast PM in yesterday's Bear Traps chat set the bar even higher: "you need to see OAI + ANTH combined ARR going to $200 - $300bn by mid 2027 for AI trade to work," adding that "Anthropic ARR number tomorrow better be huge---Everyone bracing for a bad number after the OpenAI debacle last week."
Well, today's number was good, but not huge. Take Anthropic at ~$74 billion and OpenAI at its own ~$50 billion end-September figure and you get roughly $124 billion combined, and that is mixing a gross number with a net one, which numerous hyperscalers will also want a piece of. On the Q3 trend (~$89 billion) plus OpenAI hitting its ≥$70 billion year-end target, the two labs end the year near $160 billion, short of Gerstner's bar even before you add SpaceX/xAI's contribution.
On valuation, the picture improves. At $2 trillion, Anthropic trades at about 27x its implied September exit rate and about 22x the ~$89 billion trend number for December, versus the ~47x trailing revenue multiple Breakingviews calculated two weeks ago. That is the bull pitch in one line, and it's the one investors heard today. The question is whether that flatline in growth shown above persists, or even reverses. That would be bad, and would explain why Anthropic is rushing to go public now.
This morning we asked whether Anthropic is going public from a position of strength or need. Tonight's answer is both: a $16.8 billion quarter, adjusted profits and positive cash flow are strength by any normal standard, and good enough to keep the November IPO on track. But the growth rate implied by that quarter fell from about a third per month to mid-single digits, and the $100 billion year-end number the market has been underwriting now requires Q4 growth to roughly double from the Aug-Sep pace, during a quarter when token prices are falling and Meta, Google and the Chinese open-weight labs are all crowding the frontier with their own deeply discounted offerings.
Which is why we think the November window will be set less by today's revenue print than by the credit market that is supposed to fund the next $518 billion. On a day when Oracle CDS blew out 31bps and CoreWeave's bonds traded at deeply distressed yields, a strong quarter from the most important tenant in the AI ecosystem is necessary. It may not be sufficient. Futures will tell us tomorrow whether one number can reattach the AI trade's right tail; the public S-1, due around Oct 25, will tell us what "adjusted" means.
Much more in today's Goldman "US Equities Color" and "CAS Mark to Market" notes and Matthew Kaplan's "A few observations from today," all available to pro subs.
Tyler Durden Wed, 10/14/2026 - 19:40
Continue reading...
[ H/T ZeroHedge ]
We got the number.
As we previewed this morning, the entire AI complex (if not the entire market) spent Wednesday waiting with bated breath for one data point out of Anthropic's closed-door pre-IPO investor day in San Francisco. Shortly after the close, the FT delivered: Anthropic told investors its third-quarter revenue had jumped to $16.8 billion, "almost 50 per cent" above the $11.5 billion recorded in the second quarter, and that the company was "profitable on an adjusted basis" and cash flow positive in the quarter.
Executives spent the full day laying out how "a safety-focused philosophy, rapid growth and efficiency gains" would set up a successful IPO in November.
On the surface, that is close to the "position of strength" JonesTrading's Mike O'Rourke said the market was looking for. And the timing could hardly be better for the bulls, because the AI trade spent the entire session before the headline getting taken to the woodshed.
A Brutal Session Before The Number
Goldman's US trading desk titled its close "UGLY" (available to pro subs): the S&P fell 1.11% to 7,719 and the NDX slid 2.02% to 29,950, the "first -1% SPX / -2% NDX move since late July," with "sentiment particularly within the AI complex taking a real step function lower" on:
The credit side was worse. Goldman's cross-asset desk reported "macro credit spreads widening the most in a single session in months," with Oracle CDS +31bps on the day, CoreWeave CDS exploding over 100 bps wider, hyperscaler cash bonds 4-5bps wider and datacenters 7bps wider. CoreWeave stock lost more than 15% (and almost 20% including the after hours dump), and as we noted in today's market wrap, the CDS market now assigns a 63% chance it defaults within five years. Semis meanwhile closed down for a sixth straight session, a streak Goldman's Matthew Kaplan flagged as uncommon:
Meanwhile, as everything AI got dumped, Goldman's S&P ex-AI basket rose 61bps, a 1.72-point spread over the index that ranks among the top five of the year:
In other words, the market spent the day cutting the "right tail off of the AI trade", in the words of Goldman's derivatives desk, and then Anthropic's number crossed after the close. The only question that matters now is whether the number reattaches that tail.
Back Out The Months
Start with the obvious. Annualize the quarter and you get about $67 billion, barely above the $65 billion run rate Anthropic told investors it had hit at the end of July. But Anthropic's run rate annualizes the most recent month, so the real question is where the company exited September, and that takes a little arithmetic.
Anchor on July, a process which the company is known to do by annualizing its latest (and greatest) month. Read the $65 billion end-July mark as July revenue × 12 and July comes to about $5.4 billion. That leaves roughly $11.4 billion for August and September combined ($16.8 billion − $5.4 billion), which fits steady growth of just ~3.4% a month: about $5.6 billion in August and $5.8 billion in September, or a September run rate of ~$69-70 billion.
The more generous reading treats $65 billion as the pace on July 31 rather than July's average. In that case July revenue was lower (closer to $5.2 billion, since it was still ramping), more of the quarter lands in August and September, and the implied growth rate rises to ~6.6% a month. September revenue × 12 still comes to only ~$71 billion, but the exit pace on Sep 30 works out to about $74 billion.
Either way, Anthropic exited the third quarter at somewhere between $69 billion and $74 billion, which is what TMT Breakout also calculated shortly after the FT headline. Now project it forward from the generous end of the range. At the same ~6.6% a month, the run rate reaches ~$89 billion by December. Hitting the $100 billion year-end bogey requires about 10.6% a month in Q4 from $74 billion, or 12.6% from $70 billion. That's the same conclusion Shanu Mathew reached: growth has decelerated, and the $100 billion target now needs Q4 to reaccelerate.
Incidentally, that is what the latest token data from Ramp AI shows: while AI usage is rapidly rising (per Jevon's Paradox), AI spend is actually flat at best, if not shrinking...
... as a result of tumbling token prices thanks to growing market share by open-source models; in fact as we showed earlier, token prices at Anthropic just hit an all time low suggesting that the price is dropping faster than the the company can convert higher volumes into revenue.
Put it all on one chart and the problem is plain to see: the line that went near-vertical through July on the initial burst of agentic euphoria and Tokenmaxxing has flattened, and the $100 billion IPO bogey sits about $10 billion above where the Aug-Sep pace gets you by December.
Here is the same deceleration in quarterly terms:
And here it is in monthly terms, which is where it really jumps out. Going from $9 billion at the end of 2025 to $65 billion at the end of July works out to roughly 33% compounded growth per month. Over August and September, the implied pace fell to 3.4%-6.6%. To reach the "more than $100 billion" year-end figure the NYT reported last month, Anthropic now needs ~10.6%-12.6% a month in Q4, depending on whether it exited at $74 billion or $70 billion:
To be clear, 46% sequential growth on a $46 billion base (Q2 annualized) is extraordinary by the standards of any company that has ever existed. The issue is the bar, which Anthropic itself set: going into the meeting, much of the Street had the NYT's "more than $100 billion" year-end figure penciled in. On the trend that the third quarter implies, they get closer to $89 billion.
Here, one can argue here that the only way the previous growth rate can be recovered, is if Anthropic's token prices rebound strongly to pre-September levels. But for that to happen, the US government would need to "regulate" away Chinese open-source competition.
And now you know why both Anthropic and OpenAi are "passively" scaremongering each and every day in hopes of getting the Trump admin to block competition (because only China could be so irresponsible as to unleash an agent swarm hell bent on crushing everything in its path). Actually, make that "active": as we reported earlier, OpenAI CFO Sarah Friar is done beating around the bush, and is now on a crusade to eliminate cheaper competitors, warning businesses on Wednesday that adopting low-cost Chinese artificial intelligence models carries material cybersecurity risks, and telling Bloomberg that firms should prioritize Western models "on the cyber front."
Western models like... OpenAI course.
"Adjusted" Profitable
Then there is the profit claim, which will get most of the headlines and deserves the most asterisks. The FT doesn't say what was "adjusted," and the full S-1 with GAAP numbers isn't due publicly until around Oct 25. What we do know comes from the confidential prospectus reported by Reuters: a $42 billion net loss in 2025 (about $34 billion of it an accounting charge tied to financing), an operating loss of more than $8 billion, and at least $518 billion of compute and infrastructure commitments over the next decade, about 80% of them non-cancelable.
Also recall also the gross-vs-net debate that blew up OpenAI's numbers last week. As Goldman's TMT desk explained, "Anthropic reports closer to gross revenue (full customer spend through cloud partners, partner cut booked as a cost)." That flatters the top line relative to OpenAI's net reporting, and it makes any "adjusted" margin a function of what gets booked where. One quarter of positive adjusted profit and cash flow, ahead of a ~$2 trillion IPO and with the biggest compute bills still ahead (the Microsoft commitment doesn't even start until November), is a data point (and one that does not take into account subscriber churn, which is certainly a key issue among frontier labs where a new and improved model is released between the 4-5 leaders every other week like hot potatoes). It is certainly a long way from a track record.
Pricing is the other moving part. Echoing what we said above, this morning we showed the Ornn Anthropic Token Price Index at a record low, and pointed out what that has meant historically:
If the Aug-Sep slowdown happened while prices were still relatively firm, a Q4 reacceleration has to come from a lot more volume at half the price. That is possible (Jevons and all), but it's a different business model than the one that delivered 33% a month.
Enough To Save The AI Trade?
That depends on which yardstick you use. Brad Gerstner's framework, which Goldman's desk resurfaced last week, has the top three labs needing to go from a combined ~$100 billion run rate in July to $180-200 billion by year-end "to keep the AI trade intact." One West Coast PM in yesterday's Bear Traps chat set the bar even higher: "you need to see OAI + ANTH combined ARR going to $200 - $300bn by mid 2027 for AI trade to work," adding that "Anthropic ARR number tomorrow better be huge---Everyone bracing for a bad number after the OpenAI debacle last week."
Well, today's number was good, but not huge. Take Anthropic at ~$74 billion and OpenAI at its own ~$50 billion end-September figure and you get roughly $124 billion combined, and that is mixing a gross number with a net one, which numerous hyperscalers will also want a piece of. On the Q3 trend (~$89 billion) plus OpenAI hitting its ≥$70 billion year-end target, the two labs end the year near $160 billion, short of Gerstner's bar even before you add SpaceX/xAI's contribution.
On valuation, the picture improves. At $2 trillion, Anthropic trades at about 27x its implied September exit rate and about 22x the ~$89 billion trend number for December, versus the ~47x trailing revenue multiple Breakingviews calculated two weeks ago. That is the bull pitch in one line, and it's the one investors heard today. The question is whether that flatline in growth shown above persists, or even reverses. That would be bad, and would explain why Anthropic is rushing to go public now.
Bottom Line
This morning we asked whether Anthropic is going public from a position of strength or need. Tonight's answer is both: a $16.8 billion quarter, adjusted profits and positive cash flow are strength by any normal standard, and good enough to keep the November IPO on track. But the growth rate implied by that quarter fell from about a third per month to mid-single digits, and the $100 billion year-end number the market has been underwriting now requires Q4 growth to roughly double from the Aug-Sep pace, during a quarter when token prices are falling and Meta, Google and the Chinese open-weight labs are all crowding the frontier with their own deeply discounted offerings.
Which is why we think the November window will be set less by today's revenue print than by the credit market that is supposed to fund the next $518 billion. On a day when Oracle CDS blew out 31bps and CoreWeave's bonds traded at deeply distressed yields, a strong quarter from the most important tenant in the AI ecosystem is necessary. It may not be sufficient. Futures will tell us tomorrow whether one number can reattach the AI trade's right tail; the public S-1, due around Oct 25, will tell us what "adjusted" means.
Much more in today's Goldman "US Equities Color" and "CAS Mark to Market" notes and Matthew Kaplan's "A few observations from today," all available to pro subs.
Tyler Durden Wed, 10/14/2026 - 19:40
Continue reading...
[ H/T ZeroHedge ]